Key Findings
- Europe circular plastics market volume is projected to increase from 7.9 million tons in 2024 to 12.7 million tons by 2033.
- Market volume is expected to expand at a 5.7% CAGR during 2027 to 2033, indicating sustained growth in circular material adoption.
- Market value is projected to rise from USD 14.6 billion in 2024 to USD 26.1 billion by 2033.
- Average circular plastics pricing is expected to increase from USD 1,850 per ton in 2024 to USD 2,050 per ton by 2033.
- The Europe circular plastics market is increasingly influenced by recycled content requirements, recycling capacity expansion and converter demand.
- Feedstock availability and quality remain critical factors affecting the scalability of European recycling operations.
- Competition from lower priced virgin polymers and imported recyclates can constrain recycled polymer pricing and recycler margins.
- Mechanical recycling remains commercially important, while chemical and advanced recycling technologies create opportunities for difficult to recycle plastic streams.
- Germany, Italy, France, Spain, the Netherlands and Poland represent important country level opportunities based on plastics consumption, recycling infrastructure and downstream demand.
Europe Circular Plastics Market Outlook
Europe Circular Plastics Market recorded a sales volume of 8.3 million tons in 2025 and is estimated to reach a volume of 12.7 million tons by 2033 with a CAGR of 5.7% during the forecast period.
Europe Circular Plastics Market Dynamics
Expansion of deposit return systems
The expansion of deposit return systems is strengthening the feedstock economics of the Europe circular plastics market by shifting beverage packaging collection from mixed municipal waste toward dedicated recovery streams. The most important effect is not simply higher collection volumes, but improved material quality, traceability and suitability for closed loop recycling. Poland illustrates the scale of this transition: its deposit return system became operational in October 2025 and had collected around 1.6 billion beverage containers by May 2026, supported by approximately 62,000 collection points and 13,000 reverse vending machines.
For the Europe circular plastics market, this infrastructure can materially improve the economics of PET recycling because separately collected bottles generally require less intensive sorting than material recovered from mixed waste. It also creates a more predictable feedstock stream for recyclers, allowing investment decisions to be based on contracted collection volumes rather than uncertain municipal waste availability. However, the commercial impact will depend on how effectively collected material is converted into high quality recyclate and retained within European value chains. Deposit systems therefore represent more than a waste collection mechanism: they can become a supply infrastructure for bottle to bottle recycling. As additional European markets expand or strengthen deposit systems, recyclers and packaging converters could gain greater access to consistent post consumer feedstock, while brand owners obtain a more reliable source of recycled PET needed to meet recycled content requirements. The strategic opportunity is consequently strongest where collection, sorting, washing, pelletization and packaging conversion are integrated into regional circular supply chains.
Virgin polymer price competition
Virgin polymer price competition is becoming a structural constraint on the Europe circular plastics market, particularly when lower virgin resin prices reduce the economic incentive for converters to substitute recycled material. The issue is not simply the absolute price of virgin polymers, but the spread between virgin and recycled grades after accounting for quality, certification, processing and compliance costs. Plastics Europe reports that European plastics production was 54.9 Mt in 2024, while circular production reached 8.7 Mt, or 15.8% of total production. However, circular production increased only 2.4% between 2022 and 2024, while circular production growth slowed to 1.2% annually over the period.
The competitive pressure becomes stronger when imported virgin polymers enter Europe at prices that domestic circular producers cannot economically match. The United States accounted for 18.9% of European polymer imports in 2024, while the EU polymer trade balance remained negative at 0.2 Mt. Consequently, recyclers may face pressure to reduce selling prices even as European operating costs remain elevated. High energy, feedstock and emissions costs are already identified as factors undermining European plastics competitiveness. For the Europe circular plastics market, this creates a critical commercial requirement: recycled polymers need either a sufficiently narrow price differential with virgin grades or a regulatory and performance advantage that justifies the premium. PPWR driven recycled content requirements can support demand, but they do not completely eliminate price sensitivity among converters. Therefore, the competitiveness of circular plastics will increasingly depend on reducing processing costs, improving recyclate quality and securing stable feedstock rather than relying solely on sustainability driven purchasing.
Europe Circular Plastics Market: Recycled Polymer Price Analysis
Recycled polymer pricing in the Europe circular plastics market is increasingly determined by the spread between secondary and virgin resin prices rather than by waste availability alone. In 2024, Europe produced approximately 8.7 million tonnes of circular plastics, equivalent to 15.8% of total plastics production, while converter demand for circular plastics reached approximately 7.9 million tonnes. This creates a market where pricing depends heavily on polymer grade, feedstock quality, processing intensity, certification and application requirements. PET generally commands stronger pricing in applications where food contact quality and bottle to bottle recycling create specification driven demand, while recycled PE and PP can experience greater price pressure because converters can substitute between recycled and competitively priced virgin grades. The pricing challenge becomes more pronounced when virgin polymer prices decline, narrowing the premium that recyclers can capture despite higher collection, sorting and processing costs.
The Europe circular plastics market therefore has a structural pricing tension: converter demand is expanding faster than European circular production, but imported recyclates and virgin polymers constrain how much producers can increase prices. Plastics Europe reports that 12.4% of collected European plastic waste was recycled outside Europe, while approximately 19% of converter demand for circular plastics was supplied through imports, highlighting the importance of international price competition. For recyclers, the most defensible pricing position is likely to remain in high specification applications where traceability, recycled content compliance and consistent polymer performance create measurable value. Conversely, commodity grade recycled polymers face greater exposure to virgin resin cycles. This means future pricing performance in the Europe circular plastics market will depend increasingly on feedstock efficiency, plant utilization, quality consistency and long term offtake agreements rather than simply rising demand for recycled materials.
Europe Circular Plastics Market:Import Dependency Analysis
Import dependency is becoming an important structural issue for the Europe circular plastics market because domestic recycling capacity is not expanding at the same pace as converter requirements for recycled polymers. The imbalance is particularly relevant for high quality secondary materials required by packaging and other regulated applications, where European converters need consistent specifications, traceability and reliable supply. Imports can therefore fill short term material shortages, but they also expose European buyers to international resin pricing, freight costs, currency movements and changing trade conditions. This creates a dual effect. Imports improve material availability and prevent supply constraints from limiting recycled content adoption, while simultaneously reducing the pricing power of European recyclers. The strategic issue is therefore less about eliminating imports and more about determining which recycled polymer streams Europe can competitively produce domestically and which will remain structurally dependent on external suppliers.
For the Europe circular plastics market, import dependency also creates a strategic opportunity for domestic capacity expansion. Recyclers able to secure high quality post consumer feedstock and establish long term relationships with converters can potentially replace part of the imported supply while benefiting from shorter logistics chains and stronger traceability. However, domestic production will only displace imports sustainably if European facilities can achieve competitive conversion costs and consistent material specifications. This is particularly important for PE and PP, where recycled grades compete directly with virgin polymers and imported recyclates on price. The market therefore needs to distinguish between volume dependency and specification dependency. Some imports may be unavoidable because particular recycled grades or quality levels are not sufficiently available domestically. For the Europe circular plastics market, reducing strategic import exposure will consequently require targeted investment in sorting, washing, advanced recycling and polymer upgrading rather than simply adding recycling capacity. The greatest opportunity lies in converting European waste that is currently exported or inadequately processed into locally available, specification compliant recycled polymers.
Europe Circular Plastics Market: Plastic Circularity Funnel
The Europe circular plastics market can be better understood through a material flow funnel that identifies where plastic resources are lost between collection and reintegration into new products. In 2024, Europe recycled 9.7 million tonnes of collected plastic waste, equivalent to a 29.6% recycling rate, while 70.4% continued to landfill or incineration. This indicates that the principal constraint is not simply the availability of plastic waste, but the conversion of collected material into usable circular feedstock. The funnel narrows further at the conversion stage, where European converters used 7.9 Mt of circular plastics, representing 15.1% of total plastics processed. The gap between collected waste, recycled material and circular plastics incorporated into products highlights losses arising from contamination, sorting limitations, material degradation and unsuitable waste streams.
For the Europe circular plastics market, the funnel demonstrates why increasing collection alone will not automatically produce equivalent growth in circular polymer consumption. Europe exported 1.5 Mt of sorted plastic waste in 2024, while 19% of circular plastics used by converters relied on imports. This creates a structural mismatch in which European waste resources can leave the region while converters simultaneously source circular materials from external markets. The largest opportunity therefore lies in improving the middle stages of the funnel: advanced sorting, washing, purification, polymer separation and conversion into application ready recyclates. Closing these gaps could increase domestic feedstock utilization without requiring proportional growth in total plastic waste generation. The Europe circular plastics market will consequently depend increasingly on improving conversion efficiency and retaining valuable secondary materials within European supply chains.
Europe Circular Plastics Market: Country Analysis
Country performance in the Europe circular plastics market is increasingly shaped by differences in recycling infrastructure, industrial demand, waste collection systems and access to secondary raw materials. The European landscape is therefore not uniform. Germany combines a large plastics converting base with extensive recycling infrastructure, while Italy has a strong plastics manufacturing ecosystem and substantial recycling activity. The Netherlands benefits from its logistics position and established plastics processing network, whereas France has a large packaging market and significant regulatory pressure to increase circular material use. Spain has been expanding collection and recycling infrastructure, while Poland is becoming increasingly relevant because of its large manufacturing base and the rollout of its deposit return system. These differences mean that countries with similar waste generation can present very different investment opportunities depending on how efficiently collected material is converted into marketable recyclates.
For the Europe circular plastics market, Germany remains strategically important because its scale supports investment in collection, sorting and recycling, while Italy's established plastics processing industry creates downstream demand for recycled polymers. The Netherlands has a different advantage: its ports and logistics infrastructure can facilitate movement of waste, recyclates and polymer products across European markets. Poland presents a particularly interesting growth case because its manufacturing sector creates potential domestic demand while the new deposit return system can strengthen access to separated beverage packaging feedstock. France and Spain offer opportunities linked to packaging circularity and infrastructure expansion.
The key investment distinction is therefore between mature circular markets and capacity expansion markets. Germany, Italy and the Netherlands offer established ecosystems where consolidation, technology upgrades and higher value recycling can be attractive. Poland and Spain offer greater potential for infrastructure expansion and feedstock capture. For the Europe circular plastics market, country attractiveness should consequently be assessed using a combination of recycling capacity, converter demand, feedstock availability, import dependency, regulatory requirements and investment pipeline rather than market size alone.
Competitive Analysis
Key companies analyzed within the Europe circular plastics market are: Veolia, Suez, TOMRA, ALPLA, Borealis, Paprec Group, PreZero, Interzero, BASF, LyondellBasell, Others.
The competitive structure of the Europe circular plastics market is increasingly shaped by companies controlling different stages of the circular value chain rather than by recyclers alone. Veolia and SUEZ are positioned around waste collection, treatment and recycled material production, while TOMRA provides advanced sorting infrastructure that determines the quality of feedstock entering recycling. SUEZ currently reports 80,000 tonnes of recycled plastics placed on the market and 136,000 tonnes of plastic waste processed, while its European recycling portfolio includes PET, PVC and LDPE. ALPLA has developed substantial post consumer recycling capability, reporting 350,000 tonnes of recycling capacity and a global network spanning multiple European countries. Borealis is pursuing a polymer producer led model, with 227,900 tonnes of circular solutions capacity established in 2024 and 221,200 tonnes of circular feedstock processed.
Paprec operates 12 plastics recovery plants and collects around 300,000 tonnes of plastic annually, while Interzero operates five major sorting facilities with combined capacity of 810,000 tonnes per year. PreZero reports 123,702 tonnes of recycled plastic within its recycled raw material output. TOMRA's Områ facility adds 90,000 tonnes per year of plastic sorting capability in Norway. The competitive opportunity for the Europe circular plastics market therefore increasingly lies in vertical integration, where companies can secure feedstock, improve sorting yields, produce specification compliant recyclates and establish direct offtake relationships with converters and brand owners.
Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) evaluates companies in the Europe circular plastics market based on their ability to secure feedstock, scale recycling capacity, produce consistent recycled polymers and integrate downstream demand. The framework gives greater weight to operational capabilities than to corporate size because circular plastics competitiveness depends on material throughput, technology depth and access to converters. Capacity and recycling footprint receive 25%, reflecting the importance of processing scale; feedstock access receives 20%, given that quality post consumer material is a major constraint; technology capability receives 20%, covering mechanical, chemical and advanced sorting technologies; downstream integration receives 15%, assessing relationships with polymer producers, converters and brand owners; geographic coverage receives 10%; and regulatory and certification capability receives 10%. Companies are scored from 1 to 5 against each parameter, producing a weighted competitive score out of 100.
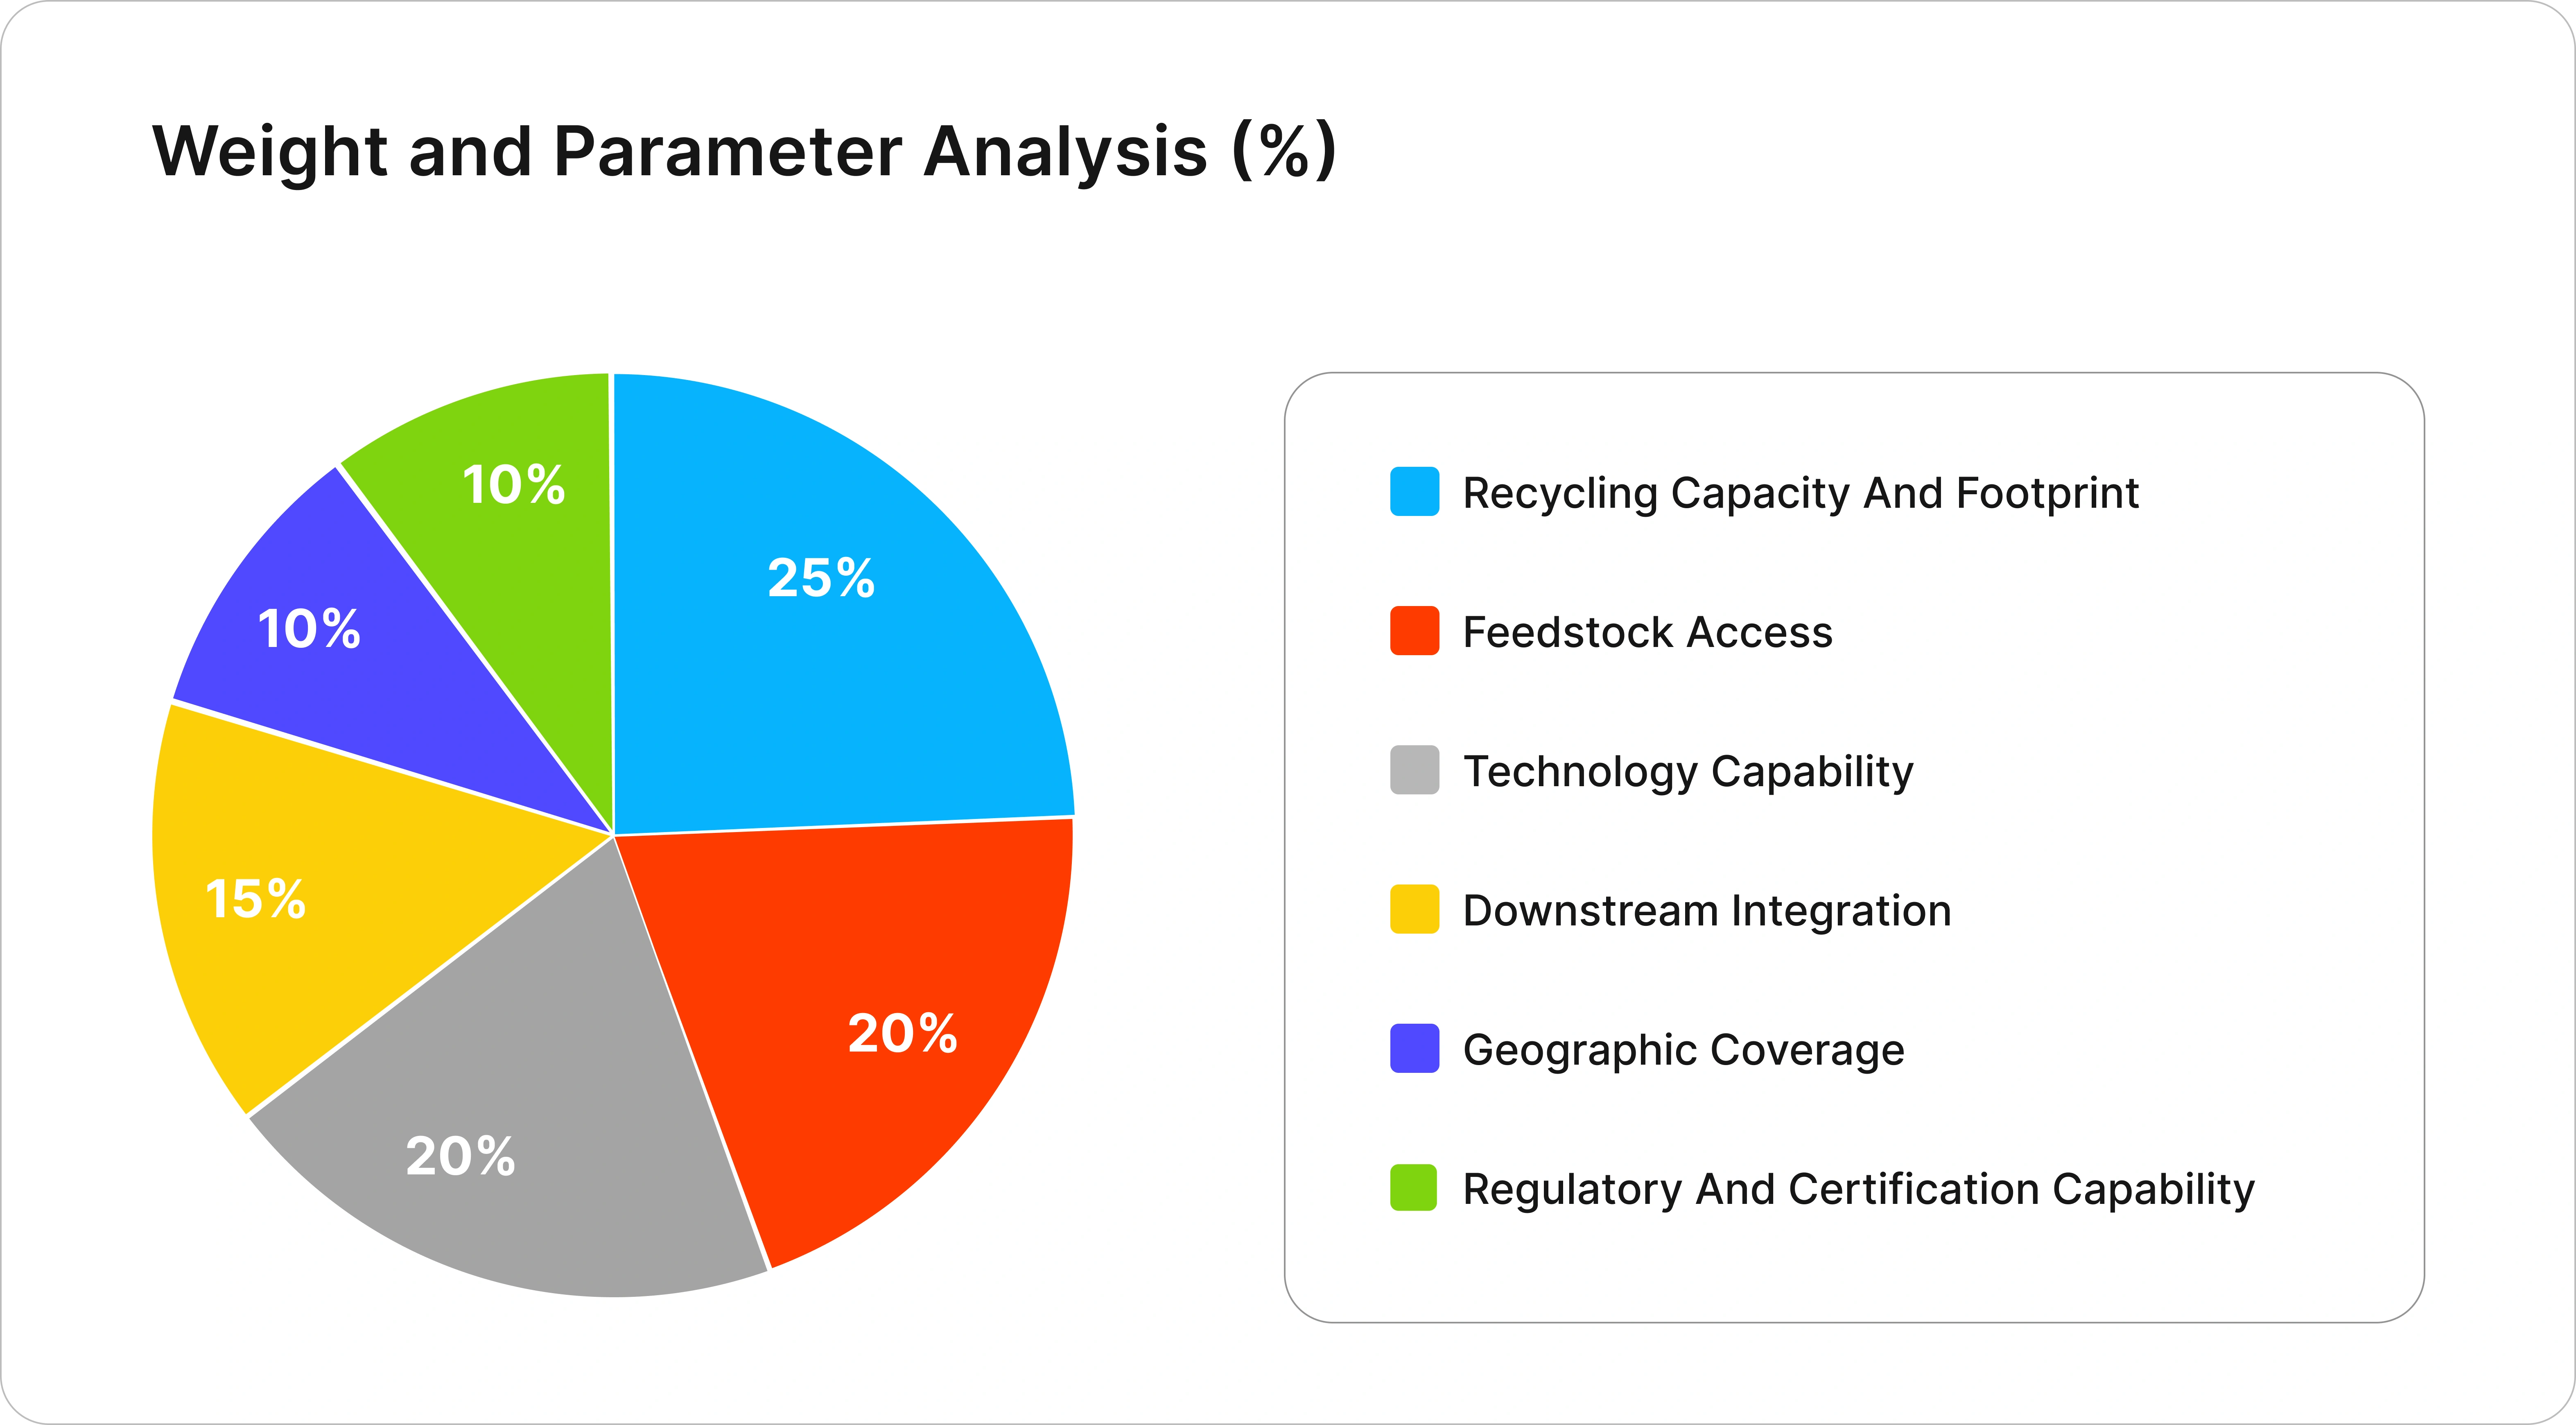
Within the Europe circular plastics market, this framework helps distinguish companies with large waste management networks from those with stronger polymer production or advanced recycling capabilities. It is particularly useful for identifying which players are best positioned to capture growth created by recycled content requirements, higher quality recyclate demand and investment in advanced recycling infrastructure.

