Key Findings
- The Europe biopolymers market was valued at USD 2.55 billion in 2025 and is projected to reach USD 3.96 billion by 2033, expanding at a CAGR of 5.4% during 2027–2033.
- Market consumption is expected to increase from 800 thousand tons in 2025 to approximately 1.28 million tons by 2033, reflecting a 6.3% volume CAGR driven by expanding industrial adoption.
- Packaging remains the dominant end-use industry, accounting for more than 40% of total biopolymer demand, supported by EU sustainability regulations and compostable packaging initiatives.
- Polylactic Acid (PLA) leads the product portfolio, followed by starch blends and PBAT, collectively representing the majority of regional biopolymer consumption.
- Average selling prices are forecast to remain relatively stable, ranging between USD 3,100 and USD 3,260 per ton through 2033, indicating improving manufacturing efficiencies despite growing demand.
- Germany is the largest country market, while France, Italy, the United Kingdom, and the Netherlands remain key growth hubs due to strong manufacturing bases and circular economy investments.
Europe Biopolymers Market Overview
Europe Biopolymers Market recorded a sales volume of 800 thousand metric tons in 2025 and is estimated to reach a volume of 1,277 thousand metric tons by 2033 with a CAGR of 6.3% during the forecast period.
Europe Biopolymers Industry Dynamics
Expansion of chemical recycling and organic waste collection infrastructure supporting certified compostable plastics
The expansion of chemical recycling facilities and organic waste collection infrastructure is emerging as a key growth driver for the European biopolymers market. This development addresses a significant challenge within the industry: the effective end-of-life management of bio-based and compostable plastics. With the introduction of mandatory separate bio-waste collection under the revised EU Waste Framework Directive starting January 2024, there is a growing availability of industrial composting streams that can process certified compostable materials.
According to the European Commission, municipal waste generation in the EU amounts to over 225 million tonnes annually, with bio-waste representing approximately 30–40% of mixed household waste. The expansion of separate collection systems is facilitating the diversion of compostable packaging, food-service items, and organic waste bags made from PLA, PBAT, starch blends, and other biodegradable polymers away from landfills and conventional recycling streams, enhancing resource recovery and minimizing contamination.
Simultaneously, Europe is making substantial investments in advanced recycling technologies. Industry organizations report that more than 100 chemical recycling projects are either announced or in development across the continent, targeting hard-to-recycle plastic waste through methods such as pyrolysis, depolymerization, and solvent-based recycling processes. While chemical recycling primarily focuses on conventional plastics, the investments are enhancing waste sorting infrastructure, traceability systems, and polymer recovery technologies, which also benefit bio-based materials.
Additionally, certification standards like EN 13432 are fostering greater confidence among packaging manufacturers and municipalities by establishing harmonized requirements for industrial compostability. This has enabled wider commercial acceptance of certified compostable products. Countries such as Germany, Italy, the Netherlands, and France are increasing their industrial composting capabilities alongside food waste collection programs, creating favorable conditions for compostable packaging applications.
For manufacturers, this strengthened infrastructure helps to alleviate uncertainties regarding product disposal while ensuring compliance with the evolving EU circular economy policies. As investments continue in recycling facilities, composting plants, and waste collection networks, the European biopolymers market is poised to benefit from enhanced downstream infrastructure, leading to higher adoption rates, greater regulatory acceptance, and increased demand for certified compostable polymers across packaging, food service, retail, and agricultural sectors.
Complex certification requirements for compostability, biodegradability, and food-contact compliance
The complex certification requirements for compostability, biodegradability, and food-contact compliance present a significant challenge for the biopolymers market in Europe. Manufacturers are tasked with meeting multiple regulatory and technical standards before their products can be introduced commercially across various applications. Unlike conventional plastics, biopolymers designated for packaging, food service, agriculture, or medical use must demonstrate compliance with specific European regulations and harmonized standards.
For instance, industrially compostable packaging is required to meet the EN 13432 standards, which assess factors such as biodegradation, disintegration, ecotoxicity, and heavy metal content under controlled composting conditions. Food-contact biopolymers are also subject to the Regulation (EC) No. 1935/2004 and, as applicable, the Commission Regulation (EU) No. 10/2011, which governs plastic materials meant for contact with food. The pathways for obtaining these certifications involve extensive laboratory testing, migration analysis, toxicological assessments, and third-party verification, all of which increase both product development timelines and commercialization costs.
The situation is further complicated by the fact that biodegradability claims can vary based on disposal conditions, often requiring different certifications for industrial composting, home composting, soil biodegradation, or marine environments. Manufacturers aiming to market their products across various European countries may also be required to acquire certifications from recognized organizations such as TÜV Austria or DIN CERTCO, adding an additional layer of administrative complexity.
This regulatory burden can be particularly challenging for small and medium-sized enterprises, which constitute a significant portion of Europe's plastics converting industry, as the costs associated with certification can be a substantial part of their overall product development budgets. Simultaneously, stricter enforcement against misleading environmental claims under evolving EU sustainability legislation highlights the importance of scientifically validated certification, thereby limiting opportunities for unsupported "green" marketing.
While these standards help enhance consumer confidence and product quality, they also slow the commercialization of innovative materials and necessitate a continuous investment in regulatory expertise and product testing. As the European Union continues to refine its packaging, sustainability, and food safety legislation under initiatives such as the Circular Economy Action Plan and the Packaging and Packaging Waste Regulation, compliance requirements are anticipated to become even more comprehensive. Consequently, navigating these certification frameworks will remain both a competitive differentiator and an operational challenge for companies in the biopolymers market throughout Europe.
Europe Biopolymers Market Pricing Analysis
The pricing trajectory of the European biopolymers market shows a gradual shift from cost inflation towards improved manufacturing efficiency and increased supply availability throughout the forecast period. Average selling prices are projected to rise from USD 3,150 per ton in 2024 to USD 3,260 per ton in 2027. This increase reflects the ongoing commercialization of higher-value biopolymers, including polyhydroxyalkanoates (PHA), bio-based polyamides, and specialized polylactic acid (PLA) grades that cater to medical, automotive, and high-performance packaging applications.
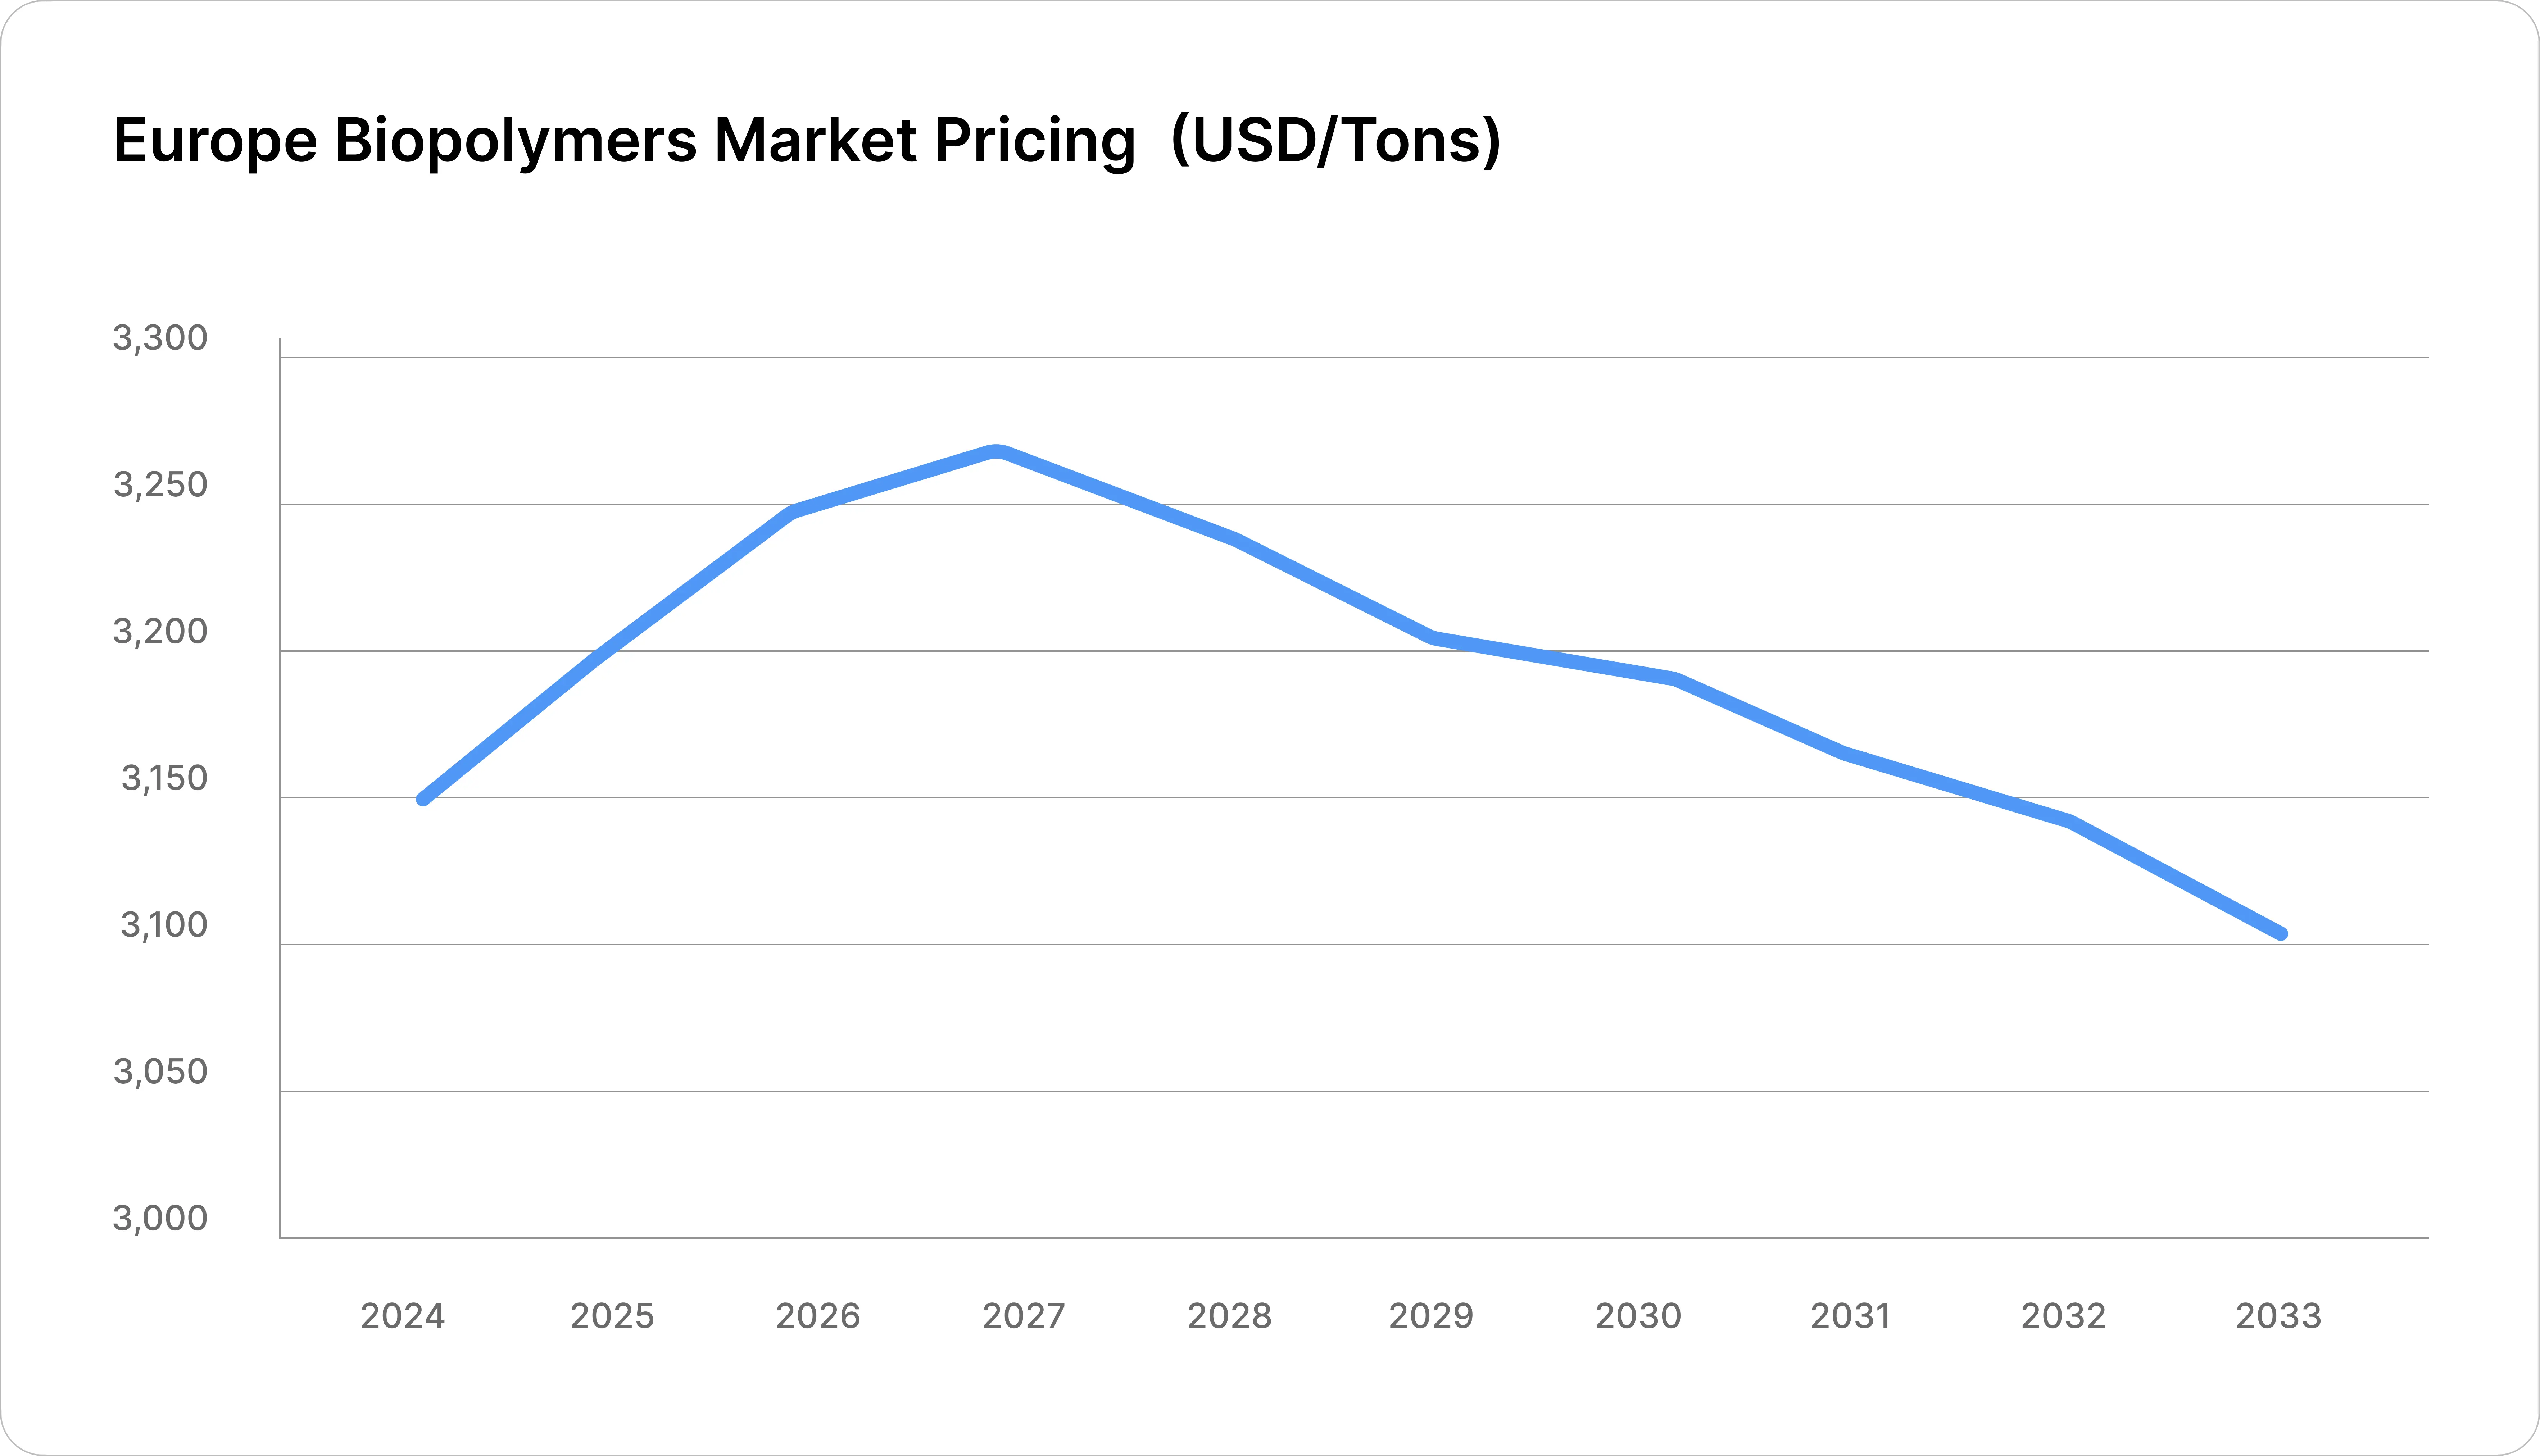
During this timeframe, manufacturers are expected to absorb elevated feedstock costs associated with sugar, starch, vegetable oils, and cellulosic biomass. Investments in advanced fermentation technologies and downstream purification processes contribute to relatively high production costs. However, after peaking in 2027, average prices are anticipated to gradually decrease to around USD 3,100 per ton by 2033, marking a decline of approximately 4.9% from the peak. This moderation is primarily driven by an increase in production capacity across Europe, improved economies of scale, and heightened competition among suppliers as new facilities for PLA, PBAT, and other bio-based polymers come online.
The integration of second-generation feedstocks, such as agricultural residues and lignocellulosic biomass, is also expected to diminish reliance on food-based raw materials, enhancing cost stability. Continuous improvements in process efficiency, higher plant utilization rates, and automation in polymer manufacturing are further contributing to the reduction of unit production costs without compromising product performance.
At the same time, expanding demand from packaging, consumer goods, textiles, and agriculture mitigates sharp price declines despite capacity additions, as regulatory support for sustainable materials strengthens market fundamentals. The relatively narrow price range between USD 3,100 and USD 3,260 per ton throughout the forecast period indicates that the industry is moving into a phase of balanced supply and demand, avoiding significant price volatility.
For manufacturers and downstream converters, this stable pricing environment facilitates long-term procurement planning, investment decisions, and the commercialization of bio-based products. Consequently, the pricing outlook underscores the long-term competitiveness and commercial maturity of the European biopolymers market as production volumes increase and manufacturing technologies continue to advance.
Segment & Country Analysis
Market Share Analysis of Bio-PE, PLA, PHA, PBAT, and Other Biopolymers in Europe
The Europe biopolymers market is significantly influenced by Polylactic Acid (PLA), which is estimated to account for 26.8% of total market demand by 2025. PLA has secured a strong commercial foothold due to its widespread applications in rigid food packaging, thermoformed trays, disposable food-service products, and 3D printing filaments. Its increasing adoption is bolstered by advancements in heat resistance and mechanical performance, enabling it to replace traditional petroleum-based plastics across a broader range of applications.
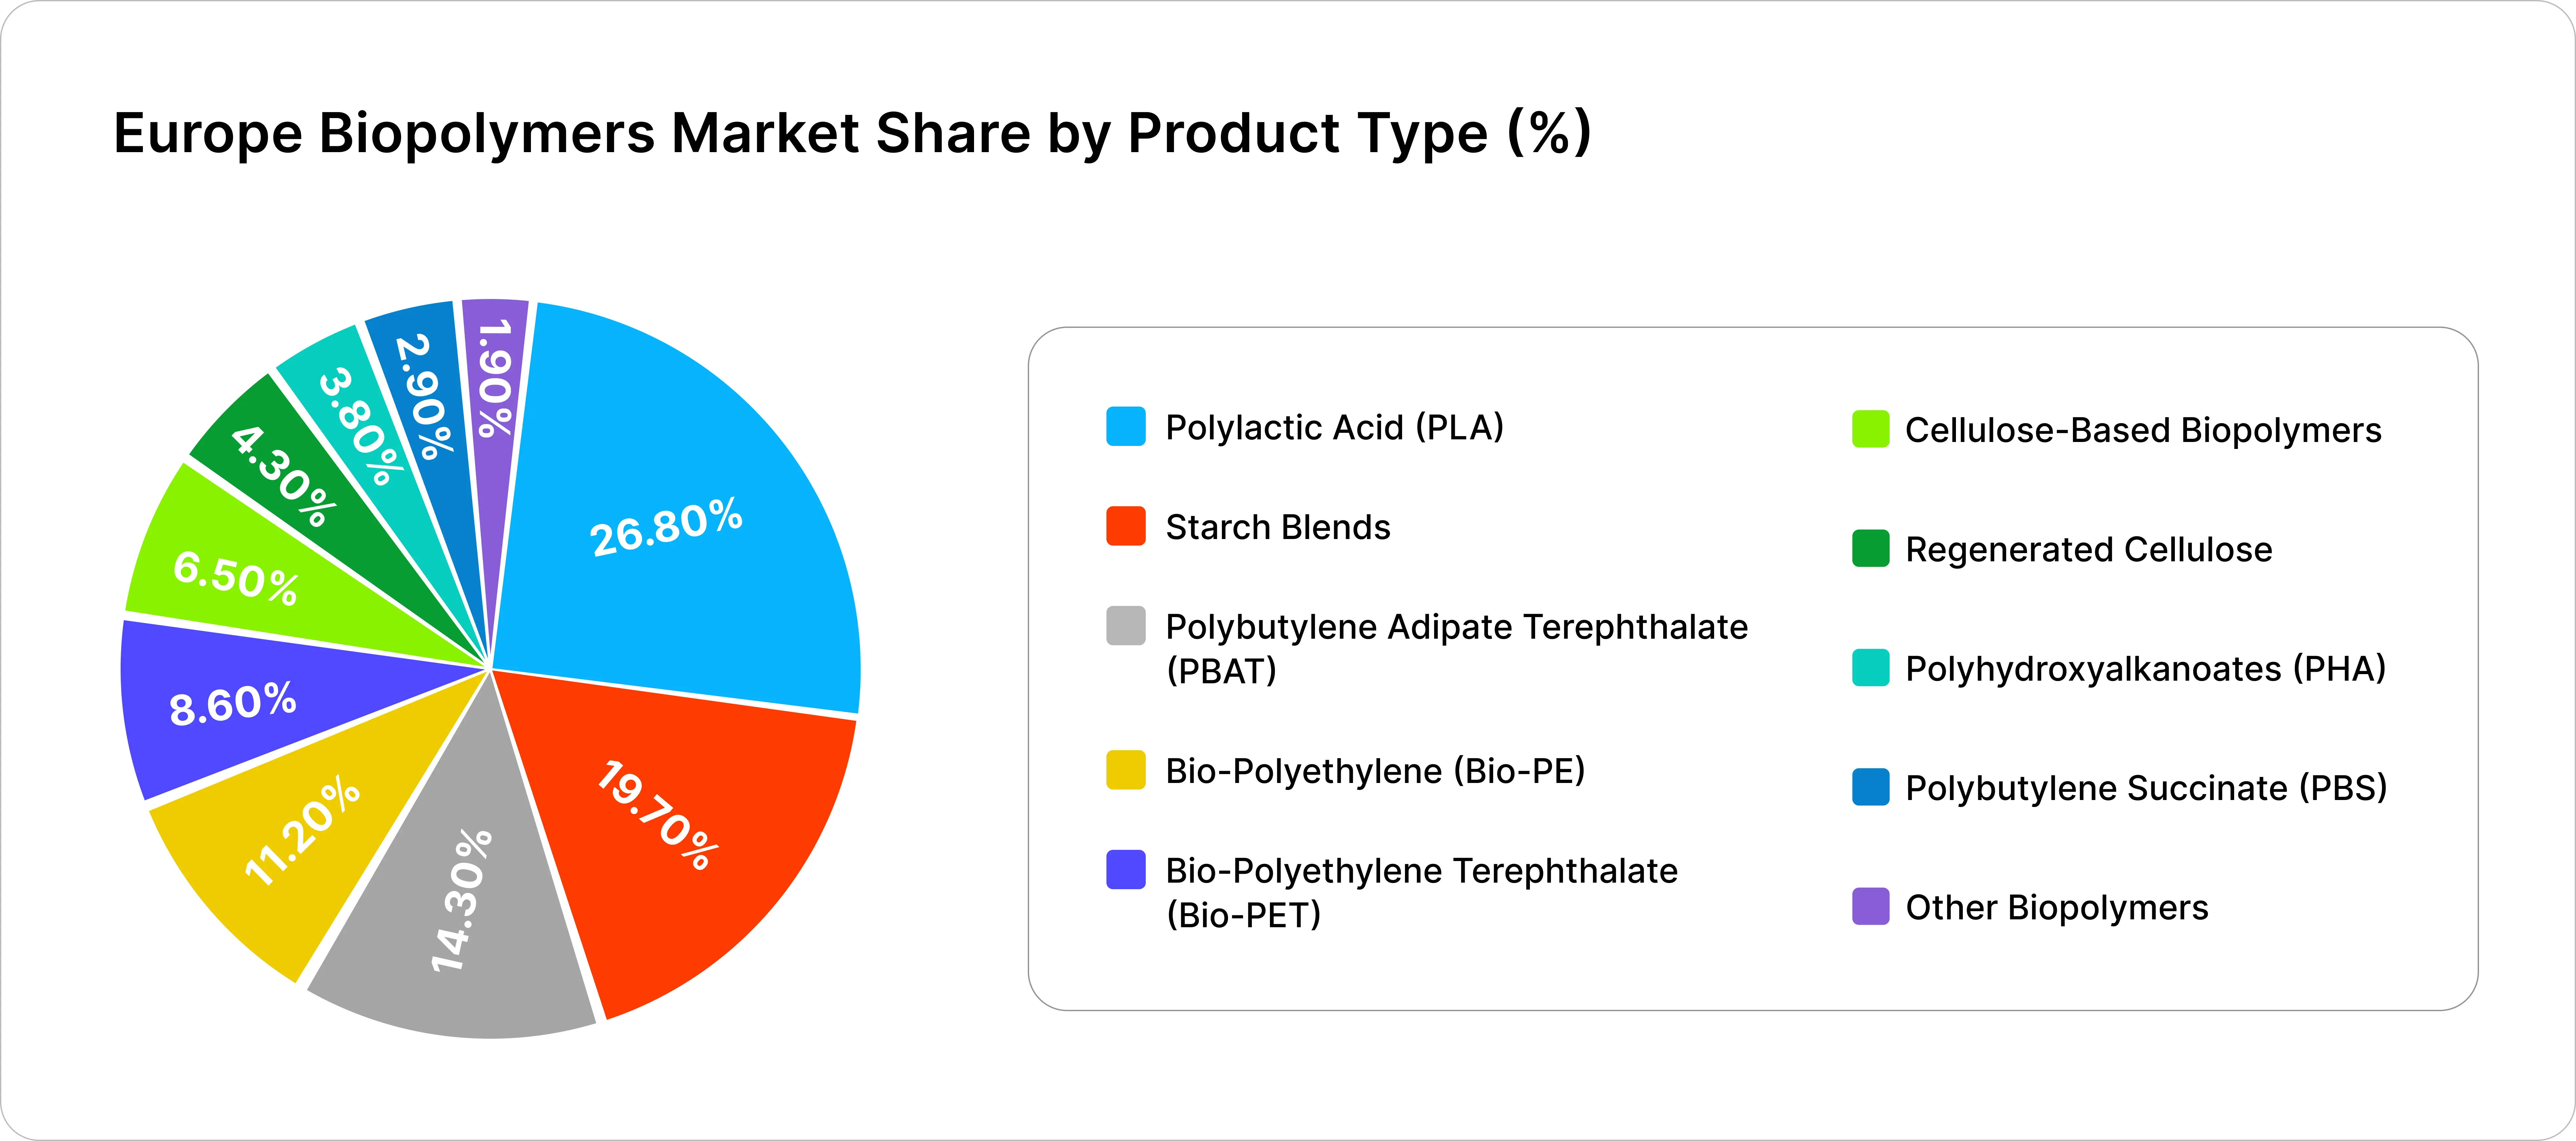
Starch blends hold the position of the second-largest segment, contributing approximately 19.7% of the market share. Their popularity stems from their common use in compostable shopping bags, organic waste collection bags, and agricultural mulch films. These materials benefit from recognized industrial compostability certifications and a robust demand from municipalities initiating separate bio-waste collection systems throughout Europe.
PBAT, with a 14.3% market share, has established itself as an essential biodegradable polymer, offering flexibility and impact resistance when blended with PLA or starch. This characteristic makes it particularly suitable for flexible packaging and compostable films. Concurrently, Bio-PE and Bio-PET together account for nearly 20% of market demand, reflecting the rising investments from consumer goods and beverage companies aiming for renewable-content packaging while ensuring compatibility with existing recycling systems.
Although PHA currently represents only 3.8% of the market, it is anticipated to experience one of the highest growth rates in the coming decade due to its ability to biodegrade in diverse environments, including marine conditions, along with its applicability in medical and specialty packaging.
Cellulose-based materials and regenerated cellulose maintain consistent demand in premium packaging and specialty film applications, where transparency and renewable content are important. This varied product mix indicates that the Europe biopolymers market is evolving beyond reliance on a single polymer, with growth increasingly driven by application-specific material selection based on performance, compostability needs, regulatory compliance, and lifecycle sustainability goals rather than solely on cost.
Packaging Dominates While Automotive and Healthcare Drive High-Value Demand Across the Europe Biopolymers Market
The cross-segment analysis reveals that the European biopolymers market is predominantly centered around countries with advanced manufacturing capabilities, robust circular economy policies, and high-value downstream industries. Germany stands out as the largest demand center in the region, fueled by its extensive packaging, automotive, healthcare, and engineering plastics sectors. The German packaging industry generates more than EUR 30 billion in annual revenues and positions the country as Europe’s leading automotive producer, which presents significant opportunities for bio-based engineering polymers in lightweight interior components and sustainable packaging solutions.
In addition, France and Italy show strong demand across the packaging, food and beverage, and agriculture sectors. This is supported by the widespread adoption of compostable films, food packaging, and agricultural mulch applications. France, with one of the largest agricultural sectors in Europe, utilizes over 27 million hectares of agricultural land, facilitating the growing use of biodegradable agricultural inputs. Spain and Poland also demonstrate substantial engagement in agricultural applications, propelled by extensive cultivation areas and a rising demand for sustainable farming materials.
The healthcare and life sciences sectors, along with advanced manufacturing, spotlight the United Kingdom and the Netherlands, where high-performance bio-based polymers are increasingly used in medical devices, laboratory consumables, and pharmaceutical packaging. Additionally, the Netherlands serves as a major logistics and polymer distribution hub, with the Port of Rotterdam enabling efficient movement of bio-based raw materials throughout Europe.
Belgium’s strong petrochemical cluster supports the integration of bio-based polymers into existing chemical value chains, while Sweden, Denmark, and Norway exhibit above-average adoption rates in automotive, construction, and healthcare sectors, driven by ambitious carbon neutrality goals and the prevalent use of sustainable materials.
Overall, packaging remains the dominant end-use industry, constituting over 40% of total bioplastics consumption in Europe, largely influenced by regulatory pressures under the Packaging and Packaging Waste Regulation (PPWR) and increasing commitments from retailers towards renewable packaging options. Together, healthcare, consumer goods, and food and beverage sectors represent the next largest areas of application. Meanwhile, niche segments like electronics and 3D printing are experiencing rapid growth, driven by material innovation. This diverse landscape highlights that the European biopolymers market is evolving through application-specific demand, rather than depending on a singular end-use sector, thereby creating multiple growth opportunities across manufacturing, agriculture, healthcare, consumer products, and industrial domains.
Competitive Analysis
Key companies studied within the Europe biopolymers market are: BASF SE, Novamont S.p.A., Arkema, FKuR Kunststoff GmbH, Evonik Industries AG, Covestro AG, Others.
Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) for the European biopolymers market emphasizes the importance of production capability and innovation over traditional financial metrics. This focus arises from the fact that competitive differentiation in the industry is largely influenced by manufacturing scale, feedstock security, and regulatory compliance.
In the framework, production capacity is given the highest weighting at 20%. This reflects the ongoing investments in facilities for PLA, PBAT, and specialty polymers within Europe, aimed at reducing reliance on imported materials while enhancing regional supply resilience. Product portfolio diversity also holds significant importance at 15%, as customers increasingly seek application-specific materials ranging from compostable flexible packaging to engineering-grade bio-based polymers.
Feedstock integration is recognized with a 12% weighting, marking it as a strategic differentiator. Manufacturers who utilize agricultural residues, waste biomass, or secure long-term renewable feedstock contracts are better equipped to manage raw material price volatility. Innovation, carrying another 12% weighting, underscores the industry's commitment to enhancing heat resistance, barrier properties, and mechanical performance, enabling expansion into sectors beyond traditional packaging, such as automotive, healthcare, and electronics.
Regulatory compliance contributes 10%, acknowledging that certifications for compostability, food-contact safety, and sustainability are critical for gaining commercial acceptance in the European biopolymers market. Factors like geographic reach, customer partnerships, application diversification, and operational efficiency receive lower but still meaningful weightings, as they influence the ability to scale operations across various European industries while maintaining profitability.
Overall, the EICAF framework offers a comprehensive methodology for benchmarking manufacturers based on their long-term competitiveness, technological leadership, and commercial execution, rather than relying solely on market share or revenue.

