U.S. Power Transformer Market: Meeting the Rising Power Demand from AI Data Centers
Analysis by Power Rating (Up to 100 MVA, 101–300 MVA, 301–600 MVA, Above 600 MVA), Voltage Rating, Phase Configuration, Application and End User 2027-2033


Analysis by Power Rating (Up to 100 MVA, 101–300 MVA, 301–600 MVA, Above 600 MVA), Voltage Rating, Phase Configuration, Application and End User 2027-2033
U.S. Power Transformer Market recorded a sales volume of 2,500 units in 2025 and is estimated to reach a volume of 3,275 units by 2033 with a CAGR of 3.7% during the forecast period.
Growing installations of utility-scale solar, wind, and battery energy storage systems require generator step-up (GSU) and transmission transformers to integrate renewable power into the grid.
The rapid expansion of renewable energy infrastructure is becoming a significant growth driver for the U.S. power transformer market. Utility-scale solar, wind, and battery energy storage projects require high-capacity generator step-up (GSU) and transmission transformers to efficiently deliver electricity to the national grid. The U.S. Energy Information Administration (EIA) projects that utility-scale solar and battery storage will account for nearly 81% of all new utility-scale generating capacity additions in 2025, with plans for approximately 32.5 GW of solar and 18.2 GW of battery energy storage. Additionally, wind energy is expected to contribute another 7.7 GW of new capacity, further boosting the demand for high-voltage transmission infrastructure.
Each large-scale renewable project necessitates GSU transformers to elevate generator voltage from typical levels of 13–34.5 kV to transmission levels exceeding 230 kV, while additional power transformers are installed at substations to ensure reliable power transfer across regional transmission networks. The U.S. Department of Energy estimates that national electricity transmission systems must expand by 60% by 2030 and potentially triple by 2050 to accommodate the increasing generation from renewables and meet decarbonization goals.
This unprecedented expansion of the grid presents sustained procurement opportunities for extra-high-voltage power transformers used in interconnection substations and long-distance transmission corridors. Investments in transmission assets are accelerating due to the rising deployment of offshore wind projects along the Atlantic coast, large solar farms in Texas and the Southwest, and grid-scale battery storage installations in California, Arizona, and Nevada. As utilities modernize substations and enhance grid resilience, the demand for digitally monitored, high-efficiency power transformers is also on the rise.
As a result, the integration of renewable energy is poised to be a long-term catalyst for the U.S. power transformer market, with transformer manufacturers likely to benefit from increasing utility capital expenditures, transmission expansion projects, and federal investments aimed at supporting clean energy infrastructure and grid modernization initiatives.
Limited domestic availability of key materials such as GOES and specialized transformer components increases exposure to international trade restrictions, tariffs, and supply shortages.
The U.S. power transformer market is encountering notable supply-side challenges stemming from a limited domestic supply of critical raw materials and specialized transformer components. Grain-oriented electrical steel (GOES), which is vital for transformer cores to reduce energy losses and enhance efficiency, is produced by only a few manufacturers worldwide. As a result, the U.S. relies heavily on imports to meet a significant portion of its needs. Additionally, essential components like high-voltage bushings, on-load tap changers (OLTCs), insulation systems, and transformer-grade copper conductors are acquired through intricate international supply chains.
The U.S. Department of Energy reports that lead times for large power transformers have lengthened from about 12–18 months before 2020 to 24–36 months now, primarily due to shortages of GOES, electrical components, and manufacturing capabilities. Factors such as rising geopolitical tensions, tariffs on imported steel and electrical equipment, shipping disruptions, and fluctuations in freight costs have further elevated procurement risks for utilities and transformer manufacturers.
According to the International Energy Agency (IEA), global electricity grid investment needs to surpass USD 600 billion annually by 2030, increasing the competition for transformer-grade materials and critical components. The rapid growth of renewable energy projects, AI-driven data centers, and transmission infrastructure in North America has tightened the supply-demand balance for GOES and other specialized materials. Consequently, utilities are facing delays in procurement, leading many transmission projects to postpone their commissioning schedules and driving up project costs.
While initiatives under the Infrastructure Investment and Jobs Act (IIJA) and domestic manufacturing incentives are anticipated to bolster the U.S. industrial base in the long run, expanding production of GOES and transformer manufacturing capacity will require significant capital investment and several years to become fully operational. Therefore, the ongoing reliance on imported materials and components remains a major challenge for the U.S. power transformer market, leaving manufacturers and utilities vulnerable to trade restrictions, tariff fluctuations, supply shortages, and extended delivery timelines, all of which could hinder market growth in the foreseeable future.
The unprecedented growth of artificial intelligence (AI), hyperscale cloud computing, and colocation facilities is becoming a significant demand driver for the U.S. power transformer market. Data centers utilizing AI technology consume substantially more electricity than traditional facilities due to their high-density GPU clusters and advanced liquid-cooling systems. According to the International Energy Agency (IEA), global electricity consumption from data centers is expected to surpass 1,000 TWh by 2030, more than double the levels anticipated in 2024, with the United States leading the way in AI infrastructure deployment. Goldman Sachs projects that U.S. data center electricity demand could rise by approximately 160% between 2023 and 2030, while the Electric Power Research Institute (EPRI) estimates that data centers may account for up to 9% of total U.S. electricity consumption by 2030, up from around 4% in 2023.
Typically, each hyperscale campus requires 100–500 MW of power capacity, and next-generation AI campuses often exceed 1 GW. This trend necessitates the construction of dedicated substations equipped with high-capacity power transformers operating at voltage levels of 230 kV, 345 kV, and above. Major technology firms such as Microsoft, Amazon Web Services, Google, Meta, and Oracle are actively expanding their AI infrastructure across states like Virginia, Texas, Arizona, Ohio, and Georgia, resulting in considerable investments in transmission upgrades and substation development.
In response, utilities are expediting the procurement of large generator step-up and transmission transformers to manage higher electrical loads while ensuring grid reliability. The increasing concentration of hyperscale facilities is also driving the deployment of digitally monitored transformers, which offer real-time asset diagnostics, predictive maintenance, and improved thermal management to support continuous operations. As AI adoption accelerates across various industries, transformer manufacturers are experiencing stronger order pipelines, longer production backlogs, and higher capacity utilization. Therefore, the rapid expansion of AI-powered data centers is anticipated to remain a long-term structural growth driver for the U.S. power transformer market, fostering ongoing demand for high-voltage transformer installations, grid modernization initiatives, and utility capital investments throughout the forecast period.
The choice between replacing existing transformers and installing new units is emerging as a key consideration in shaping investment strategies within the U.S. power transformer market. Utilities are increasingly depending on comprehensive asset management programs to assess various factors such as transformer age, insulation condition, loading circumstances, maintenance history, dissolved gas analysis (DGA), and potential failure risks before deciding whether refurbishment or full replacement offers the best long-term value.
According to the U.S. Department of Energy, the typical lifespan of a large power transformer is between 40 and 50 years. Many of these assets, installed during the grid expansion of the 1970s and 1980s, are nearing the end of their operational life. However, decisions around replacement are influenced by more than just age. Utilities also evaluate increased electricity demand, higher fault current levels, requirements for renewable energy integration, and stricter efficiency standards to determine if existing transformers can meet future network needs.
Refurbishment can extend the life of transformers by 10–20 years at a significantly lower capital cost, making it an appealing option for those with structurally sound cores and windings. On the other hand, replacement becomes the preferred choice when transformers show signs of insulation degradation, repeated operational failures, insufficient capacity, or designs that no longer support modern digital monitoring technologies.
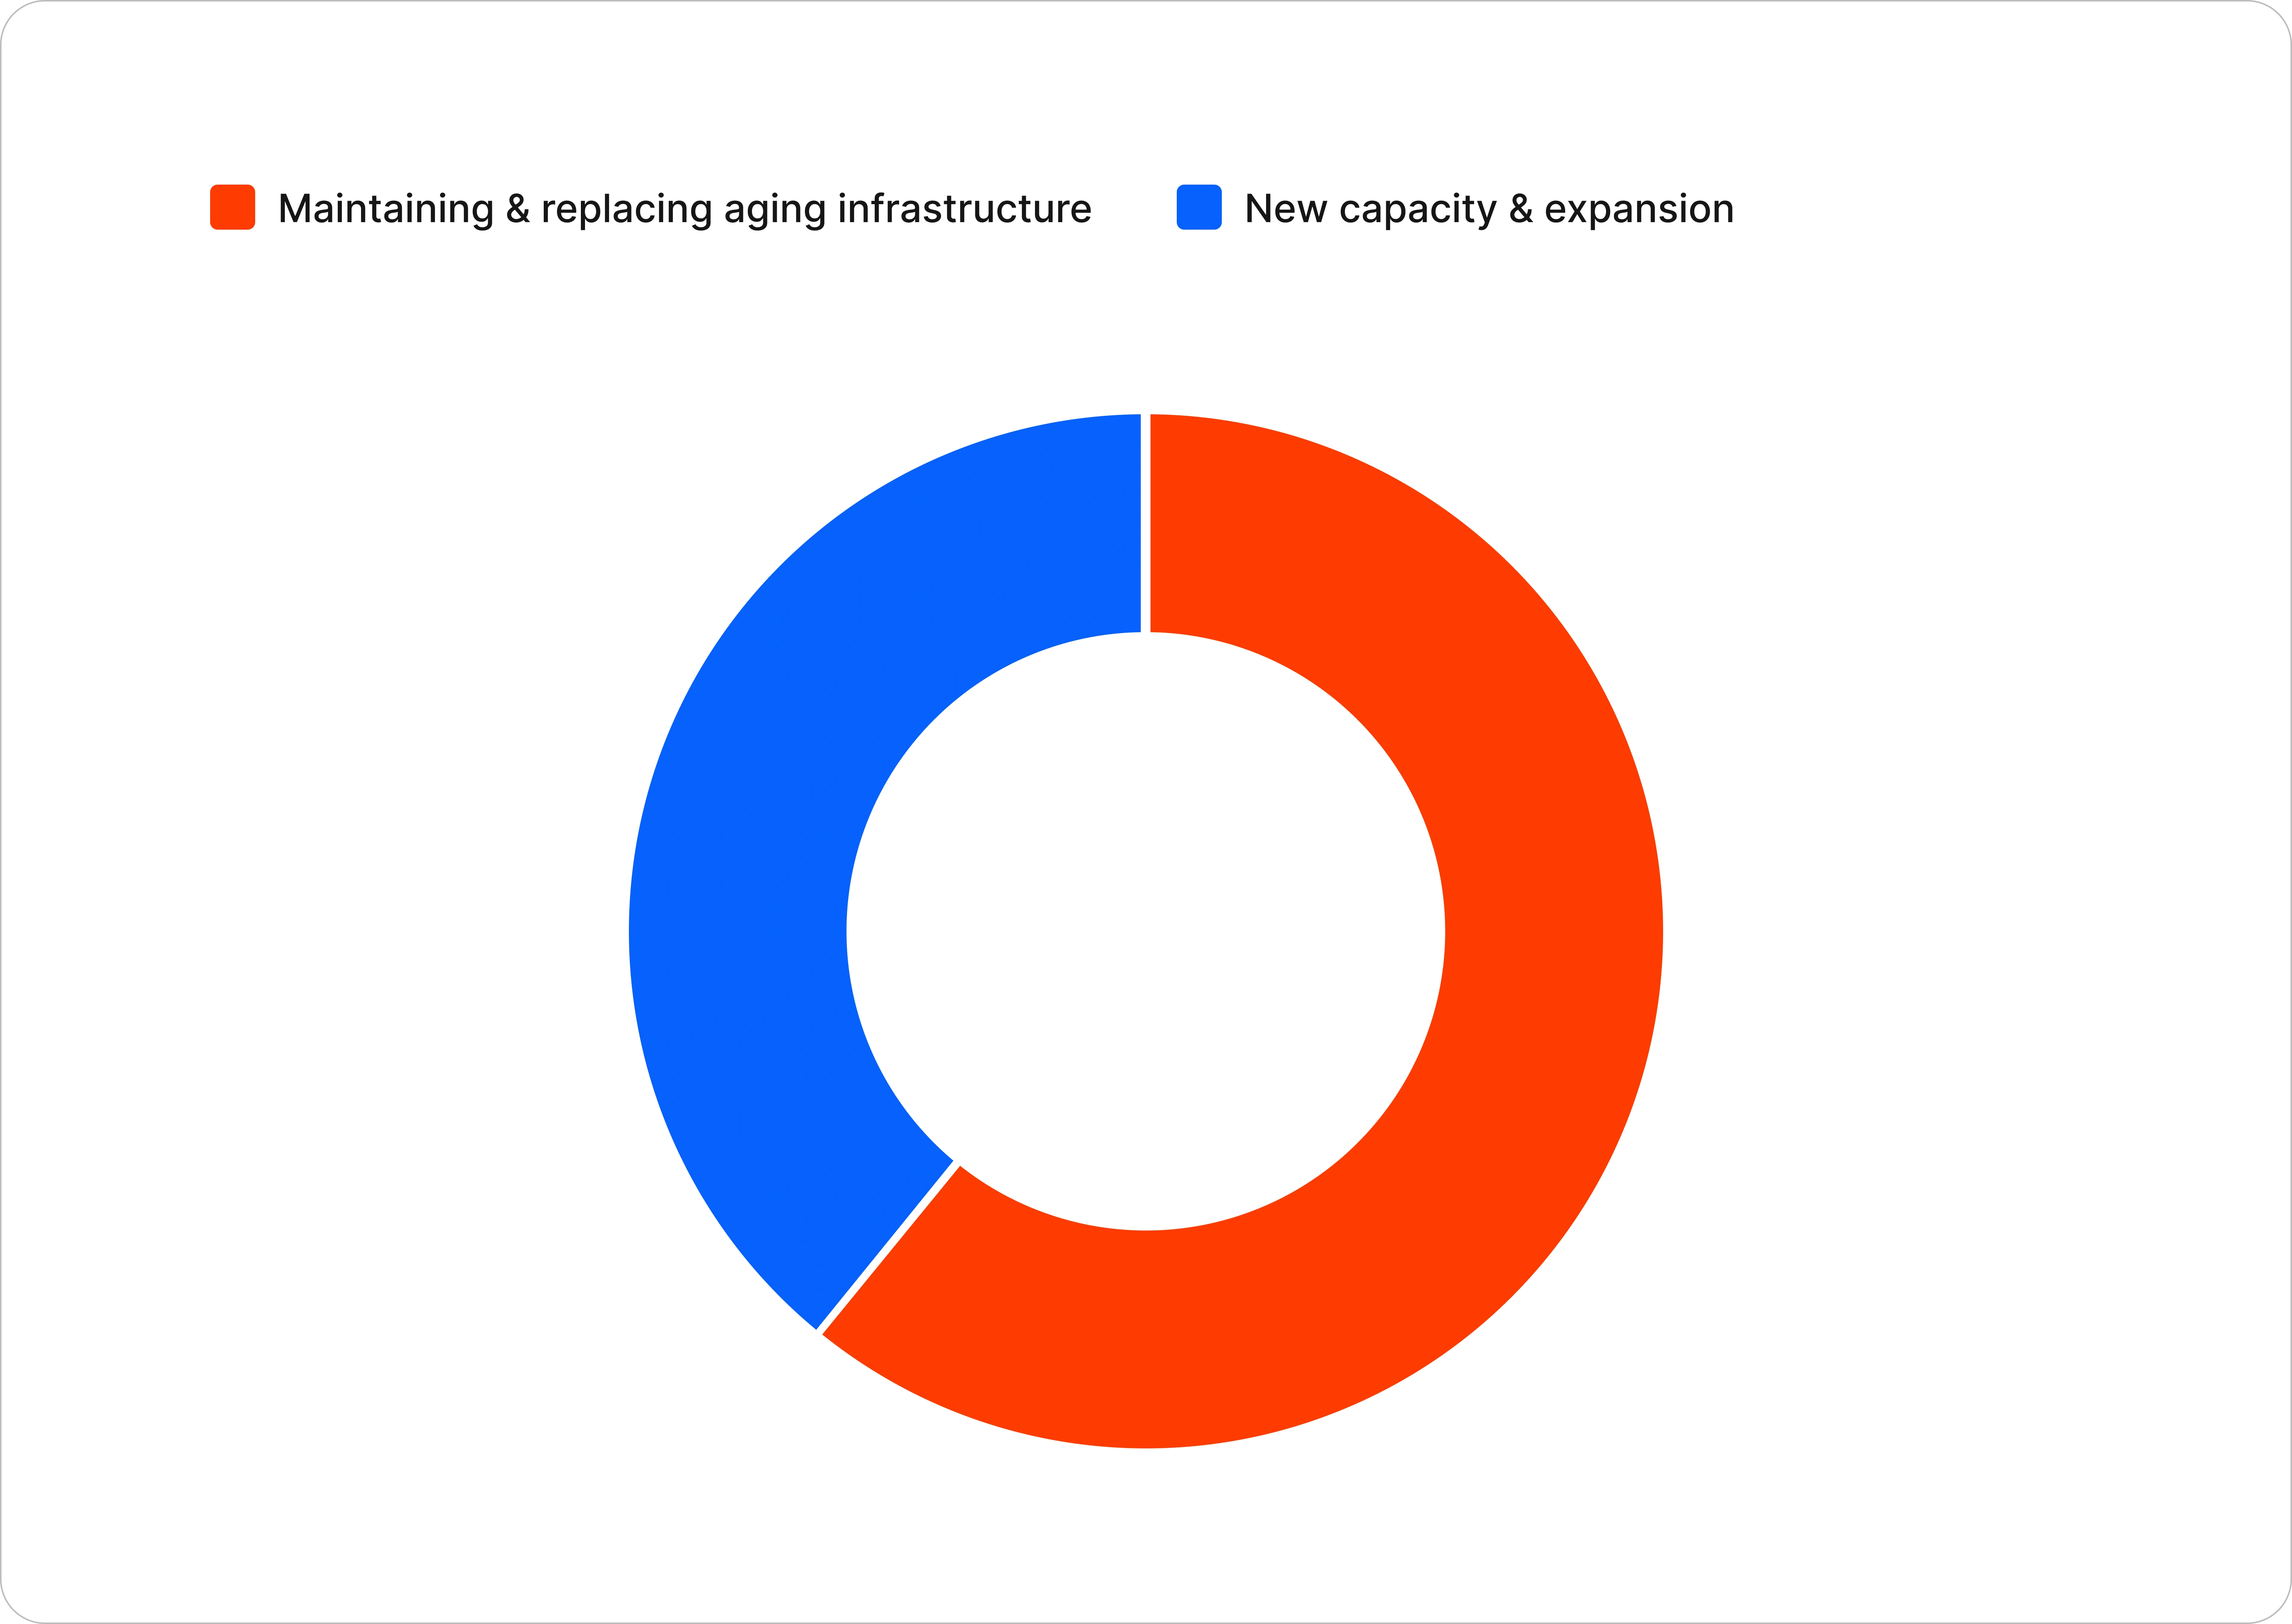
Industry estimates suggest that utilities allocate approximately 60–70% of their annual expenditure on transmission assets to maintaining and replacing aging infrastructure, highlighting the increasing significance of lifecycle optimization. The rise of condition-based maintenance, online monitoring systems, and predictive analytics allows operators to postpone unnecessary replacements while focusing investments on high-risk assets.
New transformer installations are primarily linked to transmission expansion, substation upgrades, industrial electrification, and large commercial projects, rather than routine asset renewals. As utilities seek to optimize capital returns while ensuring grid reliability, their decisions regarding replacement and refurbishment are becoming more data-driven. This process balances operational risk, lifecycle costs, regulatory compliance, and anticipated load growth, influencing procurement trends, service revenues, and capital distribution across the U.S. power transformer market in the years ahead.
The ongoing shift towards a cleaner electricity mix is notably enhancing the readiness for renewable integration within the U.S. power transformer market. Utilities are proactively gearing up their transmission infrastructure to effectively handle the increasingly variable power generation from wind, solar, and energy storage sources. Unlike traditional thermal generation, renewable energy projects are frequently situated far from demand centers. This necessitates the development of new high-voltage substations, interconnection facilities, and extensive transmission corridors that are equipped with advanced power transformers capable of managing bidirectional power flows and accommodating fluctuating grid conditions.
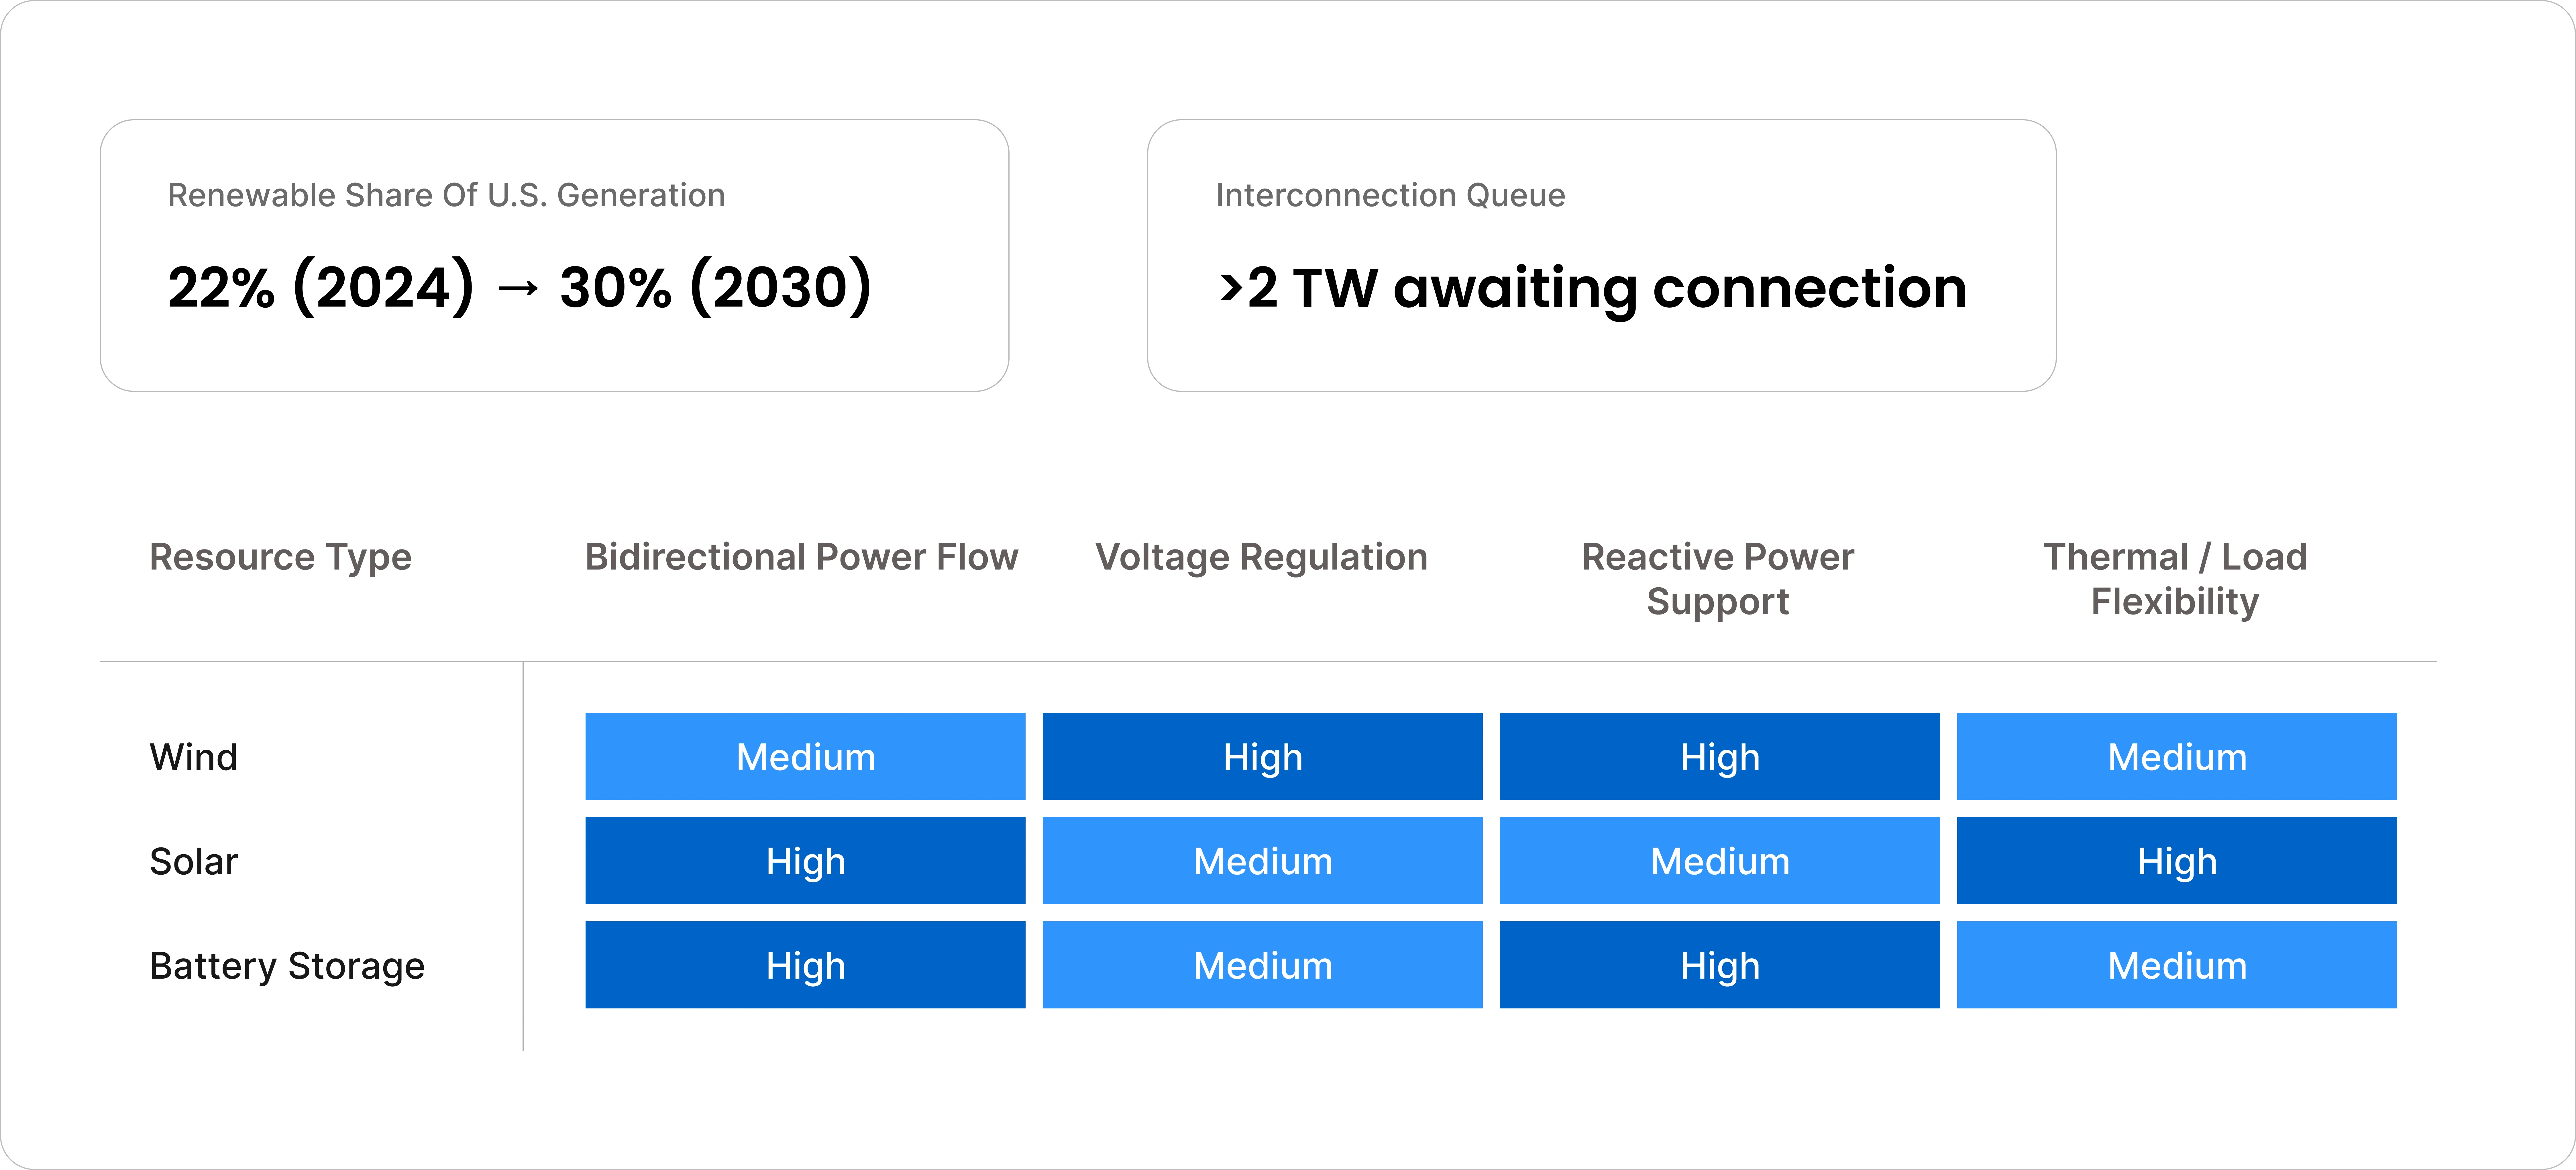
According to the U.S. Energy Information Administration (EIA), renewable energy is projected to contribute roughly 30% to total U.S. electricity generation by 2030, an increase from approximately 22% in 2024, highlighting the rapid deployment of utility-scale clean energy projects. Concurrently, the U.S. Department of Energy estimates that achieving national decarbonization goals will require the construction of tens of thousands of miles of new transmission lines over the upcoming decades, effectively linking renewable generation to population centers.
This transition is prompting utilities to upgrade their substations with higher-capacity transformers that offer improved voltage regulation, enhanced thermal performance, and increased operational flexibility. Furthermore, the demands of renewable integration are leading to the need for transformers that can support dynamic load variations, reactive power compensation, and maintain grid stability amidst intermittent generation conditions.
The Federal Energy Regulatory Commission (FERC) has also implemented transmission planning reforms aimed at speeding up long-term grid expansion, encouraging utilities to make proactive investments in infrastructure that can support future renewable capacity instead of relying solely on incremental upgrades. Regional transmission organizations (RTOs) and independent system operators (ISOs) are reporting significant interconnection backlogs, with over 2 terawatts (TW) of proposed generation and storage capacity awaiting grid connection in the U.S. This situation underscores the pressing need for transformer upgrades and new installations.
As a result, utilities are increasingly focusing on resilient, high-efficiency transformer technologies that not only enhance grid reliability but also facilitate greater renewable energy penetration.
This structural transformation is establishing renewable integration readiness as a key growth aspect for the U.S. power transformer market, paving the way for ongoing investments in advanced transmission infrastructure, digital substations, and next-generation power transformer technologies throughout the projected period.
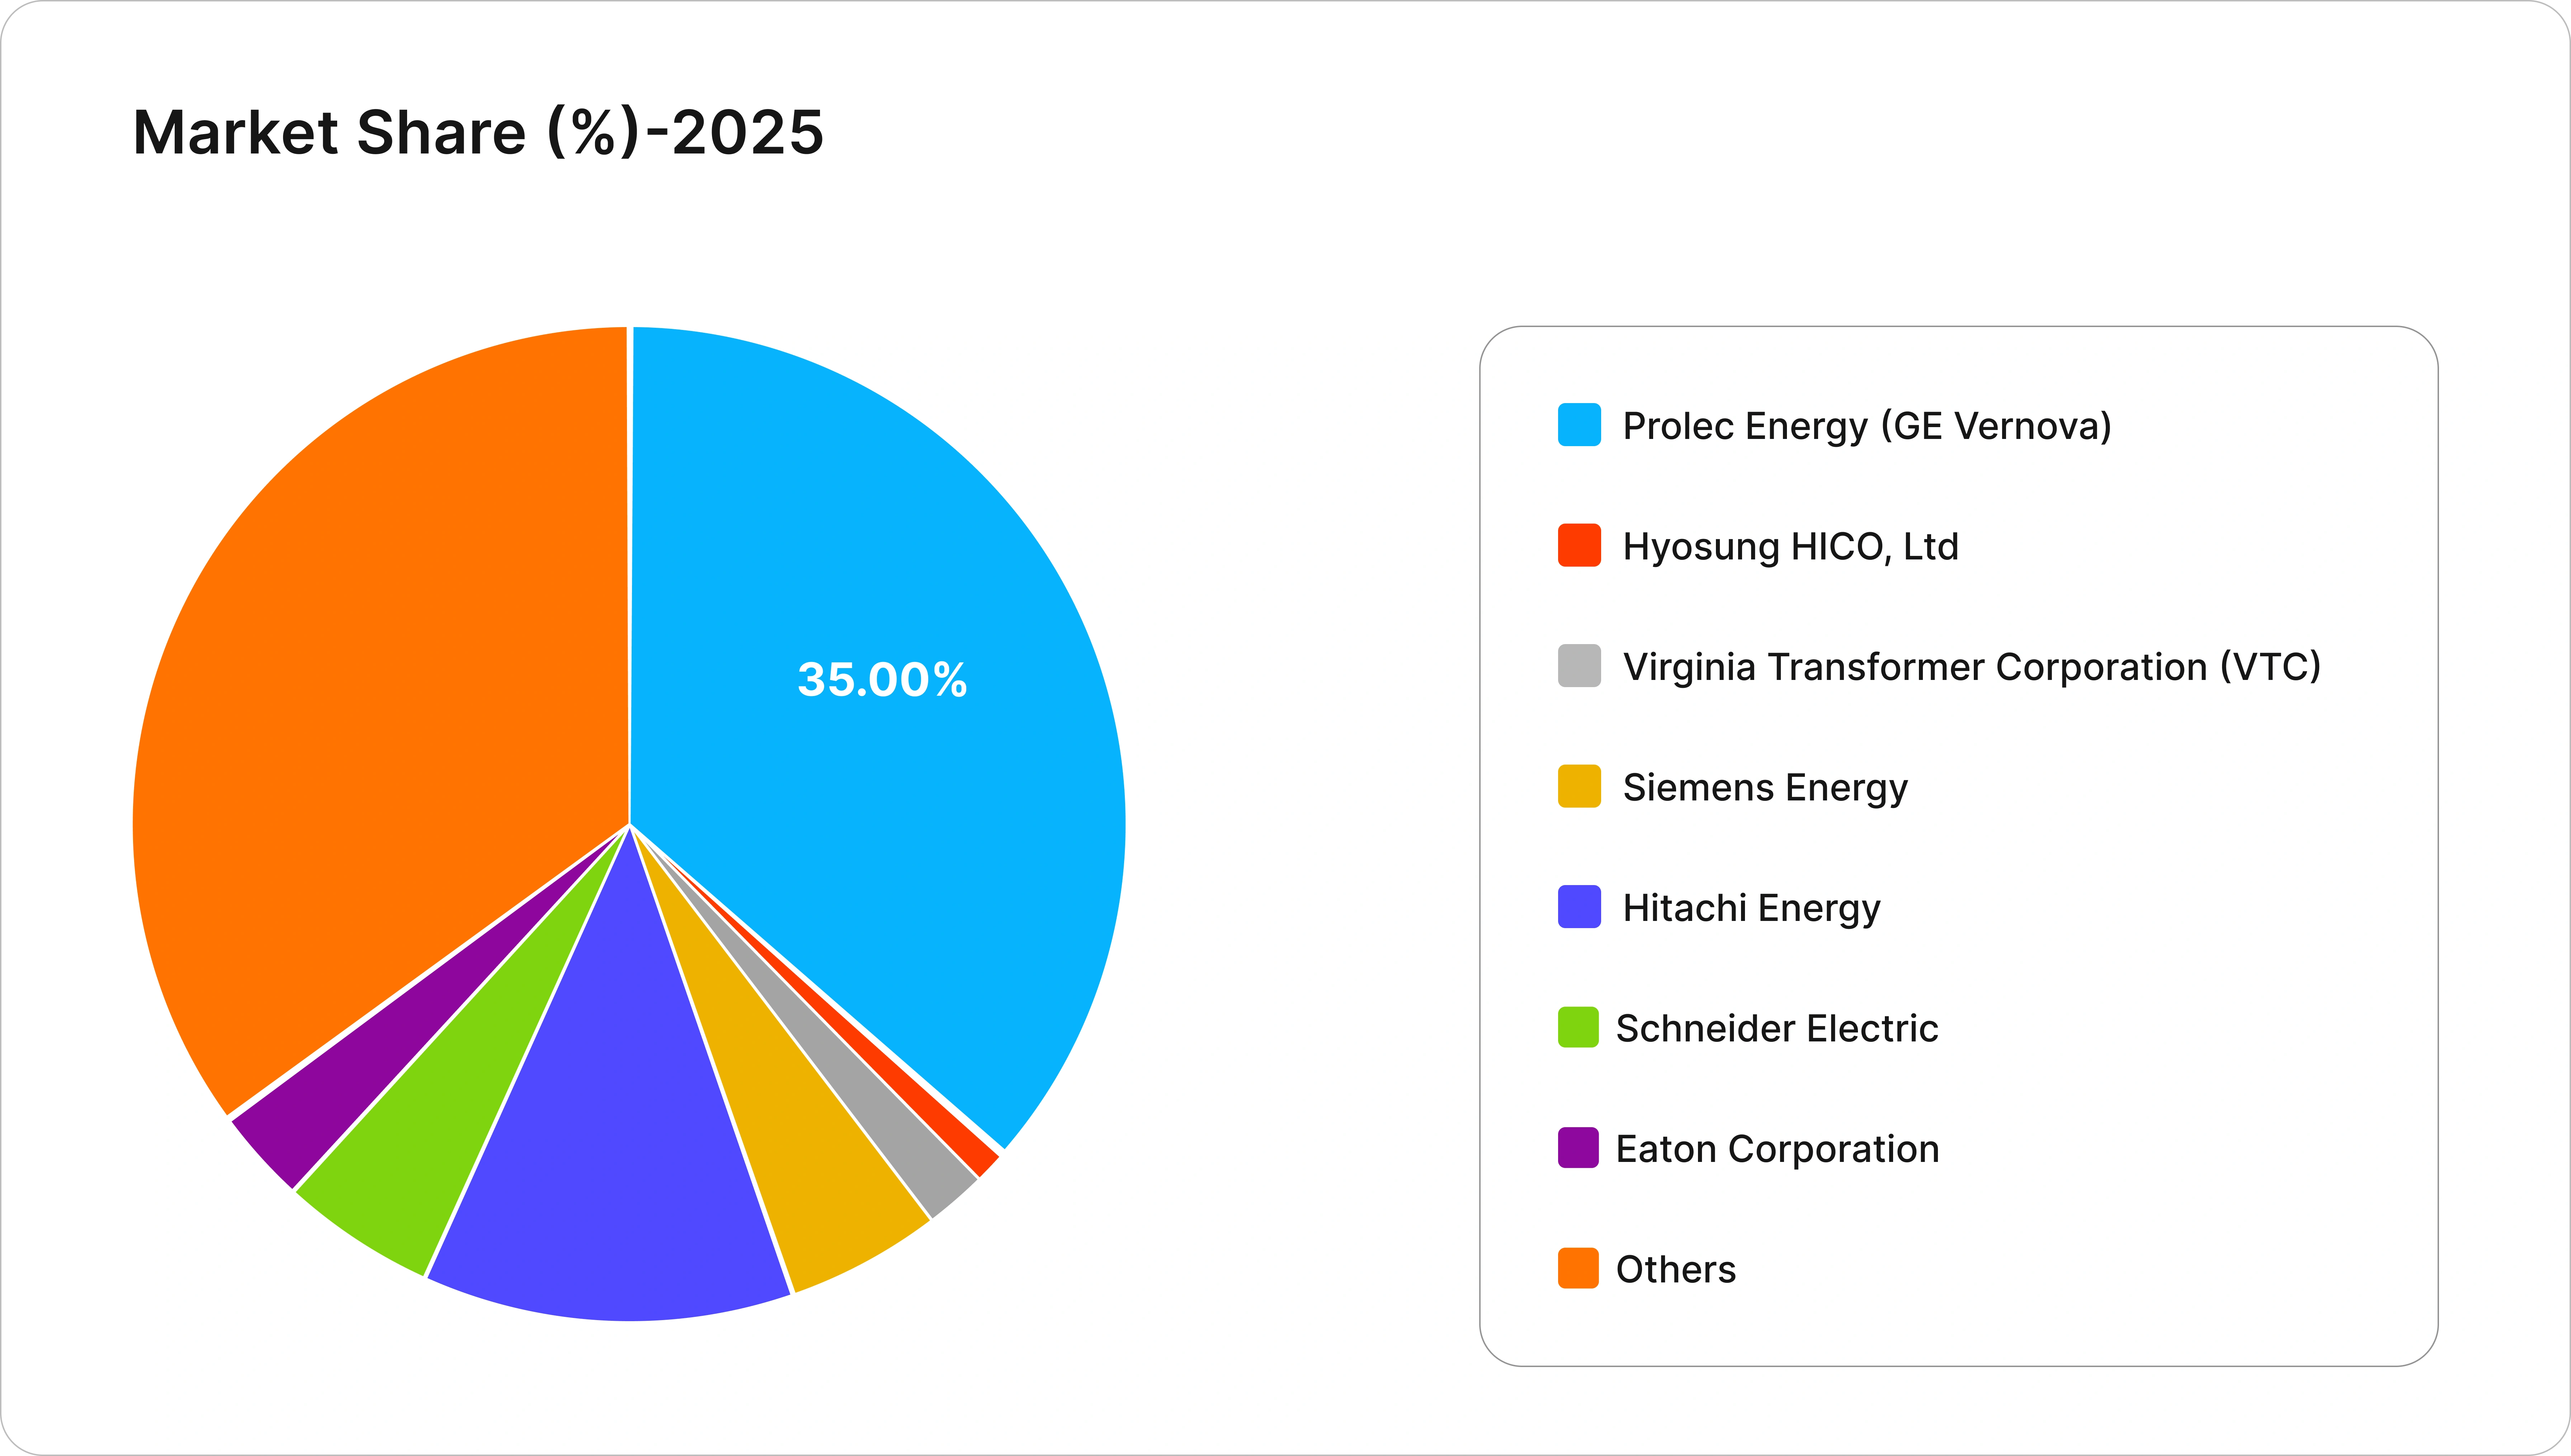
Key players analyzed within the U.S. power transformer market are: Hitachi Energy, GE Vernova (now includes Prolec GE as a wholly owned subsidiary), Siemens Energy, Virginia Transformer, Hyosung Heavy Industries, Mitsubishi Electric, WEG, CG Power and Industrial Solutions, SGB-SMIT Group.
The Epignosis Insights Competitive Assessment Framework (EICAF) serves as a tool for evaluating the competitive positioning of manufacturers in the U.S. power transformer market. It assesses their capabilities in key areas such as technology, manufacturing, commercial strength, and long-term strategic readiness. Unlike traditional methods that focus solely on market share, EICAF provides a comprehensive evaluation of a company’s ability to maintain a competitive advantage through a weighted analysis of critical business factors.
Manufacturers are benchmarks on various parameters, including production capacity, range of product offerings, technological innovation, and capabilities in grid modernization. Additional factors like financial health, customer relationships, after-sales service, domestic manufacturing presence, and supply chain resilience are also considered. Qualitative aspects, such as digital transformer capabilities, involvement in renewable energy projects, utility approvals, and investments in research and development, are integrated into the assessment.
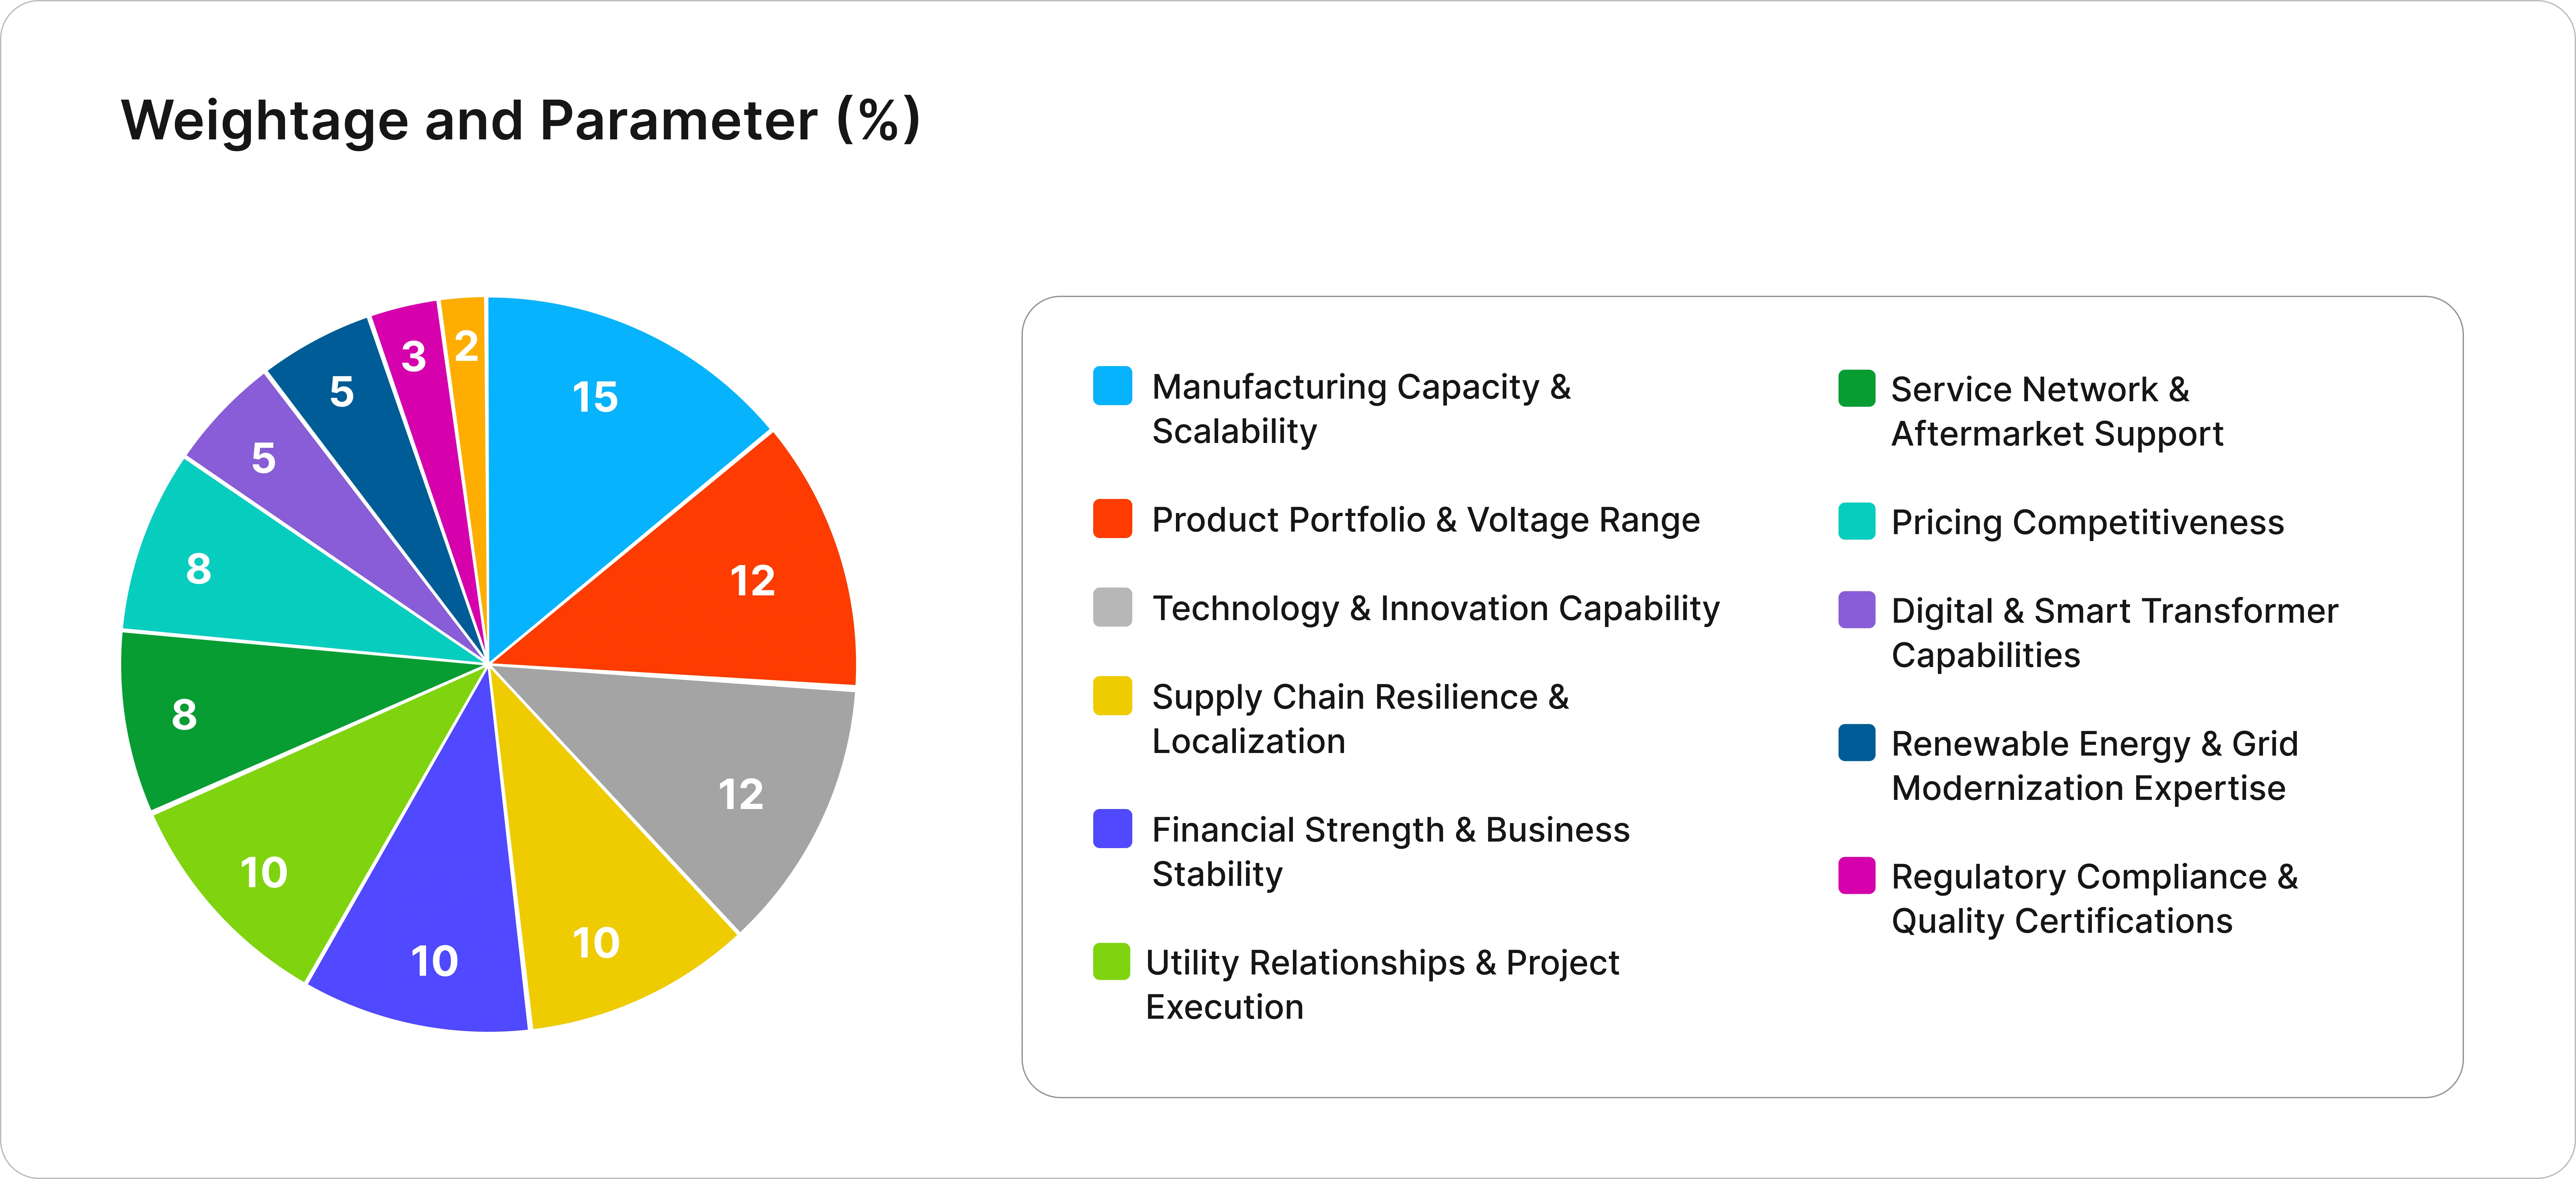
Typically, companies with diversified manufacturing facilities, solid utility partnerships, shorter delivery times, and cutting-edge monitoring technologies score higher in competitiveness. The framework also takes into account strategic factors like engagement in transmission expansion projects, adherence to U.S. regulatory standards, localization strategies, and the ability to cater to high-growth applications, including AI data centers, renewable energy integration, and HVDC infrastructure.
EICAF allows stakeholders to compare top original equipment manufacturers (OEMs) beyond mere revenue metrics by uncovering strengths, weaknesses, opportunities, and execution capabilities throughout the value chain. For investors, utilities, EPC contractors, and procurement teams, this framework provides a standardized methodology to evaluate vendor competitiveness, assess procurement risks, and pinpoint potential market leaders. As infrastructure investments ramp up, EICAF serves as a practical decision-support tool for assessing competitive intensity and strategic positioning in the U.S. power transformer market.