Japan Electric Motor Market: Lucrative Investment Opportunities Through 2033
Analysis by Motor Type (AC Motors, DC Motors, Universal Motors, Stepper Motors, Servo Motors, Synchronous Motors, Switched Reluctance Motors), Voltage and Application


Analysis by Motor Type (AC Motors, DC Motors, Universal Motors, Stepper Motors, Servo Motors, Synchronous Motors, Switched Reluctance Motors), Voltage and Application
Japan Electric Motor Market recorded a sale of 192 million units in 2025 and is estimated to reach a volume of 372 million units by 2033 with a CAGR of 11.7% during the forecast period.
Growing Integration of Motors With Industrial IoT and Predictive Maintenance Systems
The integration of electric motors with Industrial IoT is creating a more technology intensive demand environment in the Japan electric motor market, particularly across factories using robotics, automated production lines and precision equipment. Japan had approximately 450,500 industrial robots in operational use in 2024, while 44,500 new industrial robots were installed during the year, highlighting the scale of automated equipment that depends heavily on motor driven motion systems.
This installed base creates a substantial opportunity for connected motors equipped with vibration, temperature, current and load monitoring capabilities. Instead of operating motors until failure, Japanese manufacturers can use real time sensor data to identify bearing deterioration, abnormal vibration, overheating and load changes before equipment downtime occurs. This is particularly relevant for semiconductor, electronics, automotive and precision manufacturing facilities where an unexpected motor failure can interrupt highly synchronized production processes. Japan's manufacturing policy is also placing greater emphasis on AI and digital technology adoption as part of longer term industrial competitiveness and investment.
The aging of Japan’s industrial equipment base is creating a distinctive replacement opportunity and challenge for the Japan electric motor market. Japanese manufacturers have historically operated equipment for long periods, meaning many motors remain embedded within production lines that were designed before the current generation of high efficiency, variable speed and digitally connected motor systems.
METI has previously highlighted the scale of this issue: a survey of manufacturing equipment found that 50% to nearly 80% of selected equipment categories had been in operation for more than 15 years. This matters for electric motor suppliers because replacing an individual motor is often not a simple component purchase. Motors are integrated with pumps, compressors, conveyors, machine tools, robotics and factory control systems, so upgrading them can require changes to drives, control systems, mounting arrangements and operating parameters. METI's recent assessment also notes that Japan has historically emphasized replacement investment while lagging in the scale and speed of investment in manufacturing infrastructure, increasing the urgency of modernization and smart manufacturing adoption.
Consequently, the opportunity is shifting from straightforward motor replacement toward system level modernization, particularly where older motors have high electricity consumption, limited controllability or insufficient compatibility with predictive maintenance platforms. However, manufacturers face a difficult investment decision because replacing a functioning motor creates an upfront capital expense even when the existing equipment continues to operate. This creates demand for retrofit solutions, efficiency based payback analysis and motors designed for compatibility with existing machinery. The replacement cycle is therefore likely to remain highly application specific rather than uniform across Japan.
In the Japan electric motor market, purchasing decisions are increasingly evaluated on total operating economics rather than the initial motor price alone. This is particularly relevant for industrial buyers, where motors operate for thousands of hours and electricity expenditure can materially exceed the original equipment purchase cost. Japan's industrial sector accounted for approximately 37% of the country's total electricity consumption in 2023, making motor efficiency an important consideration for manufacturers managing operating expenses.
Performance ranks alongside efficiency because Japanese automotive, robotics, semiconductor and precision manufacturing applications require tight speed control, low vibration and consistent torque output. Brand reputation also carries significant weight because motor failure can disrupt interconnected production equipment, making established suppliers attractive where reliability and technical compatibility are critical. Price remains important, particularly for standardized motors and cost sensitive applications, but buyers are more likely to accept a premium when it is supported by measurable energy savings, longer operating life or reduced maintenance requirements. Warranty and after sales service become particularly influential for specialized motors because commissioning, troubleshooting, replacement parts and technical support can affect equipment uptime.
The Japan electric motor market therefore has a strong value based purchasing environment, particularly for industrial applications where downtime and energy consumption can outweigh upfront procurement costs. Buyers increasingly compare motors using lifecycle economics, technical specifications and supplier support rather than selecting solely on purchase price. This creates an advantage for manufacturers able to demonstrate efficiency gains, dependable performance and responsive service. For premium applications such as robotics and precision machinery, performance and reliability can command greater importance, while standardized motors used in less demanding equipment are more exposed to price competition.
Japan maintains a strong position in international electric motor trade, particularly in precision and small motor categories that serve automotive, electronics, industrial equipment and automation applications. In the Japan electric motor market, trade data for motors with output not exceeding 37.5 W shows that Japan exported 73.27 million units valued at US$613.2 million in 2024, while imports reached 265.94 million units valued at US$582.8 million.
The significant difference between export and import volumes reflects Japan's diversified manufacturing structure, where domestic manufacturers maintain competitiveness in higher value or specialized motor products while importing substantial volumes of smaller motors from Asian production hubs. China supplied 125.42 million units, representing approximately 47% of Japan's imports in this category, followed by Vietnam with 95.94 million units. On the export side, the United States and China were major destinations, receiving approximately 17.92 million and 14.77 million units, respectively.
This trade structure indicates that Japan functions simultaneously as a technology intensive manufacturing base and an important market for cost competitive imported motors. For manufacturers, the competitive opportunity therefore differs by product segment. Standardized, high volume motors face greater import competition, whereas precision motors and specialized products can benefit from Japan's established engineering capabilities and relationships with automotive and industrial OEMs. Japan also exported US$1.67 billion of electric motor and generator parts in 2024, demonstrating the country's broader role in the international motor component supply chain.
Replacement and repurchase demand in the Japan electric motor market is increasingly influenced by equipment modernization rather than simple motor failure. Many Japanese factories operate highly integrated production systems, so buyers typically replace motors when an existing unit becomes inefficient, difficult to maintain, incompatible with newer drives or unable to meet the precision requirements of upgraded machinery.
This creates a replacement opportunity across machine tools, pumps, compressors, conveyors, HVAC equipment, robotics and automated production lines. The replacement decision is particularly relevant because Japan's manufacturing equipment base includes a substantial amount of mature machinery. METI has reported that 50% to nearly 80% of selected manufacturing equipment categories had been operating for more than 15 years, indicating a sizeable installed base where motor replacement can occur alongside broader equipment refurbishment.
Rather than following a uniform replacement cycle, Japanese buyers tend to assess motor condition, operating hours, efficiency losses and compatibility with surrounding equipment before authorizing replacement. This favors manufacturers offering retrofit compatible designs, replacement motors with matching mounting dimensions and technical support for integration.
Repurchase behavior is also strengthened when the original supplier provides reliable maintenance and replacement parts, because industrial users often prefer to minimize integration risk. For newer equipment, repeat purchases can arise from expansion of production capacity, additional automated lines and standardization around an existing motor platform. This is particularly valuable for suppliers that secure preferred vendor status with automotive, electronics, robotics and machinery manufacturers. In the Japan electric motor market, therefore, replacement demand is closely linked to the age and modernization requirements of the installed equipment base, while repurchase demand is influenced by supplier reliability, product standardization and expansion investment.
Key companies analyzed within the Japan electric motor market are: Nidec Corporation, Mitsubishi Electric Corporation, Toshiba Industrial Products and Systems Corporation, Hitachi Industrial Equipment Systems Co., Ltd., Fuji Electric Co., Ltd., Meidensha Corporation, Yaskawa Electric Corporation, Mabuchi Motor Co., Ltd., MinebeaMitsumi Inc., Oriental Motor Co., Ltd., Tamagawa Seiki Co., Ltd., Sanyo Denki Co., Ltd., TMEIC Corporation, Others.

The Epignosis Insights Competitive Assessment Framework (EICAF) for the Japan electric motor market evaluates manufacturers according to factors that directly influence their ability to capture demand across Japan's automotive, factory automation, robotics, electronics and industrial equipment sectors. Rather than relying only on company size or reported revenue, the framework emphasizes motor portfolio depth, Japanese industrial customer penetration, high efficiency motor capabilities, precision motion technology, automotive electrification exposure, customization capability, and after sales infrastructure.
This approach is particularly relevant to Japan because motor demand is fragmented across high precision applications and large industrial equipment, requiring different competitive capabilities. Product portfolio strength receives the highest weighting because suppliers with coverage across induction, permanent magnet, servo, brushless DC and specialized motors can address a broader range of Japanese applications. Technology and innovation receive a similarly high weighting because Japanese machinery and automation customers increasingly require compact, efficient and highly controllable motors. Automotive electrification is assessed separately because traction and auxiliary motor requirements create a distinct competitive opportunity. Customer and channel strength measures relationships with Japanese OEMs, machinery manufacturers and system integrators, while service capability evaluates technical support, maintenance and replacement availability.
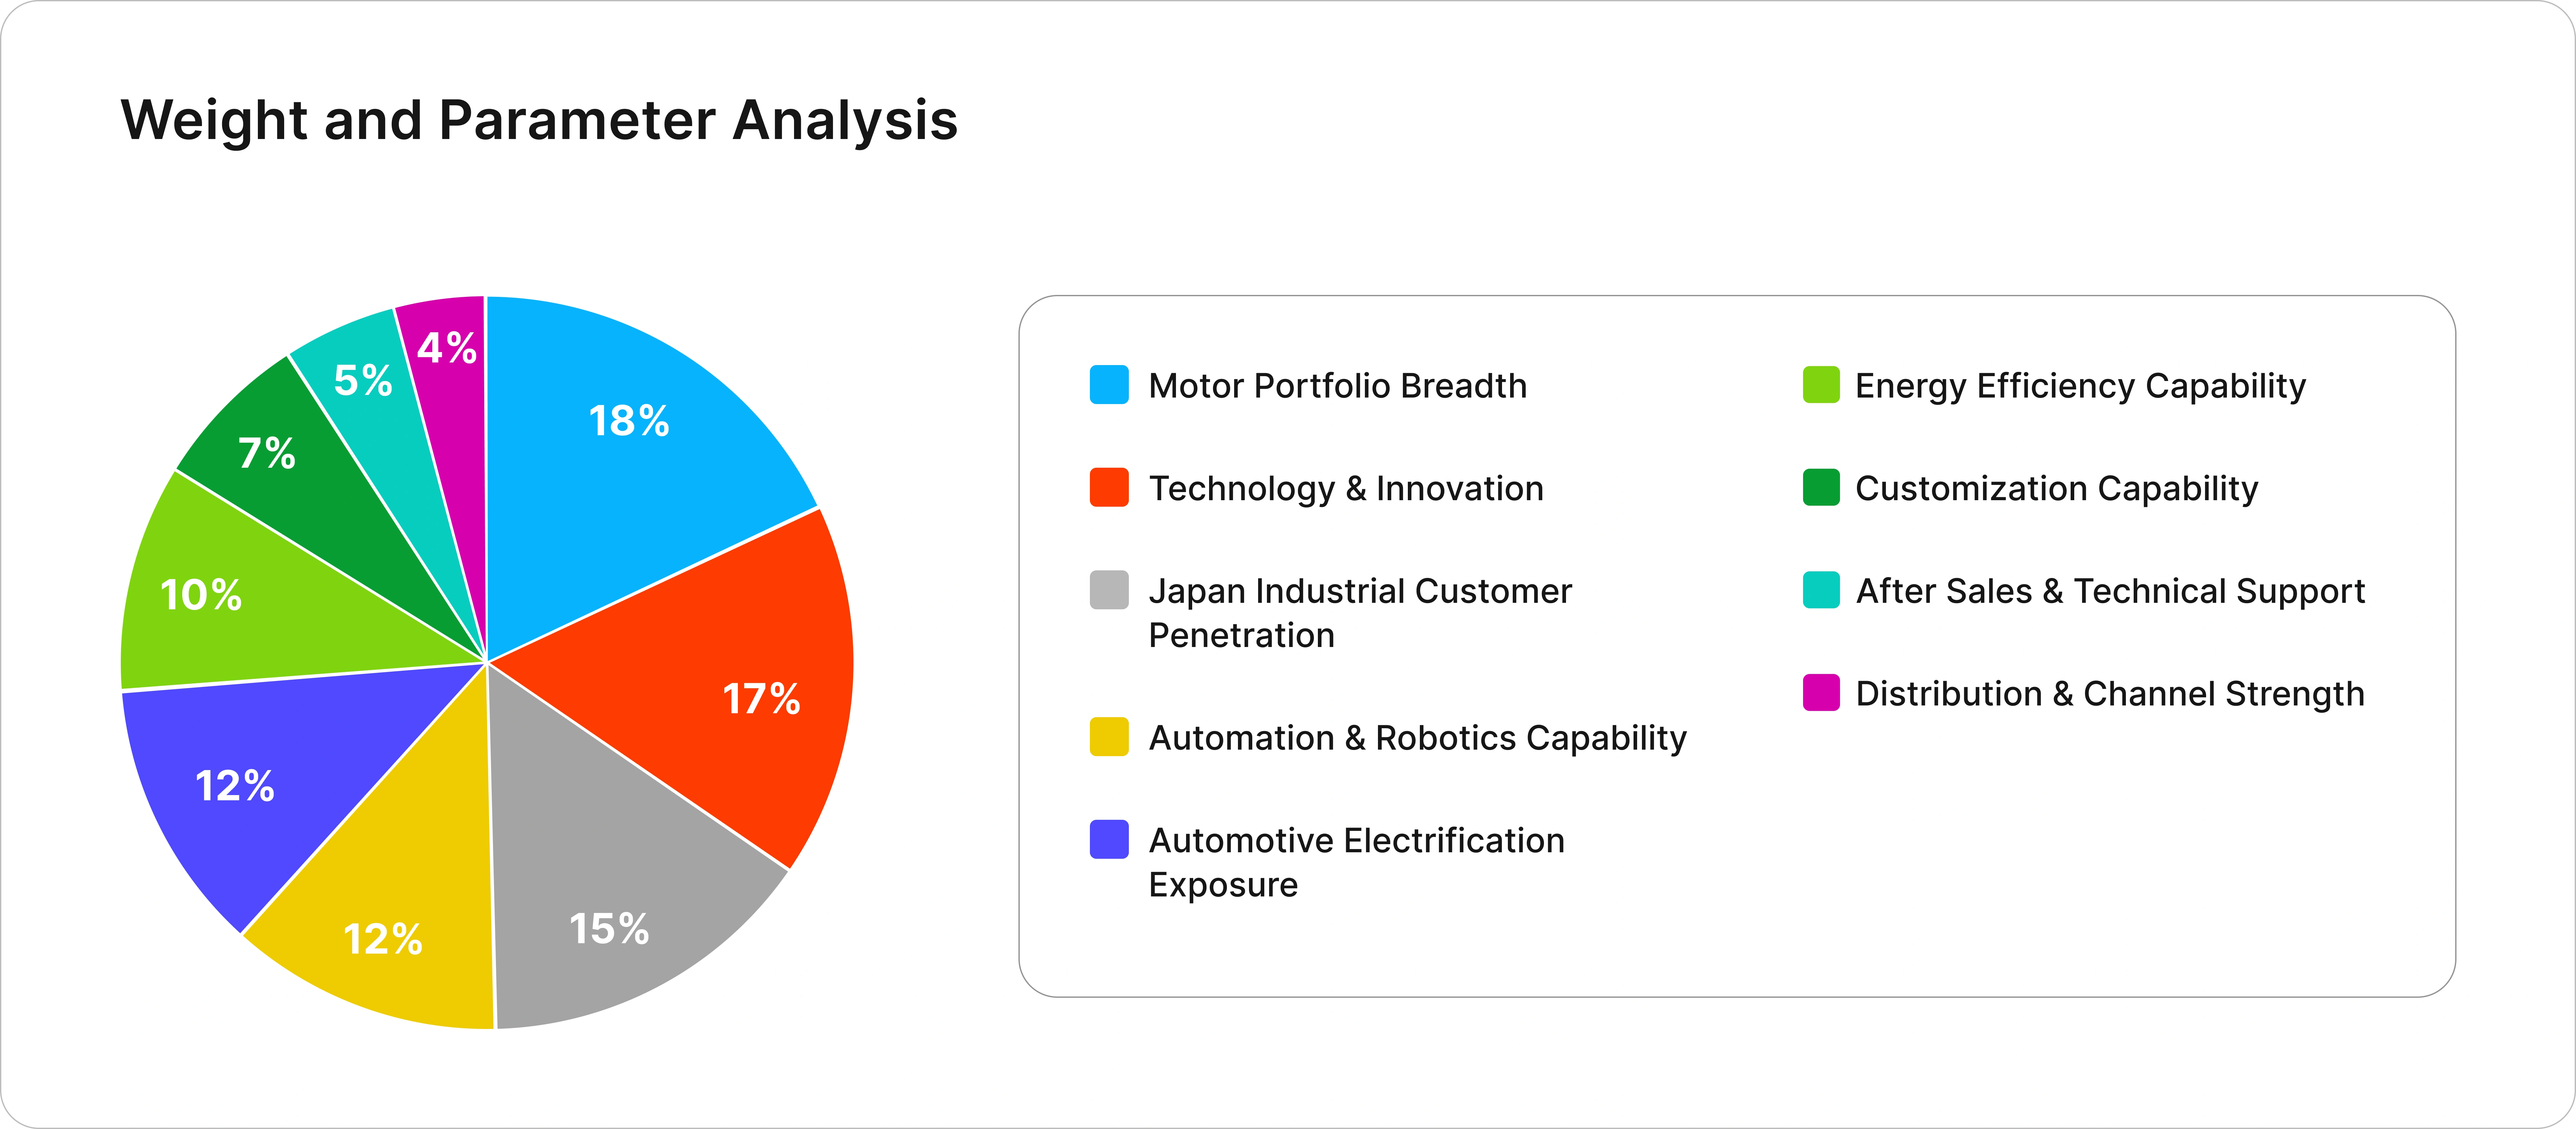
The framework also gives weight to customization because Japanese industrial customers frequently require motors adapted to specific equipment dimensions, torque requirements and control architectures. Using these parameters allows EICAF to distinguish broad based manufacturers such as Nidec and Mitsubishi Electric from specialized players such as Oriental Motor, Sanyo Denki and Tamagawa Seiki. The resulting assessment can be used to construct a company heatmap and identify competitive gaps within the Japan electric motor market.