Key Findings
- Market value: USD 23.6 billion in 2025, projected to reach USD 67.8 billion by 2033.
- Waste processed: 112.5 million tons in 2025, increasing to 211.9 million tons by 2033.
- Volume growth: Waste processing is projected to expand at 8.5% CAGR from 2027 to 2033.
- Average value per ton: Expected to increase from USD 210 in 2025 to USD 320 by 2033.
- Technology focus: Mass burn incineration remains the core large scale solution, while anaerobic digestion, gasification and pyrolysis address more specialized feedstocks.
- Investment opportunity: Locations combining residual waste availability, treatment capacity gaps and district heating demand offer stronger project economics.
- Key revenue lever: Long term waste treatment contracts provide greater revenue visibility alongside electricity and heat sales.
- Major risk: Higher recycling rates could reduce the availability of suitable residual waste for combustion based facilities.
- Strategic opportunity: Advanced ash processing, metal recovery and heat utilization can improve plant economics beyond electricity generation.
- Competitive advantage: High efficiency energy recovery, emission control and proven project execution are becoming critical differentiators in the Europe waste to energy market.
Europe Waste to Energy Market Outlook
The Europe Waste to Energy Market processed approximately 112 million tons of waste in 2025 and is projected to reach around 211 million tons by 2033, expanding at a CAGR of 8.5% during the forecast period.
Europe Waste to Energy Market Dynamics
Carbon Reduction Requirements Are Increasing Demand for High Efficiency WtE Plants
Carbon reduction targets across Europe are shifting investment toward waste to energy facilities that can extract more usable energy from each tonne of residual waste while controlling emissions more effectively. The EU reduced net greenhouse gas emissions by 2.5% in 2024, while the EU ETS had already driven emissions from electricity, heat generation and industrial manufacturing 50% below 2005 levels, increasing pressure on energy intensive infrastructure to improve environmental performance.
This is creating a more selective investment environment for the Europe waste to energy market, where older plants with lower electrical efficiency, limited heat recovery and outdated flue gas treatment can face higher modernization requirements. Energy recovery is becoming particularly valuable in locations connected to district heating networks. European WtE facilities currently supply around 10% of energy delivered through European district heating networks, while individual cities with established networks can obtain more than half of their heating demand from WtE.
The EU's waste incineration framework also covers energy recovery, air emissions, flue gas cleaning and bottom ash treatment, making environmental performance an integrated plant design consideration rather than a standalone compliance issue.
Furthermore, EU waste management currently contributes to an estimated 1% reduction in annual EU greenhouse gas emissions, demonstrating the wider decarbonization value of effective waste treatment. Consequently, operators are increasingly evaluating high efficiency boilers, improved steam cycles, heat recovery systems, advanced flue gas treatment and digital process optimization when upgrading facilities.
The opportunity is strongest for plants capable of combining electricity generation with useful heat delivery because multiple energy outputs can improve resource utilization and reduce dependence on fossil fuel based heating. This trend is likely to favor technology providers offering integrated efficiency and emissions solutions rather than suppliers focused solely on combustion capacity. Within the Europe waste to energy market, carbon performance is therefore becoming a differentiating factor in plant modernization, investment selection and long term operating economics.
Ash and Residue Management Adds a Secondary Cost Burden
Ash management is becoming a more important cost and operational consideration in the Europe waste to energy market, particularly as plants face tighter requirements for residue treatment, material recovery and hazardous substance control.
European waste incineration generates substantial quantities of bottom ash and fly ash, with bottom ash typically representing the largest residue stream. CEWEP estimates that European waste incineration facilities produce approximately 15 million tonnes of bottom ash annually, creating a significant secondary material stream that requires processing before reuse or disposal. Bottom ash contains recoverable materials such as ferrous and non ferrous metals, but recovery requires additional equipment, maturation, screening and quality control infrastructure. Fly ash presents a more complex challenge because it contains higher concentrations of contaminants and generally requires specialized treatment before final disposal or recovery.
The European Commission's waste incineration framework specifically addresses bottom ash and air pollution control residues, increasing the importance of controlled handling throughout the plant lifecycle. For operators, residue management affects both operating expenditure and potential revenue. Advanced metal recovery can partially offset processing costs by generating secondary material revenues, while treated bottom ash can potentially substitute virgin aggregates in suitable construction applications.
However, contamination levels, national regulations and local end market acceptance determine whether recovery is commercially viable. This creates considerable differences between countries in the economic value of WtE residues. In mature markets, operators are increasingly moving toward integrated ash processing systems rather than treating residues purely as disposal liabilities. Such systems can include ferrous and non ferrous metal separation, ash washing, aging, stabilization and quality monitoring.
The Europe waste to energy market therefore has an emerging efficiency opportunity beyond electricity and heat generation: maximizing material recovery from residues can reduce disposal volumes while creating additional revenue streams. Plants unable to recover valuable materials may face comparatively higher net treatment costs, particularly where landfill or hazardous residue disposal charges increase. As new WtE facilities are designed and existing plants modernized, residue recovery capability is likely to become an increasingly important component of project economics, environmental performance and investment attractiveness.
Europe Waste to Energy Market Technology Cost Comparison
Technology economics in the Europe waste to energy market vary significantly because each route requires different feedstock preparation, conversion equipment, energy recovery systems and emission controls. Conventional mass burn incineration generally offers the strongest commercial maturity for mixed municipal residual waste because it can process large volumes without extensive upstream fuel preparation.
Capital expenditure for new European WtE incineration capacity can typically fall around €600 million to €1 billion for a 500,000 tonne per year facility, depending on configuration, location and emission control requirements. Anaerobic digestion has a lower capacity threshold and is better suited to separately collected organic waste, making it economically distinct from thermal WtE. Gasification and pyrolysis require more controlled feedstock characteristics and therefore face additional preprocessing requirements, which can increase project complexity.
Their potential advantage lies in producing syngas or other higher value outputs, but commercial deployment remains more selective than conventional incineration. Electricity only projects generally have weaker revenue diversification than combined heat and power facilities because recovered heat can provide an additional income stream where district heating infrastructure exists. Technology selection is therefore increasingly determined by feedstock quality, local energy prices, heat demand and residue handling costs rather than capital expenditure alone.
For the Europe waste to energy market, advanced flue gas cleaning represents a particularly important cost component because European environmental requirements require operators to control pollutants such as NOx, particulate matter, acid gases and mercury. High efficiency steam cycles can raise upfront investment but improve electricity recovery per tonne of waste, while heat recovery can materially improve overall energy utilization. Operators are also evaluating carbon capture integration, although the additional equipment and energy requirements currently create a significant cost premium. Consequently, the most attractive technology is increasingly the one that maximizes lifetime value across waste treatment, energy sales, residue recovery and environmental compliance rather than the technology with the lowest initial capital cost.
Europe Waste to Energy Market Waste Gate Fee Analysis
Waste gate fees are a critical revenue component for operators in the Europe waste to energy market, particularly because they provide income for accepting and treating waste in addition to electricity and heat revenues. Gate fees vary substantially across Europe according to landfill availability, recycling obligations, waste composition, plant capacity, local disposal alternatives and contract structures.
In markets where landfill taxes are high and disposal capacity is constrained, municipalities and commercial waste generators have a stronger economic incentive to route residual waste toward WtE facilities. The UK illustrates this dynamic, with WRAP reporting a median 2024/25 gate fee of £102 per tonne for local authority residual waste sent to energy from waste, compared with £29 per tonne for landfill, excluding landfill tax. However, the comparison changes substantially once landfill tax is included, creating a stronger economic case for WtE in high tax environments. In the Europe waste to energy market, long term municipal contracts can provide greater revenue visibility because operators receive contracted waste volumes and agreed treatment fees over extended periods.
Commercial and industrial waste can command different gate fees depending on calorific value, contamination and alternative treatment options. High calorific waste may be attractive because it increases energy output, while difficult or contaminated streams can generate higher treatment charges because of additional handling requirements. Gate fee economics also influence plant location because facilities need sufficient local waste availability to maintain throughput and justify capital investment.
Countries with strict landfill restrictions, high landfill taxation and limited residual waste treatment capacity can therefore offer stronger pricing environments for WtE operators. At the same time, increasing recycling and waste prevention can gradually reduce the quantity of residual waste available, creating a long term volume risk for plants that depend heavily on gate fee income. Operators are consequently placing greater emphasis on securing diversified feedstock contracts, optimizing plant efficiency and monetizing recovered heat, electricity and materials. For the Europe waste to energy market, gate fee levels should therefore be evaluated alongside energy revenues, landfill alternatives and contracted waste volumes rather than considered as a standalone pricing metric.
Europe Waste to Energy Market Plant Location Attractiveness Analysis
Plant location is a decisive factor in the Europe waste to energy market because project economics depend on securing sufficient residual waste, minimizing transportation distance and accessing reliable outlets for recovered electricity and heat. The most attractive locations are not necessarily the countries generating the largest quantities of waste; rather, they are areas where residual waste availability coincides with limited treatment capacity, established district heating networks and restrictive landfill economics.
Germany, Sweden, Denmark, the Netherlands and France offer particularly relevant location characteristics because of their mature waste treatment infrastructure and established energy recovery systems. Proximity to dense urban areas is especially important for CHP facilities because heat can be sold to district heating networks without excessive transmission losses. Industrial clusters can provide another advantage by creating year round demand for recovered steam or process heat. Port access also improves project attractiveness for larger facilities because equipment, construction materials and certain waste derived fuels can be transported efficiently.
Land availability and zoning remain important constraints, particularly around major metropolitan areas where competing industrial and residential land uses can increase development costs. Grid connection capacity is another location differentiator as high capacity WtE facilities require dependable electricity export infrastructure. Municipal contracting conditions are equally important because securing long term feedstock agreements reduces throughput risk and supports project financing.
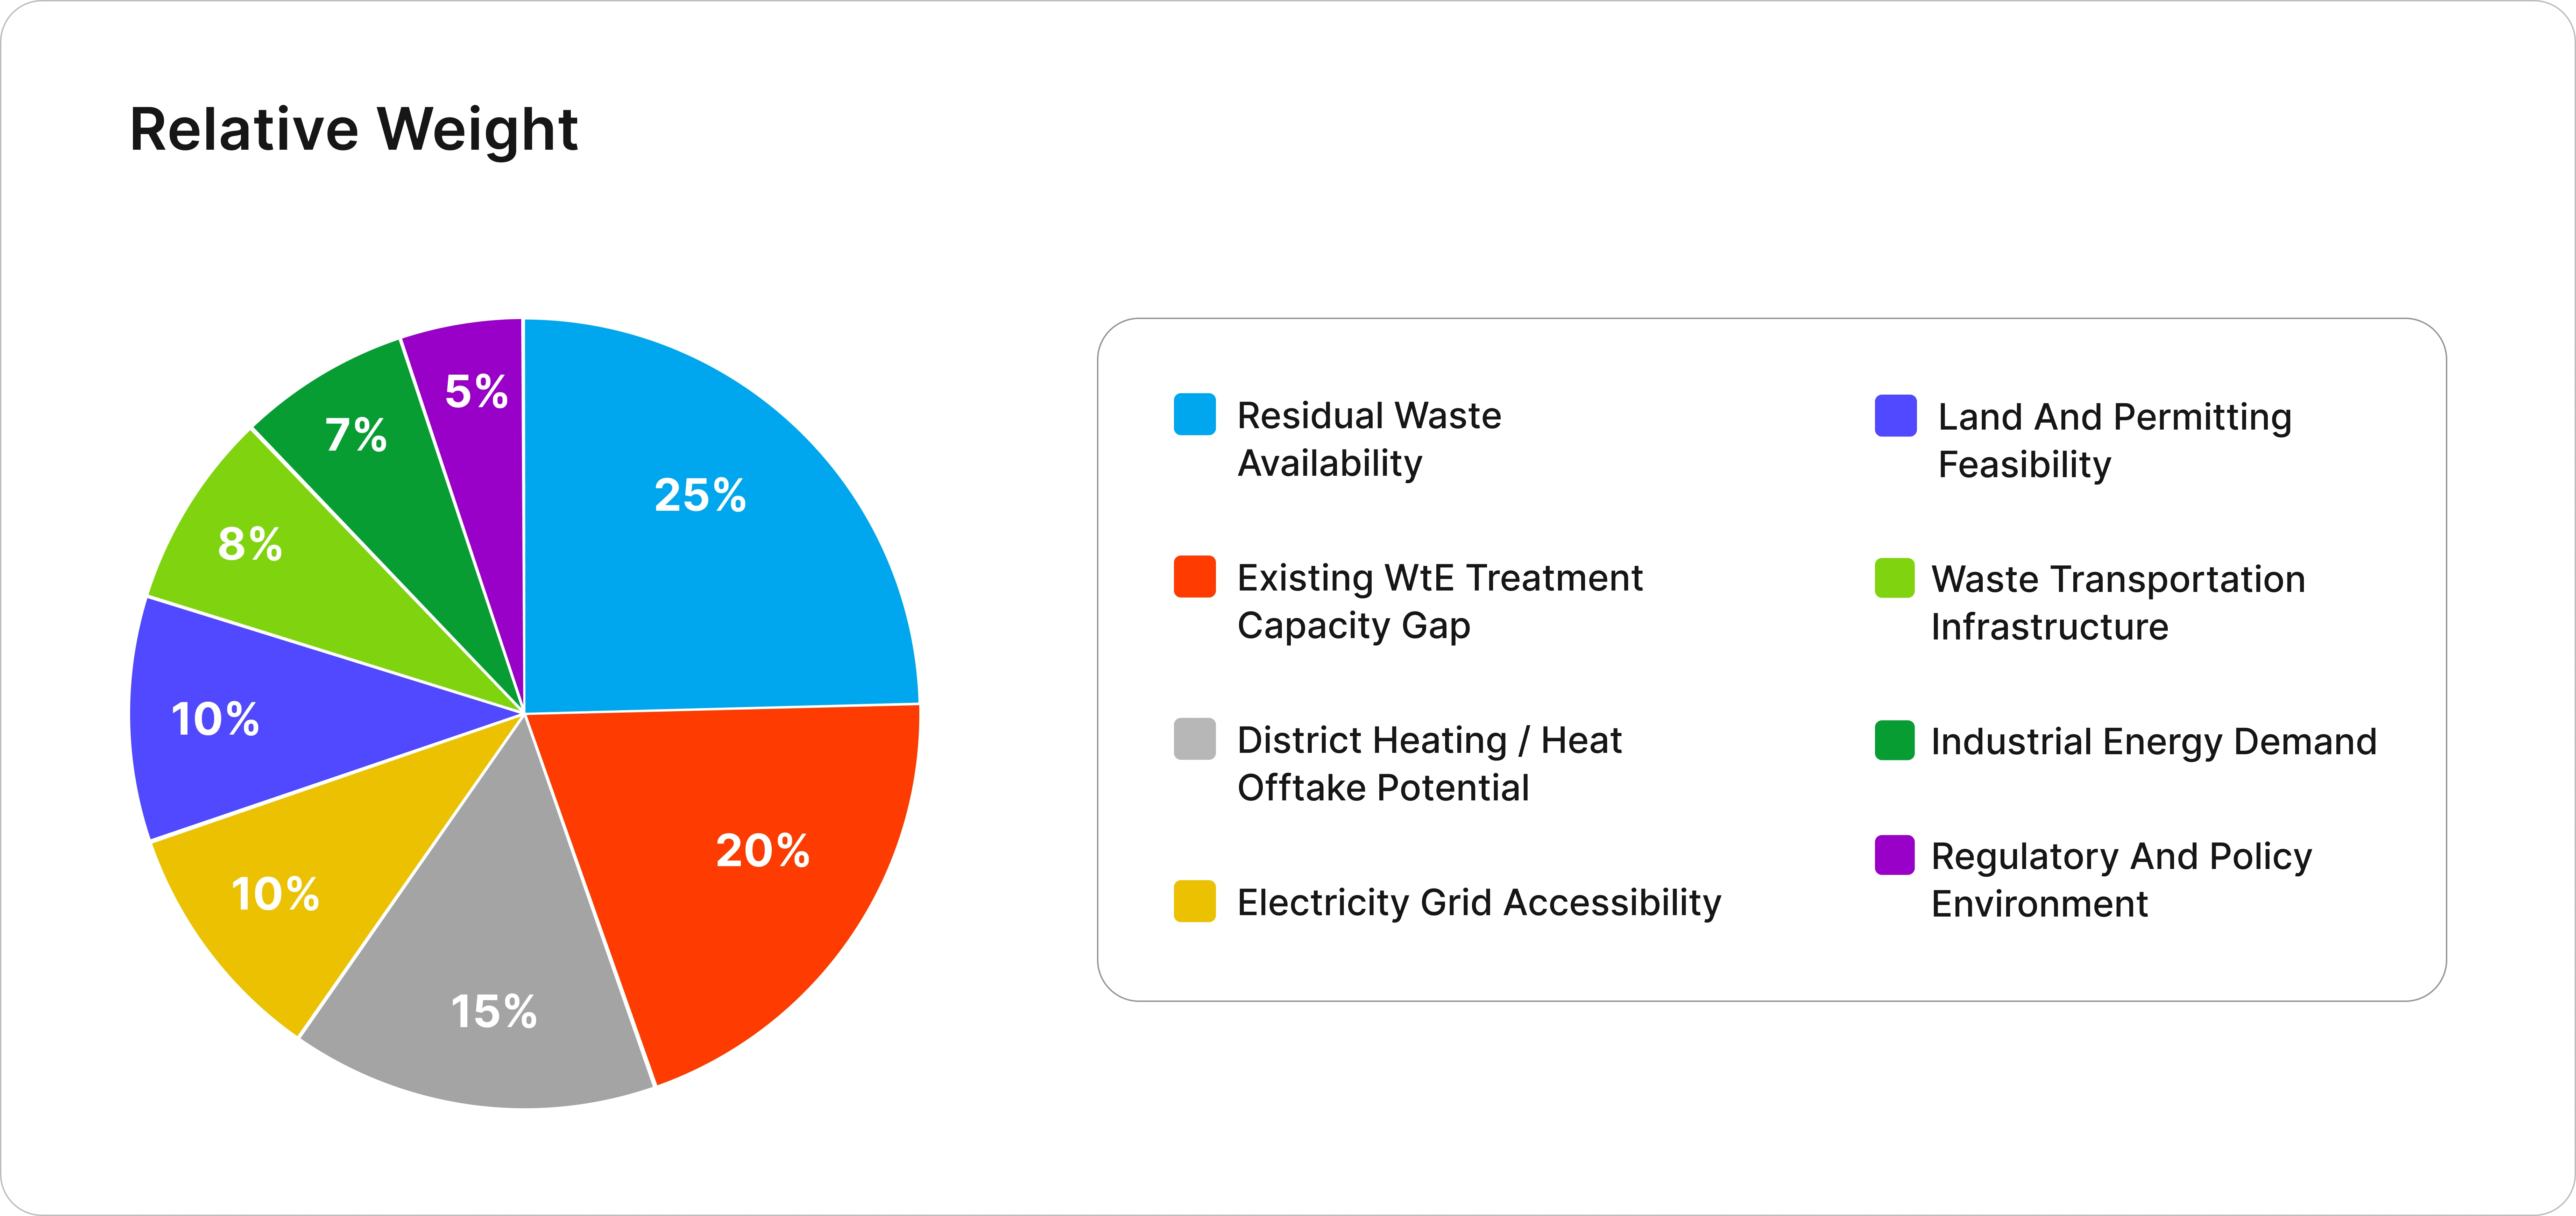
The Europe waste to energy market also shows substantial differences in residual waste treatment infrastructure between countries, creating opportunities in markets where landfill dependence remains relatively high but policy is moving toward greater recovery. Location attractiveness therefore depends on a combination of waste supply, energy offtake, infrastructure, regulation, logistics and permitting rather than a single market indicator. Developers increasingly evaluate sites using a weighted scoring framework covering waste availability, treatment capacity gap, district heating demand, grid accessibility, transport infrastructure, land availability and regulatory conditions.
This approach can identify locations where a plant can achieve high utilization while maximizing energy recovery and minimizing logistics costs. Consequently, future investment is likely to favor strategically located facilities integrated with municipal waste networks, industrial energy users and regional heat systems rather than standalone plants selected solely on land availability.
Europe Waste to Energy Market Risk Assessment Matrix
Risk exposure in the Europe waste to energy market is increasingly shaped by the interaction between waste availability, regulatory requirements, energy pricing and project economics rather than by technology risk alone. Feedstock risk remains significant because higher recycling, reuse and waste prevention can reduce residual waste volumes available for combustion, particularly for facilities designed around long operating lives.
Regulatory risk is also elevated as European environmental requirements continue to tighten emission control, residue treatment and carbon performance expectations, potentially requiring additional investment in existing plants. Revenue risk arises from fluctuations in wholesale electricity prices and differences in heat offtake potential between locations. Plants connected to district heating networks generally have greater opportunities to diversify energy revenues than electricity only facilities.
Construction and financing risk is another major consideration because WtE projects require substantial upfront investment and lengthy development periods, creating exposure to interest rates, equipment costs and construction delays. Ash management risk is becoming more relevant as operators face increasing requirements for residue treatment, metal recovery and controlled disposal of problematic fractions.
Public acceptance and permitting risk can also extend project timelines, particularly in densely populated regions where concerns over emissions, traffic and waste policy priorities can influence planning decisions. The Europe waste to energy market also faces technology specific risk where newer gasification, pyrolysis or advanced conversion systems have less operating history than conventional mass burn facilities. Supply chain disruption can affect specialist equipment such as boilers, turbines, flue gas treatment systems and pollution control components. However, risks are not uniform across Europe. Locations with long term municipal waste contracts, established district heating networks, stable regulatory frameworks and constrained disposal alternatives generally provide stronger risk mitigation. Investors should therefore assess individual projects through a combined probability and financial impact framework rather than applying a uniform European risk assumption. Plants with diversified revenue streams, secured feedstock agreements and proven technology are positioned to withstand market volatility more effectively.
Competitive Landscape
Key companies analyzed within the Europe waste to energy market are: Veolia, SUEZ, KanadeviaInova, Indaver, EEW Energy from Waste GmbH, MARTIN GmbH, Mitsubishi Heavy Industries Environmental & Chemical Engineering, Babcock & Wilcox Enterprises, Fortum, Ramboll, Covanta, Urbaser, Keppel Infrastructure, CNIM, Steinmüller Babcock Environment, EQTEC, A2A, PreZero, Renewi, Valmet and others.
Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) for the Europe waste to energy market evaluates companies based on their ability to secure feedstock, deliver efficient energy recovery and execute large scale projects under increasingly stringent European environmental requirements.
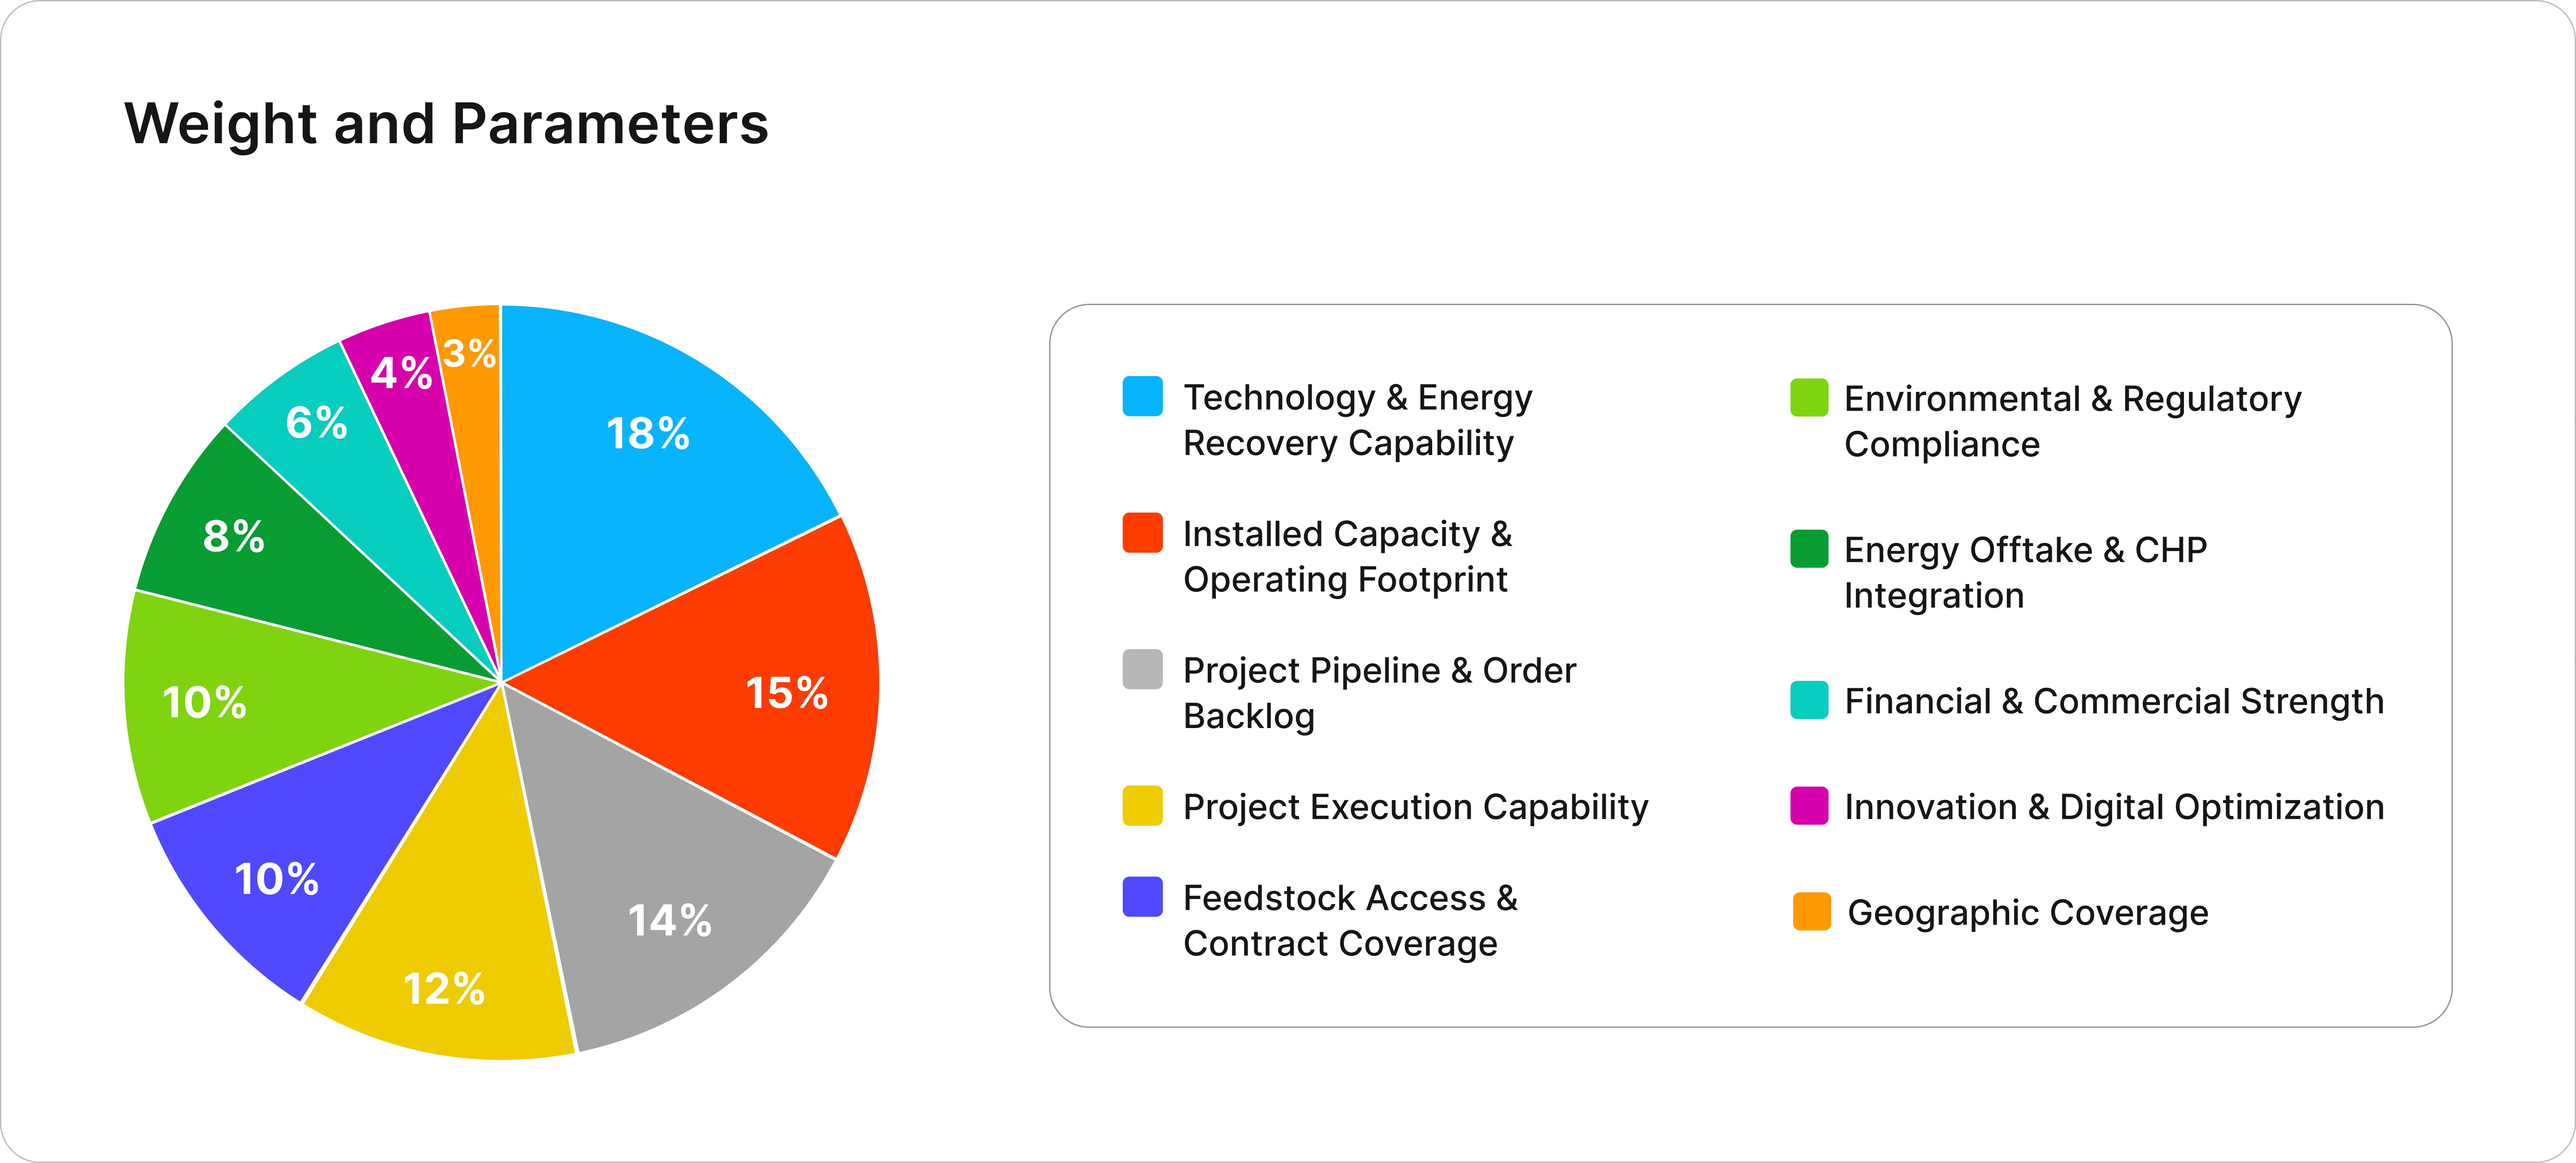
The framework places greater emphasis on technology execution, installed capacity and project pipeline than on conventional corporate indicators. Technology capability measures combustion efficiency, flue gas treatment, energy recovery and residue processing expertise. Project execution assesses the company's ability to deliver complex WtE facilities within planned timelines and budgets. Installed footprint captures operational presence across major European markets, while project pipeline indicates future competitive positioning. Feedstock access is particularly important because long term municipal and commercial waste contracts support plant utilization and revenue visibility.
Energy recovery capability evaluates electricity generation, CHP integration and heat offtake potential. Regulatory and environmental compliance assesses the company's ability to meet emission and residue management requirements. Commercial strength considers contract wins, customer relationships and financial capacity to support capital intensive projects. Innovation capability captures digital optimization, advanced sorting, carbon management and next generation conversion technologies. The resulting weighted score enables consistent benchmarking of major WtE technology providers, operators and integrated environmental services companies across Europe.

