Key Takeaways
- Market volume is projected to grow from 1,120 KT in 2024 to 2,835 KT by 2033, reflecting robust long-term demand.
- The U.S. battery materials market is expected to register a CAGR of 10.8% during 2027–2033, driven by domestic battery manufacturing expansion.
- Lithium-ion batteries remain the largest consumer of cathode, anode, electrolyte, and separator materials across major applications.
- Gigafactory expansion across the Southeast and Midwest is creating regional demand hubs for battery materials and chemical processing.
- Cathode active materials (CAM) and graphite anodes account for the highest material consumption in battery cell production.
- Energy Storage Systems (ESS) are emerging as the fastest-growing application, accelerating demand for LFP-related materials.
U.S. Battery Materials Market Outlook
U.S. Battery Materials Market recorded a sales volume of 1,260 Kilo tons in 2025 and is estimated to reach a volume of 2,835 kilo tons by 2033 with a CAGR of 10.8% during the forecast period.
U.S. Battery Market Dynamics
Expansion of Gigafactory Ecosystems Creating Regional Demand Clusters for Battery Materials
The rapid expansion of battery gigafactories across the United States is reshaping procurement patterns by creating concentrated regional demand clusters for battery materials instead of relying on dispersed sourcing networks. This shift is significantly accelerating the growth of the U.S. battery materials market. Since 2022, over 35 announced battery cell and module manufacturing projects have emerged in states such as Kentucky, Tennessee, Georgia, Michigan, Ohio, Nevada, and North Carolina, which together represent more than 1 terawatt-hour (TWh) of planned annual battery production capacity by the early 2030s.
This concentration of manufacturing is driving concurrent investments in the production of cathode active materials (CAM), precursor cathode active materials (pCAM), anode materials, electrolytes, separators, copper foil, and aluminum foil within a few hundred miles of these facilities. The aim is to reduce transportation costs, minimize inventory requirements, and mitigate supply chain risks. For instance, the Southeast U.S. has become a major battery manufacturing corridor where multiple electric vehicle (EV) assembly plants and battery gigafactories are fostering integrated ecosystems. These ecosystems encourage suppliers to set up localized refining and processing operations.
A typical battery cell plant with a capacity of 40–50 GWh may consume around 70,000–90,000 metric tons of cathode materials, 45,000–60,000 metric tons of graphite anode materials, and thousands of tons of electrolyte chemicals each year. This creates sustained regional demand for upstream battery material suppliers. The geographic clustering also supports just-in-time manufacturing strategies, allowing battery producers to shorten lead times, reduce logistics expenses, and enhance production resilience in the face of global supply disruptions.
Additionally, co-location facilitates technical collaboration between cell manufacturers and material suppliers, speeding up the qualification processes for advanced materials such as silicon-enhanced anodes, high-nickel cathodes, and next-generation electrolyte formulations. These regional ecosystems are also attracting investments in battery recycling facilities, which can supply recovered lithium, nickel, cobalt, manganese, and graphite back into nearby manufacturing plants, thereby strengthening the circular supply chains.
As the capacity utilization of gigafactories increases over the next decade, the U.S. battery materials market is expected to thrive on localized demand hubs that stimulate further growth in chemical processing, precursor manufacturing, and advanced material production while decreasing reliance on imported intermediate battery materials.
Limited Domestic Refining Capacity for Battery-Grade Lithium Chemicals
A significant constraint facing the U.S. battery materials market is the limited domestic capacity to refine lithium into battery-grade chemicals, despite considerable investments in electric vehicle and battery manufacturing. While lithium resources are available in states like Nevada, North Carolina, and Arkansas, much of the mined lithium concentrate still requires conversion into battery-grade lithium carbonate or lithium hydroxide through specialized refining processes, which the domestic industry struggles to meet.
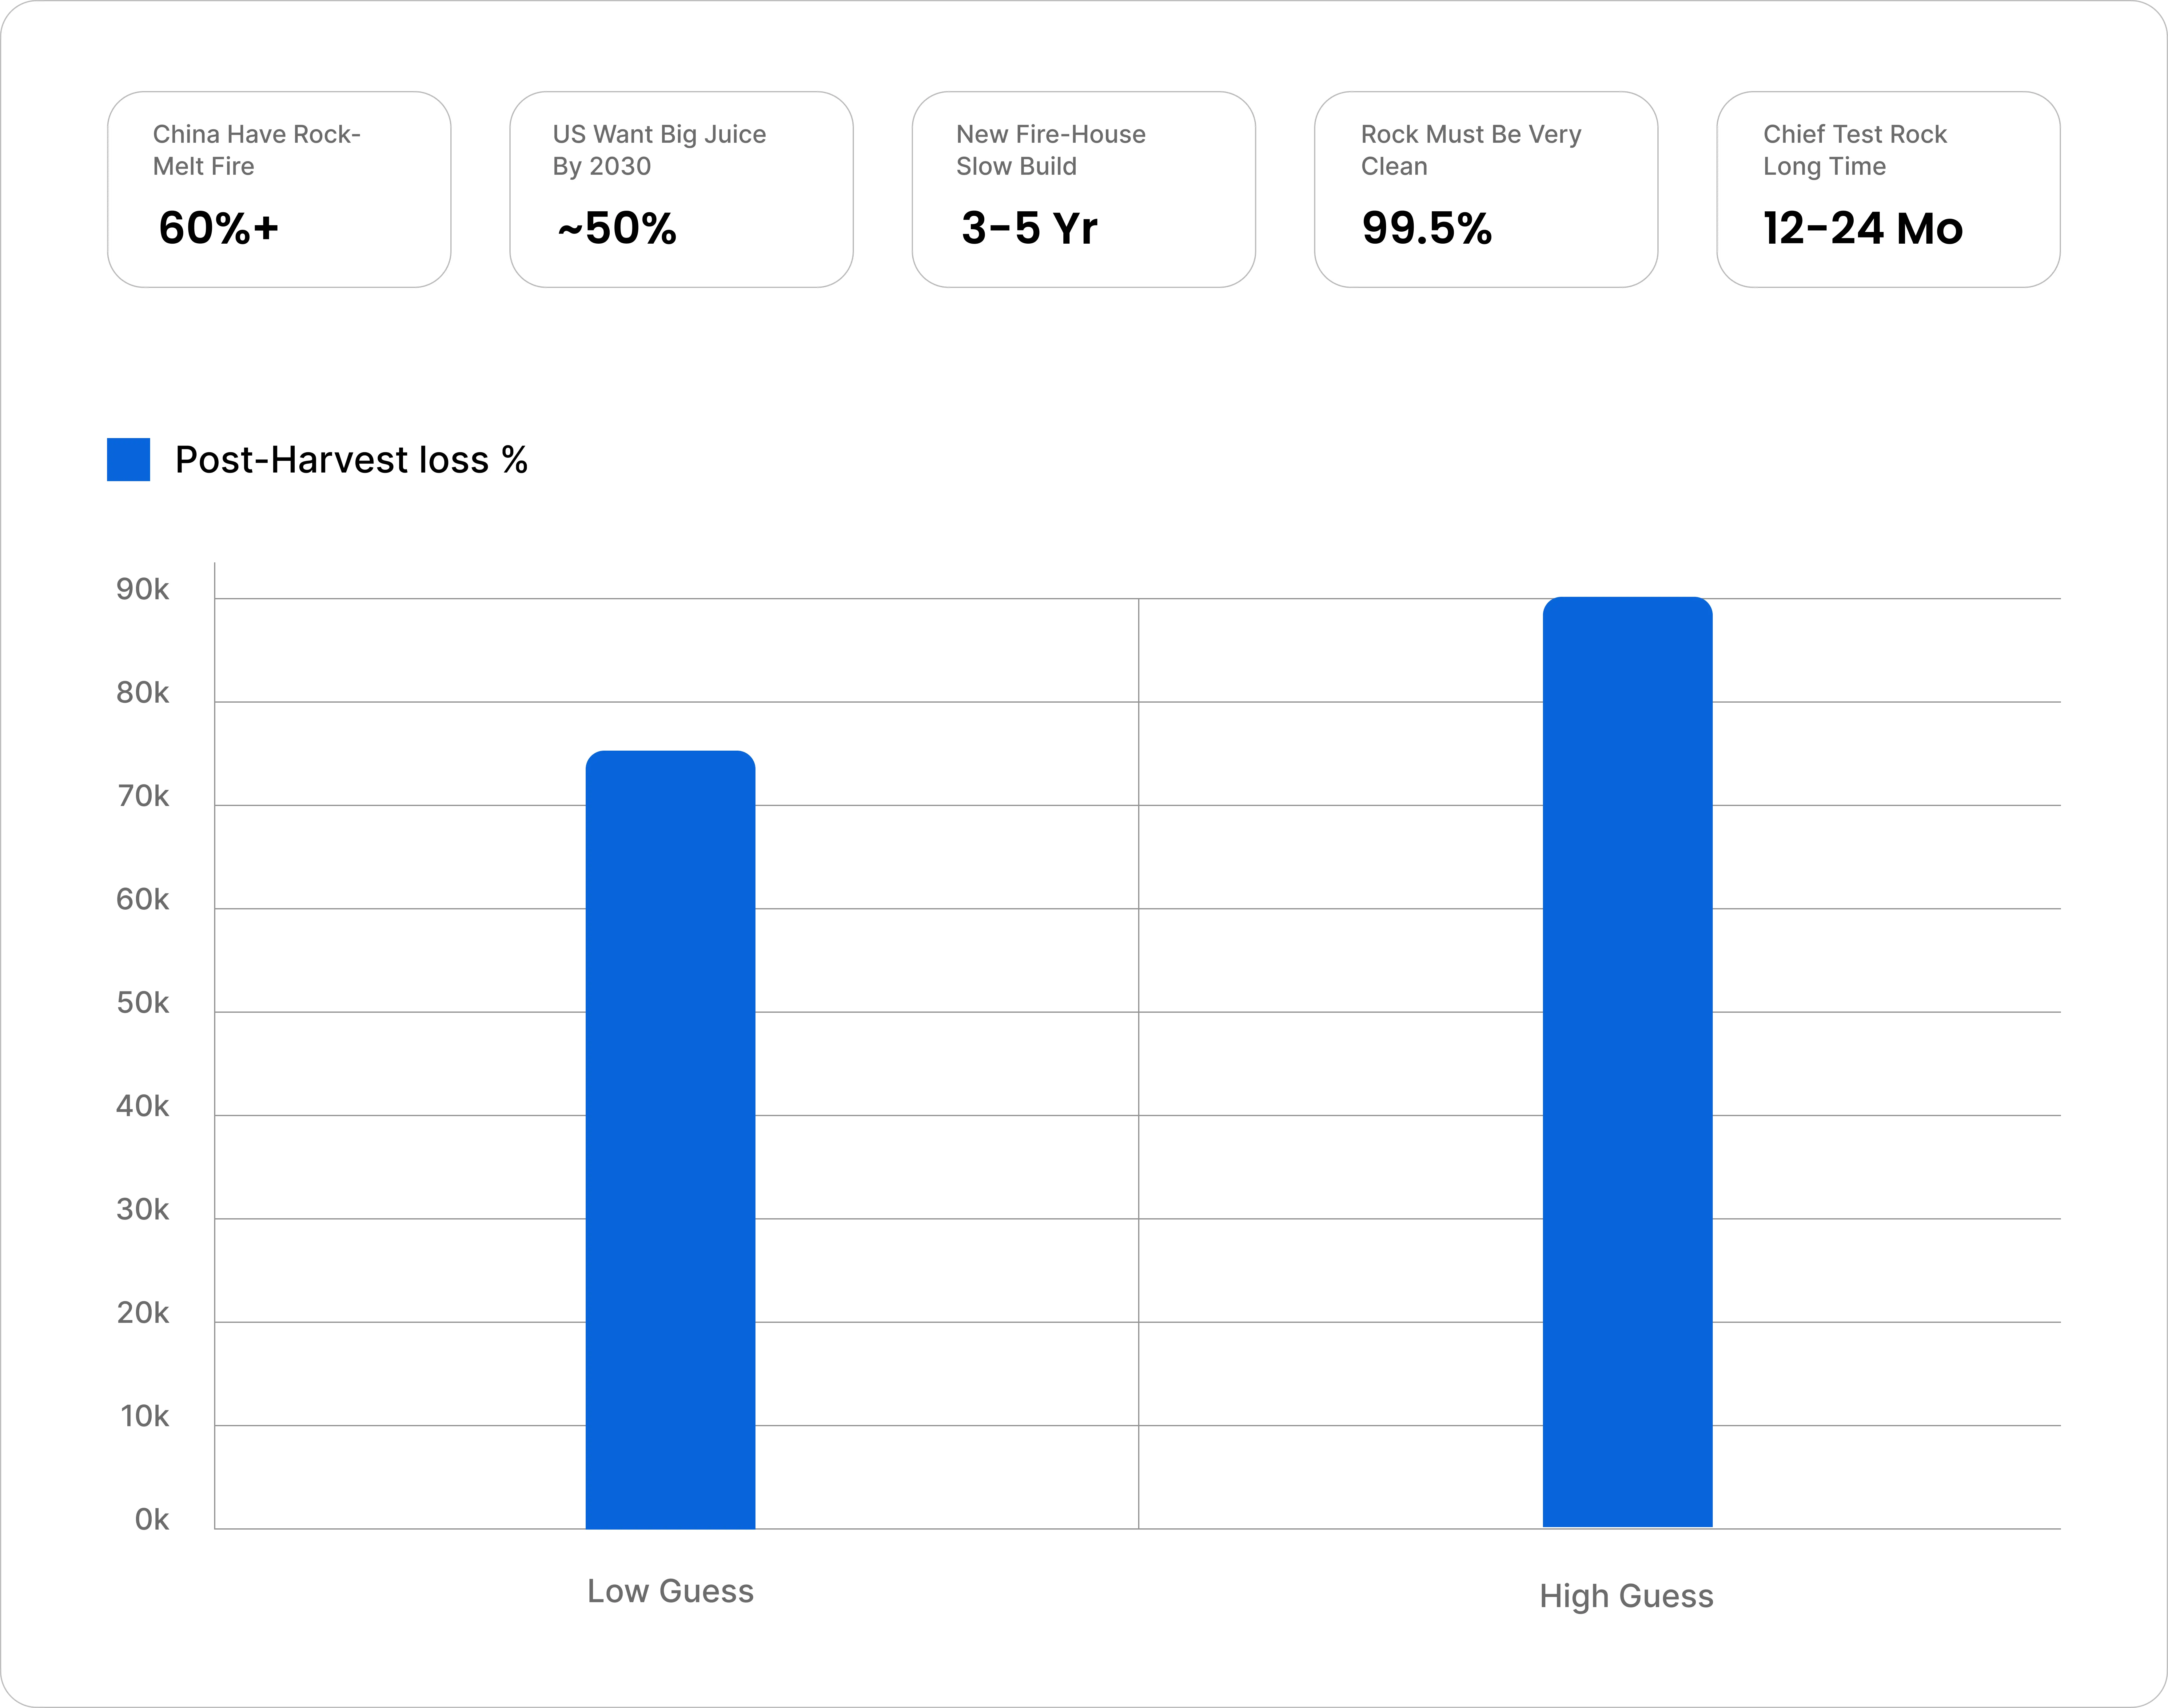
Over 60% of global lithium chemical refining capacity is concentrated in China, leading to a supply chain imbalance for U.S. battery manufacturers who want locally sourced materials. Meanwhile, the U.S. is projected to support over 1 TWh of announced battery cell manufacturing capacity by the early 2030s, necessitating hundreds of thousands of metric tons of battery-grade lithium chemicals each year. A typical 100 GWh lithium-ion battery plant can consume about 75,000–90,000 metric tons of lithium hydroxide equivalent throughout its supply chain, emphasizing the growing gap between downstream cell production and upstream refining capability.
Although new refining projects have been announced in states like Nevada and Texas, the commercial commissioning of these facilities often takes 3–5 years due to the complexities of permitting, environmental reviews, technology qualification, and the need for substantial capital investment. Additionally, producing battery-grade lithium chemicals with purity levels exceeding 99.5% presents challenges that require advanced impurity removal and crystallization technologies, complicating process optimization compared to conventional mineral refining.
These technical barriers not only increase production costs but also slow the qualification process for domestic suppliers by automotive OEMs and battery manufacturers, whose validation cycles can extend from 12 to 24 months before commercial contracts are finalized. As a result, many U.S. cell manufacturers continue to rely on imported lithium hydroxide and lithium carbonate to maintain their production schedules, which exposes the U.S. battery materials market to global price fluctuations, geopolitical supply risks, and longer procurement lead times. Expanding domestic refining infrastructure has become a critical priority for enhancing supply chain resilience and supporting the long-term localization of battery manufacturing within the United States.
U.S. Battery Materials Market Product Matrix
The application landscape of the U.S. battery materials market is notably diverse, influenced by varying battery chemistries that drive distinct material compositions and processing needs. Lithium-ion batteries dominate the market, accounting for the largest share of battery material consumption, primarily due to their widespread use in electric vehicles (EVs), energy storage systems (ESS), consumer electronics, and cordless power tools.
High-performance EV batteries necessitate substantial quantities of cathode active materials, particularly lithium iron phosphate (LFP) and nickel manganese cobalt (NMC). Additionally, they require synthetic or natural graphite anodes, electrolyte salts, separator films, as well as high-purity copper and aluminum foils. As utility-scale ESS installations expand, LFP chemistry has gained traction owing to its longer cycle life, enhanced thermal stability, and reduced reliance on critical minerals like cobalt and nickel.
Emerging solid-state batteries represent a strategic growth area, especially for premium EVs, aerospace, and defense applications. Their potential to achieve energy densities exceeding 400 Wh/kg stands in contrast to the approximately 250–300 Wh/kg of conventional lithium-ion cells. This shift is prompting increased research investment in solid electrolytes, lithium metal anodes, and advanced ceramic materials.
Meanwhile, sodium-ion batteries are garnering attention for stationary energy storage and cost-sensitive applications due to the abundance of sodium relative to lithium, which lowers dependence on imported critical minerals. However, their commercialization is still in its early stages.
Lead-acid batteries continue to hold significant market presence in industrial equipment, backup power systems, marine vessels, and telecommunications infrastructure, where their reliability and recyclability are valued over energy density. In fact, the United States boasts a recycling rate of over 95% for lead-acid batteries, making them one of the most circular battery technologies available.
Nickel-based batteries also remain relevant in aerospace, defense, aviation, and specialized medical equipment applications due to their high reliability in extreme conditions and long service life. As battery technologies evolve to meet specific performance requirements, the U.S. battery materials market is witnessing growing demand for specialized cathode chemistries, advanced anode materials, conductive additives, electrolyte formulations, and separator technologies. This trend is prompting manufacturers to focus on developing material portfolios tailored to specific applications rather than relying solely on a single battery chemistry.
Competitive Analysis
Key companies analyzed within the U.S. battery materials market are: Albemarle Corporation, Rio Tinto Lithium , MP Materials (rare-earth/magnet materials, adjacent to core battery chemistry), American Battery Technology Company, Sila Nanotechnologies, NOVONIX, Cabot Corporation, Orbia Fluor & Energy Materials, 3M, Dow, Eastman Chemical Company, PPG Industries, Honeywell, Koura, Aspen Aerogels, Ascend Elements, Redwood Materials, Cirba Solutions, Syrah Resources and others.
Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) offers a comprehensive evaluation of participants in the U.S. battery materials market. It measures their capability to provide high-quality battery materials while adapting to changing battery chemistries and domestic supply chain requirements. Instead of focusing solely on revenue or production volume, this framework assesses companies across the entire battery materials value chain. This includes activities such as lithium refining, manufacturing cathode and anode materials, producing electrolytes, developing separator technologies, and recycling capabilities, along with their strategic partnerships with battery cell manufacturers.
| Assessment Parameter |
Weight (%) |
| Production Capacity & Scalability |
20 |
| Battery Material Technology Portfolio |
15 |
| Battery-Grade Product Quality & Purity |
12 |
| Vertical Integration Across the Value Chain |
10 |
| Strategic Partnerships & Long-Term Offtake Agreements |
10 |
| Domestic Manufacturing & Supply Chain Localization |
10 |
| Innovation & R&D in Advanced Battery Materials |
8 |
| Customer Base & End-Use Diversification |
5 |
| Recycling & Circular Economy Capabilities |
5 |
| Financial Stability & Capital Investment |
3 |
| ESG, Traceability & Regulatory Compliance |
2 |
Companies are scored based on several factors, including their installed and announced production capacity, battery-grade material purity, technology portfolio, customer diversification, vertical integration, localization of manufacturing assets, and long-term supply agreements with automotive OEMs and battery producers. There is particular emphasis on investments in advanced materials like silicon-based anodes, high-nickel cathodes, lithium iron phosphate (LFP) materials, and solid-state battery components.
The framework also evaluates each company's ability to scale production while adhering to stringent quality specifications, traceability requirements, and sustainability standards expected by the automotive industry. Innovation is assessed through the commercialization of next-generation materials, the development of intellectual property, and the expansion of domestic refining and recycling infrastructures.
Competitive positioning is further bolstered by factors such as regional manufacturing presence, resilience to raw material price volatility, and strategic partnerships across sectors, including mining, refining, battery manufacturing, and recycling. By integrating quantitative production metrics with qualitative strategic insights, EICAF provides a thorough comparison of market participants, helping to identify the companies best positioned to seize long-term growth opportunities within the U.S. battery materials market.
Related Titles
Why the U.S. Battery Materials Market Is Entering a New Growth Phase with Domestic Supply Chain Investments
Battery-Grade Lithium, Graphite, and Cathode Materials: Which Segment Will Drive the U.S. Market Through 2033
U.S. Battery Materials Market Trends 2025: How EV Manufacturing and Energy Storage Are Transforming Material Demand
Risk Assessment Matrix: Mapping the Critical Vulnerabilities Facing the U.S. Battery Materials Market

