Key Finding
- Market value is projected to increase from USD 63.1 billion (2024) to USD 139.3 billion (2034).
- Market volume is forecast to grow from 40.7 million tons (2024) to 76.1 million tons (2034).
- The market is expected to register a 9.5% CAGR (value) and 7.8% CAGR (volume) during 2027–2033.
- Average selling price is anticipated to increase from USD 1,550/ton (2024) to USD 1,830/ton (2034).
- Paper & paperboard remain the dominant material segment due to high recyclability and mature collection systems.
- Food & beverages represent the largest end-use industry for eco-friendly packaging.
- Germany, France, the UK, Italy, and the Nordic countries are the leading regional markets.
- The PPWR and Circular Economy Action Plan are accelerating packaging redesign and recycled-content adoption.
Europe Eco Friendly Packaging Market Outlook
Europe Eco Friendly Packaging Market recorded a consumption of 43.1 million tons in 2025 and is estimated to reach a volume of 76.1 million tons by 2033 with a CAGR of 7.8% during the forecast period.
Europe Eco Friendly Packaging Market Dynamics
Deposit Return Schemes (DRS) Increasing Availability of High-Quality Recycled Packaging Materials
Deposit Return Schemes (DRS) have emerged as a vital policy mechanism driving the eco-friendly packaging market in Europe, enhancing the collection and quality of post-consumer packaging materials. Through a DRS, consumers are required to pay a refundable deposit on eligible beverage containers, which creates a financial incentive for them to return used packaging at designated collection points. Unlike mixed municipal waste streams, these deposit systems yield cleaner and better-sorted materials, allowing recyclers to produce high-quality recycled polyethylene terephthalate (rPET), aluminum, and glass suitable for closed-loop applications.
Various European countries have showcased the effectiveness of this approach, achieving beverage container return rates that often exceed 90%. Notably, Germany has consistently maintained collection rates around 98% for eligible single-use beverage containers. Nordic countries such as Finland and Norway have also reported return rates above 90%, ensuring a steady supply of premium recycled feedstock for packaging manufacturers.
As European packaging producers prepare for stricter recycled-content requirements under changing EU legislation, the availability of food-grade recycled materials is becoming increasingly crucial. High-quality recovered PET reduces reliance on virgin fossil-based polymers and supports bottle-to-bottle recycling, aligning with Europe's circular economy strategy.
DRS also enhances the economics of recycling by minimizing contamination levels, cutting sorting costs, and boosting material recovery yields compared to traditional curbside collection systems. Beverage brands, retailers, and packaging converters are investing in recycling partnerships and advanced processing technologies to make the most of this reliable feedstock stream, thereby strengthening regional supply chain resilience.
With the growing adoption of reverse vending machines, digital deposit tracking, and automated collection infrastructure, operational efficiency and consumer participation are being further enhanced across various European markets. As more countries expand or introduce national DRS programs, the volume of high-purity recyclable materials available for reuse is projected to increase steadily. This trend will support innovation in recyclable packaging formats and reinforce the shift towards circular packaging systems. Consequently, Deposit Return Schemes are expected to remain a strategic driver of growth, improving raw material security, reducing waste leakage, and accelerating the utilization of sustainable materials throughout the eco-friendly packaging market in Europe.
Inconsistent Recycling Infrastructure Across Eastern and Southern European Countries
The uneven recycling infrastructure across Eastern and Southern Europe represents a significant challenge for the eco-friendly packaging market in Europe. This inconsistency limits the availability of high-quality secondary raw materials and hampers the region’s shift toward a fully circular packaging economy. While several countries in Western and Northern Europe have successfully developed advanced systems for collection, sorting, and recycling, many nations in the eastern and southern regions struggle with lower collection rates, inadequate sorting capabilities, and inconsistent investment in modern recycling facilities.
Disparities in municipal waste management, public engagement, funding availability, and the implementation of extended producer responsibility (EPR) schemes result in considerable variations in recycling performance across the continent. Although European environmental statistics indicate that the average recycling rate for packaging waste in the European Union exceeds 65%, performance varies significantly among member states; some countries recycle over 80% of their packaging waste, while others fall below 50%.
Plastic packaging poses an even greater challenge, with recycling rates varying widely based on local infrastructure and the ability to handle complex or multi-layer materials. Access to advanced optical sorting technologies, food-grade plastic recycling solutions, and chemical recycling capacity is limited, which affects the production of high-quality recycled polymers that packaging manufacturers require. In many areas, recyclable materials are still transported great distances for processing, leading to increased logistics costs, higher greenhouse gas emissions, and more complex supply chains.
Moreover, infrastructure gaps further diminish the availability of reliable recycled feedstock, compelling converters to rely more on virgin materials or imported recyclates to fulfill sustainability goals and regulatory requirements. Investment imbalances among member states slow the modernization of waste collection networks, digital traceability systems, and automated material recovery facilities. While financial assistance from European funding programs is helping to expand recycling capacity, progress is inconsistent due to differences in administrative capabilities and the timelines for project implementation.
The lack of harmonized recycling performance across Europe creates uncertainty for packaging producers in search of dependable sources of recycled content and escalates compliance costs linked to evolving packaging regulations. Addressing these regional infrastructure disparities will be crucial for enhancing material circularity, securing feedstock availability, and promoting sustainable growth within the European eco-friendly packaging market.
Europe Ecofriendly Packaging Market: Consumer Behavior Analysis
Consumer behavior is becoming a crucial factor that shapes product innovation and purchasing strategies in the European eco-friendly packaging market. Environmental awareness has transformed from a niche preference into a mainstream purchasing criterion. Shoppers are now evaluating packaging alongside product quality, price, and brand reputation. There is a noticeable shift toward packaging that is easily recyclable, contains recycled content, minimizes plastic use, and clearly communicates disposal instructions.
European consumers are also placing a greater emphasis on transparency, preferring brands that offer verifiable sustainability claims rather than vague environmental messaging. Younger consumers, particularly Millennials and Generation Z, are more inclined to support products packaged in renewable or reusable materials and tend to reward companies that demonstrate measurable progress toward circular economy goals.
The rapid rise of online grocery shopping and e-commerce has heightened expectations for lightweight, protective, and recyclable delivery packaging that minimizes unnecessary material consumption. Convenience remains a significant factor in purchasing decisions, pushing manufacturers to balance sustainability with functionality, durability, shelf life, and ease of use.
There is a positive consumer response to refill systems, returnable containers, and packaging designed for multiple use cycles, especially in the personal care, household products, and premium beverage sectors. However, concerns over greenwashing have made consumers more cautious, elevating the significance of third-party certifications, standardized recycling symbols, and comprehensive environmental information on packaging labels.
Many consumers are willing to accept premium pricing for environmentally responsible products, provided that sustainability benefits are clearly demonstrated. Nonetheless, affordability continues to play a crucial role in purchasing decisions, particularly during economic downturns. Retailers are responding to these preferences by expanding their sustainably packaged private-label offerings and collaborating with suppliers to decrease virgin plastic consumption.
As digital technologies such as QR codes for product information and Digital Product Passports gain traction, consumers are acquiring better insights into material sourcing, recyclability, and carbon footprints. These changing purchasing patterns are prompting packaging manufacturers to invest in recyclable mono-material designs, renewable fiber solutions, and circular packaging systems, positioning consumer expectations as a long-term driver for innovation and competitive differentiation within the European eco-friendly packaging market.
Europe Ecofriendly Packaging Market: Recycling Infrastructure Investment Outlook
Investment in recycling infrastructure is becoming a crucial driver for growth in the European eco-friendly packaging market. Various stakeholders including governments, packaging manufacturers, waste management companies, and consumer goods producers are collaborating to enhance circular material flows and reduce reliance on virgin raw materials. The European Union has set ambitious sustainability goals for packaging through the Circular Economy Action Plan and the Packaging and Packaging Waste Regulation (PPWR). This has led to significant capital investment in collection systems, material recovery facilities (MRFs), advanced sorting technologies, and high-quality recycling plants.
In the EU, packaging waste recycling already surpasses 65%, with recycling rates for paper and cardboard packaging exceeding 80%. This highlights both the effectiveness of existing infrastructure and the need for increased capacity, particularly for plastic, flexible, and multi-material packaging. Substantial investments are now being directed toward technologies such as artificial intelligence-enabled optical sorting systems, robotics, digital material identification, and food-grade polyethylene terephthalate (rPET) recycling facilities to enhance recovery efficiency and minimize contamination.
Additionally, chemical recycling technologies are gaining traction for processing challenging packaging waste that cannot be easily handled by conventional mechanical methods. Several European countries are also expanding Deposit Return Scheme (DRS) networks, installing reverse vending machines, and implementing digital waste collection systems to improve collection quality and secure cleaner secondary raw materials.
Public funding from European Union cohesion programs, innovation funds, and national green transition initiatives is speeding up the modernization of recycling infrastructure, especially in Central and Eastern Europe, where processing capacity is comparatively lower. At the same time, private investment is rising through partnerships among packaging producers, retailers, resin manufacturers, and waste management companies that aim to create closed-loop recycling systems.
These investments are expected to enhance feedstock security, mitigate raw material price volatility, support compliance with recycled-content requirements, and bolster domestic supply chains for sustainable packaging production. Moreover, the expansion of high-quality recycling infrastructure will reduce dependence on imported recyclates while improving resource efficiency and lowering greenhouse gas emissions associated with packaging manufacturing. As recycling capacity continues to grow throughout Europe, infrastructure modernization will be integral to enhancing material circularity, fostering innovation in recyclable packaging formats, and strengthening the long-term competitiveness of the European eco-friendly packaging market.
Europe Ecofriendly Packaging Market: Circular Economy Adoption Scenario
The transition toward a circular economy is shaping the European eco-friendly packaging market as a defining structural trend. Regulatory reforms, corporate sustainability initiatives, and technological advancements are accelerating the shift from a linear "take-make-dispose" model to a regenerative packaging ecosystem. Under the European Union's Circular Economy Action Plan and the Packaging and Packaging Waste Regulation (PPWR), packaging design is increasingly focused on remaining within the economy through reuse, repair, collection, recycling, and incorporation into new products. Currently, more than 65% of packaging waste generated across the EU is recycled, with paper and cardboard packaging achieving recycling rates exceeding 80%, offering a solid foundation for circular material utilization.
Deposit Return Schemes in various European countries achieve impressive beverage container collection rates of 90–98%, ensuring a reliable supply of high-quality recycled materials for closed-loop applications. Packaging manufacturers are actively redesigning products to eliminate unnecessary materials, improve mono-material construction, increase recycled content, and facilitate easier sorting at the end of their life cycle. Retailers and consumer goods companies are expanding pilots for reusable packaging, refill stations, returnable transport packaging, and standardized packaging formats to extend product life cycles and reduce reliance on virgin materials.
Digital technologies such as QR-enabled traceability, Digital Product Passports, and AI-assisted waste sorting are enhancing transparency and material recovery efficiency throughout the packaging value chain. Increased investment in mechanical and chemical recycling infrastructure is boosting the availability of secondary raw materials, reducing dependence on imported feedstocks, and supporting compliance with evolving recycled content requirements. Capital is increasingly directed toward circular packaging innovations by financial institutions and corporate investors as environmental, social, and governance (ESG) considerations become more prominent in investment strategies.
While challenges remain in harmonizing recycling systems across member states and improving collection for flexible packaging formats, the overall adoption trajectory is strengthening. As regulatory requirements become more stringent and circular business models gain wider commercial acceptance, material recirculation rates are expected to improve significantly, enhancing resource efficiency, reducing lifecycle emissions, and bolstering long-term competitiveness in the European eco-friendly packaging market.
Competitive Analysis
Key companies analyzed within the Europe eco friendly packaging market are: DS Smith , Smurfit WestRock , Mondi , Stora Enso , UPM-Kymmene , Huhtamaki , Metsä Board , Paptic , Sulapac , Neste , Billerud , AR Packaging , PulPac , SIG Group , Tetra Pak , Amcor , Coveris , Mayr-Melnhof Group , Alpla , Borealis , Constantia Flexibles , Faerch , Papacks , Novamont , Elopak , Verallia , Ardagh Group , EcoCortec and others.
Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) is designed to evaluate companies within the European eco-friendly packaging market. Its focus is on their capacity for sustainable growth, regulatory compliance, technological innovation, and competitive resilience. Unlike traditional benchmarking models that primarily assess revenue or market share, EICAF offers a more holistic view by integrating operational, environmental, commercial, and innovation capabilities for a comprehensive assessment of long-term competitiveness.
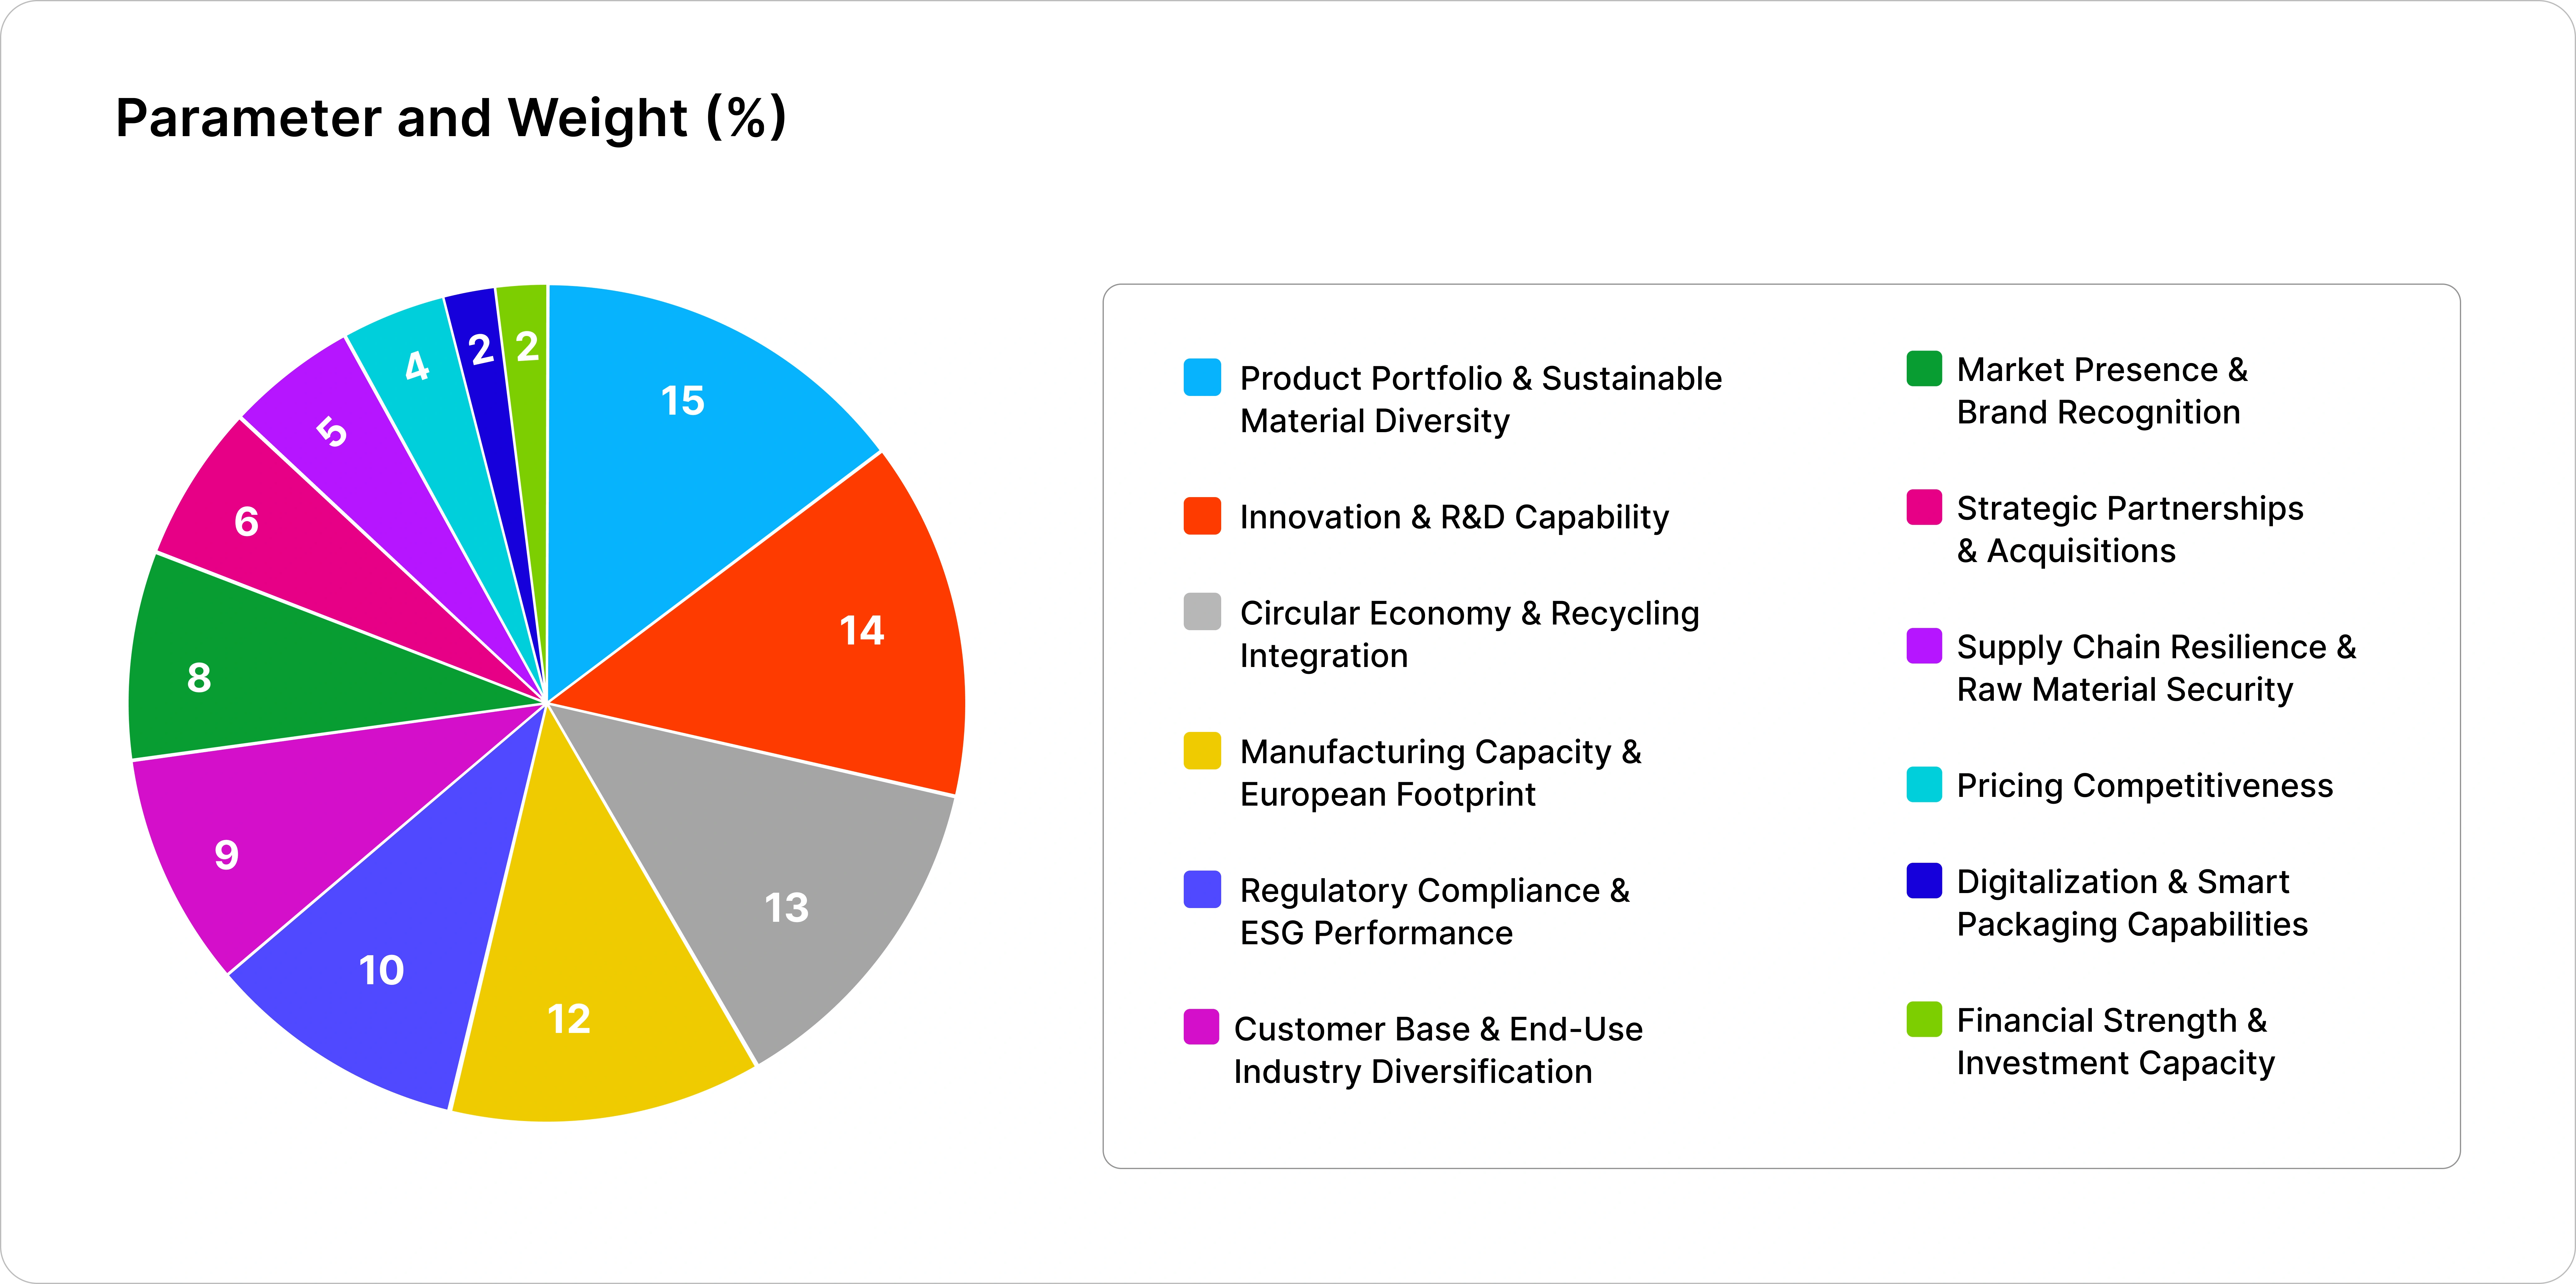
This framework examines manufacturers across various dimensions, including the diversity of their product portfolios, their manufacturing footprint, integration of recycling practices, readiness for the circular economy, research and development capabilities, environmental, social, and governance (ESG) performance, market penetration, pricing strategies, and strategic partnerships. Companies that boast robust fiber-based packaging portfolios, advanced recycling capabilities, high levels of recycled content, and extensive manufacturing networks throughout Europe tend to receive higher competitive scores. This advantage stems from their agility in responding to changing regulatory requirements and evolving customer preferences.
Innovation plays a key role in the assessment, particularly in areas such as the commercialization of recyclable mono-material packaging, bio-based materials, lightweight designs, and digital traceability solutions, which include QR-enabled packaging and Digital Product Passports. Additionally, factors like supply chain resilience, investments in recycling infrastructure, and adherence to European sustainability standards are heavily considered, as they have a direct impact on future market positioning.
Financial stability and strategies for expansion such as acquisitions, capacity enhancements, and partnerships with fast-moving consumer goods (FMCG) companies and retailers also bolster a company's competitive standing. EICAF serves as a valuable tool for investors, packaging converters, raw material suppliers, and consumer goods manufacturers, helping them to identify market leaders, benchmark operational strengths, assess strategic risks, and pinpoint emerging growth opportunities.
By merging quantitative and qualitative indicators into a weighted scoring methodology, EICAF provides a standardized and transparent evaluation of competitive positioning within the European eco-friendly packaging market. This supports effective strategic planning, investment prioritization, partnership evaluations, and long-term business decision-making.

