Europe Aluminium Recycling Market: Building a Sustainable and Circular Aluminium Value Chain 2026
Analysis by Product Type (Post-Consumer Scrap, Pre-Consumer Scrap, Import Scrap), Application, Form and Sales Channel


Analysis by Product Type (Post-Consumer Scrap, Pre-Consumer Scrap, Import Scrap), Application, Form and Sales Channel
Europe Aluminium Recycling Market recorded a consumption volume of 8.56 million tons in 2025 and is estimated to reach a volume of 11.97 million tons by 2033 with a CAGR of 4.5% during the forecast period.
High volumes of aluminium scrap leaving Europe create an opportunity for domestic recyclers to capture more feedstock and convert it into secondary aluminium.
The Europe aluminium recycling market is facing a structural feedstock imbalance as substantial volumes of aluminium scrap continue to leave the region despite rising demand for secondary metal. European Aluminium reports that the EU exported approximately 1.3 million tonnes of aluminium scrap in 2024, with around 75% directed to Asia, representing a major leakage of secondary raw material that could otherwise support European recycling operations.
The scale of the opportunity becomes clearer when export growth is compared with domestic recycling intake. Between 2019 and 2024, EU aluminium scrap exports increased 53%, while domestic scrap intake by European recyclers increased only 7%, indicating that additional scrap generation is not translating proportionately into European recycling supply. This divergence creates a potential feedstock constraint for recyclers and downstream manufacturers seeking greater recycled content.
At the same time, European companies have invested approximately €700 million in new recycling facilities, capacity expansions and process upgrades, creating additional processing capability that could benefit from greater domestic scrap availability. The strategic value of retaining scrap is reinforced by the energy advantage of secondary aluminium. Recycling aluminium requires only around 5% of the energy needed for primary production, while recycled aluminium can generate up to 95% fewer CO₂ emissions than primary aluminium, strengthening its relevance to European decarbonisation strategies.
Consequently, retaining even a portion of exported scrap could simultaneously improve recycler feedstock security, increase secondary aluminium output and reduce dependence on imported primary metal. The policy environment is also becoming more supportive, with the European Commission conducting work on trade measures intended to improve aluminium scrap availability within the EU. For recyclers, the opportunity therefore extends beyond simply increasing collection volumes: investment in sorting, alloy separation, pre treatment and remelting capacity could allow Europe to capture more of the value currently leaving the region. However, the commercial opportunity will depend on whether policy measures can reduce export leakage without creating excessive market distortion, while recyclers remain competitive against overseas buyers offering higher scrap prices.
Recycler margins can be squeezed when scrap prices rise faster than secondary aluminium selling prices, particularly for operators without long term supply contracts.
The Europe aluminium recycling market is experiencing increasing margin pressure because recyclers are facing a difficult combination of elevated scrap costs, constrained feedstock availability and uneven downstream demand. In Q1 2026, European extrusion grade scrap averaged 104% of LME aluminium prices, while the average aluminium billet premium increased to US$565 per tonne, up from US$440 per tonne in Q4 2025. At the same time, European secondary scrap prices increased 9% quarter on quarter, while DIN226 recycled foundry alloy prices rose 7.8%, demonstrating how quickly input costs can move when scrap availability tightens.
The margin issue becomes more pronounced when recyclers cannot immediately transfer higher scrap acquisition costs to customers through secondary aluminium selling prices. Hydro specifically reported that weak downstream aluminium demand combined with elevated scrap prices continued to pressure European recycling margins during Q1 2026. This creates a significant disadvantage for recyclers purchasing scrap on short term or spot arrangements, because their cost base can reset faster than customer contracts.
The situation is also linked to international competition for European scrap. EU aluminium scrap exports reached approximately 1.3 million tonnes in 2024, while European recyclers are competing against overseas buyers operating with different labour, energy, environmental and policy cost structures. European Aluminium notes that scrap prices had reached approximately 94% of primary aluminium prices on LME, illustrating how little pricing headroom can remain between feedstock acquisition and finished recycled metal value.
For recyclers, long term supplier agreements therefore become strategically important because they can improve feedstock visibility and reduce exposure to sudden procurement spikes. However, locking in supply does not eliminate margin risk if downstream aluminium prices weaken. The stronger operators are consequently focusing on yield improvement, alloy sorting, processing efficiency and cost reduction rather than relying solely on higher selling prices. Hydro, for example, has targeted US$20 to US$30 per tonne of recycling cost reductions by 2030, highlighting how operational efficiency is becoming a direct competitive lever.
The Europe aluminium recycling market has a particularly strong decarbonisation advantage because secondary aluminium production requires only around 5% of the energy used for primary aluminium production, allowing recyclers to reduce emissions without changing the material itself. European Aluminium reports that remelting emissions in Europe declined by 22% between 2015 and 2021, demonstrating that improvements in recycling operations are already contributing to lower carbon intensity.
The carbon advantage becomes more significant when recycled aluminium substitutes primary metal produced in higher carbon intensity regions. The International Aluminium Institute estimates that recycled aluminium can deliver approximately 92.4% lower emissions in Europe when comparing primary aluminium cradle to gate emissions with recycling process emissions, although the comparison uses different system boundaries and therefore should not be interpreted as the complete product carbon footprint.
This distinction is important for the Europe aluminium recycling market, because the climate benefit depends not only on recycling volumes but also on the origin of displaced primary aluminium and the energy used during collection, sorting and remelting. European primary aluminium already has a relatively low carbon footprint of 6.3 kg CO₂e per kg in 2023, around 60% below the global average, meaning that replacing European primary production provides a smaller incremental carbon saving than displacing higher carbon imports. This creates a strong strategic case for retaining scrap within Europe and using it to replace carbon intensive imported metal.
The opportunity is particularly visible in beverage cans, where 580,000 tonnes of aluminium were recycled in the latest reported dataset, generating 5.4 million tonnes of CO₂e savings. European Aluminium also projects that recycling production could increase by approximately 70% by 2050, while greater circularity could reduce annual CO₂ emissions by up to 39 million tonnes compared with today. Consequently, the carbon reduction opportunity is increasingly shifting toward improving scrap collection, sorting quality and domestic processing capacity rather than simply expanding recycling volumes. For investors and recyclers, technologies that maximise metal recovery while reducing remelting energy and maintaining alloy quality could therefore deliver both environmental and commercial value.
The Europe aluminium recycling market is moving from volume based recovery toward technology driven separation because mixed end of life scrap increasingly contains multiple alloy families that cannot be economically separated through conventional remelting alone. The European Commission's RecAL initiative identifies alloy mixing as a major technical barrier because alloying elements are difficult to remove once incorporated, causing mixed scrap to be downcycled into lower value cast alloys rather than returned to high specification wrought products. This makes advanced sorting, dismantling, refining and digital identification strategically more important than simply adding furnace capacity.
Mechanical preparation and eddy current separation remain important for removing non ferrousmetals and preparing aluminium streams, but their commercial value increases when combined with alloy specific identification technologies. RecAL is developing 14 Circular Amplification Technologies, including solutions focused on improved scrap capture, separation, purification and circular reuse, with technologies being advanced toward TRL 6. Spectroscopic and sensor based systems can potentially distinguish alloy compositions before melting, reducing the impurity burden entering furnaces and improving the quality of secondary metal.
This is particularly relevant for automotive scrap, where the growing mix of structural alloys, cast alloys and electrification related components creates a more complex feedstock than traditional beverage can streams. The technology gap has a direct economic consequence: RecAL estimates that Europe could face 6 million tonnes of surplus scrap by 2030 and 18.3 million tonnes by 2050 if current technologies and alloy systems cannot absorb available material. Therefore, the strongest technology proposition for the Europe aluminium recycling market is not a single breakthrough machine but an integrated chain combining automated dismantling, sensor based sorting, alloy classification, refining and data driven material tracking.
Digitalisation is particularly valuable because linking scrap composition with downstream alloy requirements can enable recyclers to route different streams toward higher value applications instead of defaulting to downcycling. The benchmarking therefore needs to assess technologies on purity improvement, recovery yield, throughput, energy consumption, automation level, alloy flexibility and ability to produce specification grade secondary aluminium, rather than comparing equipment solely on processing capacity.
The Europe aluminium recycling market is projected to expand from USD 17,688 million in 2027 to USD 21,546 million by 2033, representing a 3.3% CAGR, but the growth profile differs substantially across countries and regions.

Germany remains the dominant market throughout the forecast period, increasing from USD 5,729 million in 2027 to USD 6,987 million in 2033. Its scale gives Germany a disproportionately important role in the European market, although its 3.4% CAGR indicates that future expansion is not dependent solely on the largest market. Scandinavia emerges as the fastest growing regional segment, with a 4.5% CAGR and an increase from USD 2,800 million to USD 3,645 million between 2027 and 2033. This represents approximately 30% growth and makes Scandinavia the clearest high growth opportunity within the dataset.
France and Rest of Europe also outperform the overall market, recording CAGRs of 3.6% and 3.7%, respectively. In contrast, the UK, Spain and Italy show comparatively slower expansion at 2.0%, 2.3% and 2.4%. The country distribution therefore suggests that market expansion is gradually shifting toward regions with stronger growth momentum rather than being concentrated exclusively in the largest established markets.
Another important feature is the temporary contraction expected in 2026, when total market value falls from USD 17,970 million in 2025 to USD 17,565 million, before returning to growth from 2027 onward. A second interruption appears in 2030, followed by a strong recovery in 2031 and 2032. Germany's market increases by approximately 22% between 2025 and 2032, while Scandinavia expands by nearly 30%, indicating a widening contribution from faster growing regions.
The Europe aluminium recycling market therefore presents a differentiated investment landscape, where Germany provides scale and revenue depth, while Scandinavia and Rest of Europe offer comparatively stronger growth trajectories. The combination of market size, forecast CAGR and absolute revenue expansion provides a more useful basis for identifying country level opportunities than market size alone.
Key companies analyzed within the Europe aluminium recycling market are:Hydro Aluminium, Novelis Inc.,
| Companies | Recycling Capacity (Tons)-Europe (2025) |
| Hydro Aluminium | 650,000 |
| Novelis Inc. | 490,000 |
| Constellium SE | 150,000 |
| Gränges AB | 250,000 |
| Trimet Aluminium | 200,000 |
| Stena Recycling | 100,000 |
For the Europe Aluminium Recycling Market, the EICAF evaluates competitors based on their ability to secure scrap, convert complex feedstock into specification grade secondary aluminium and capture value across the recycling chain.
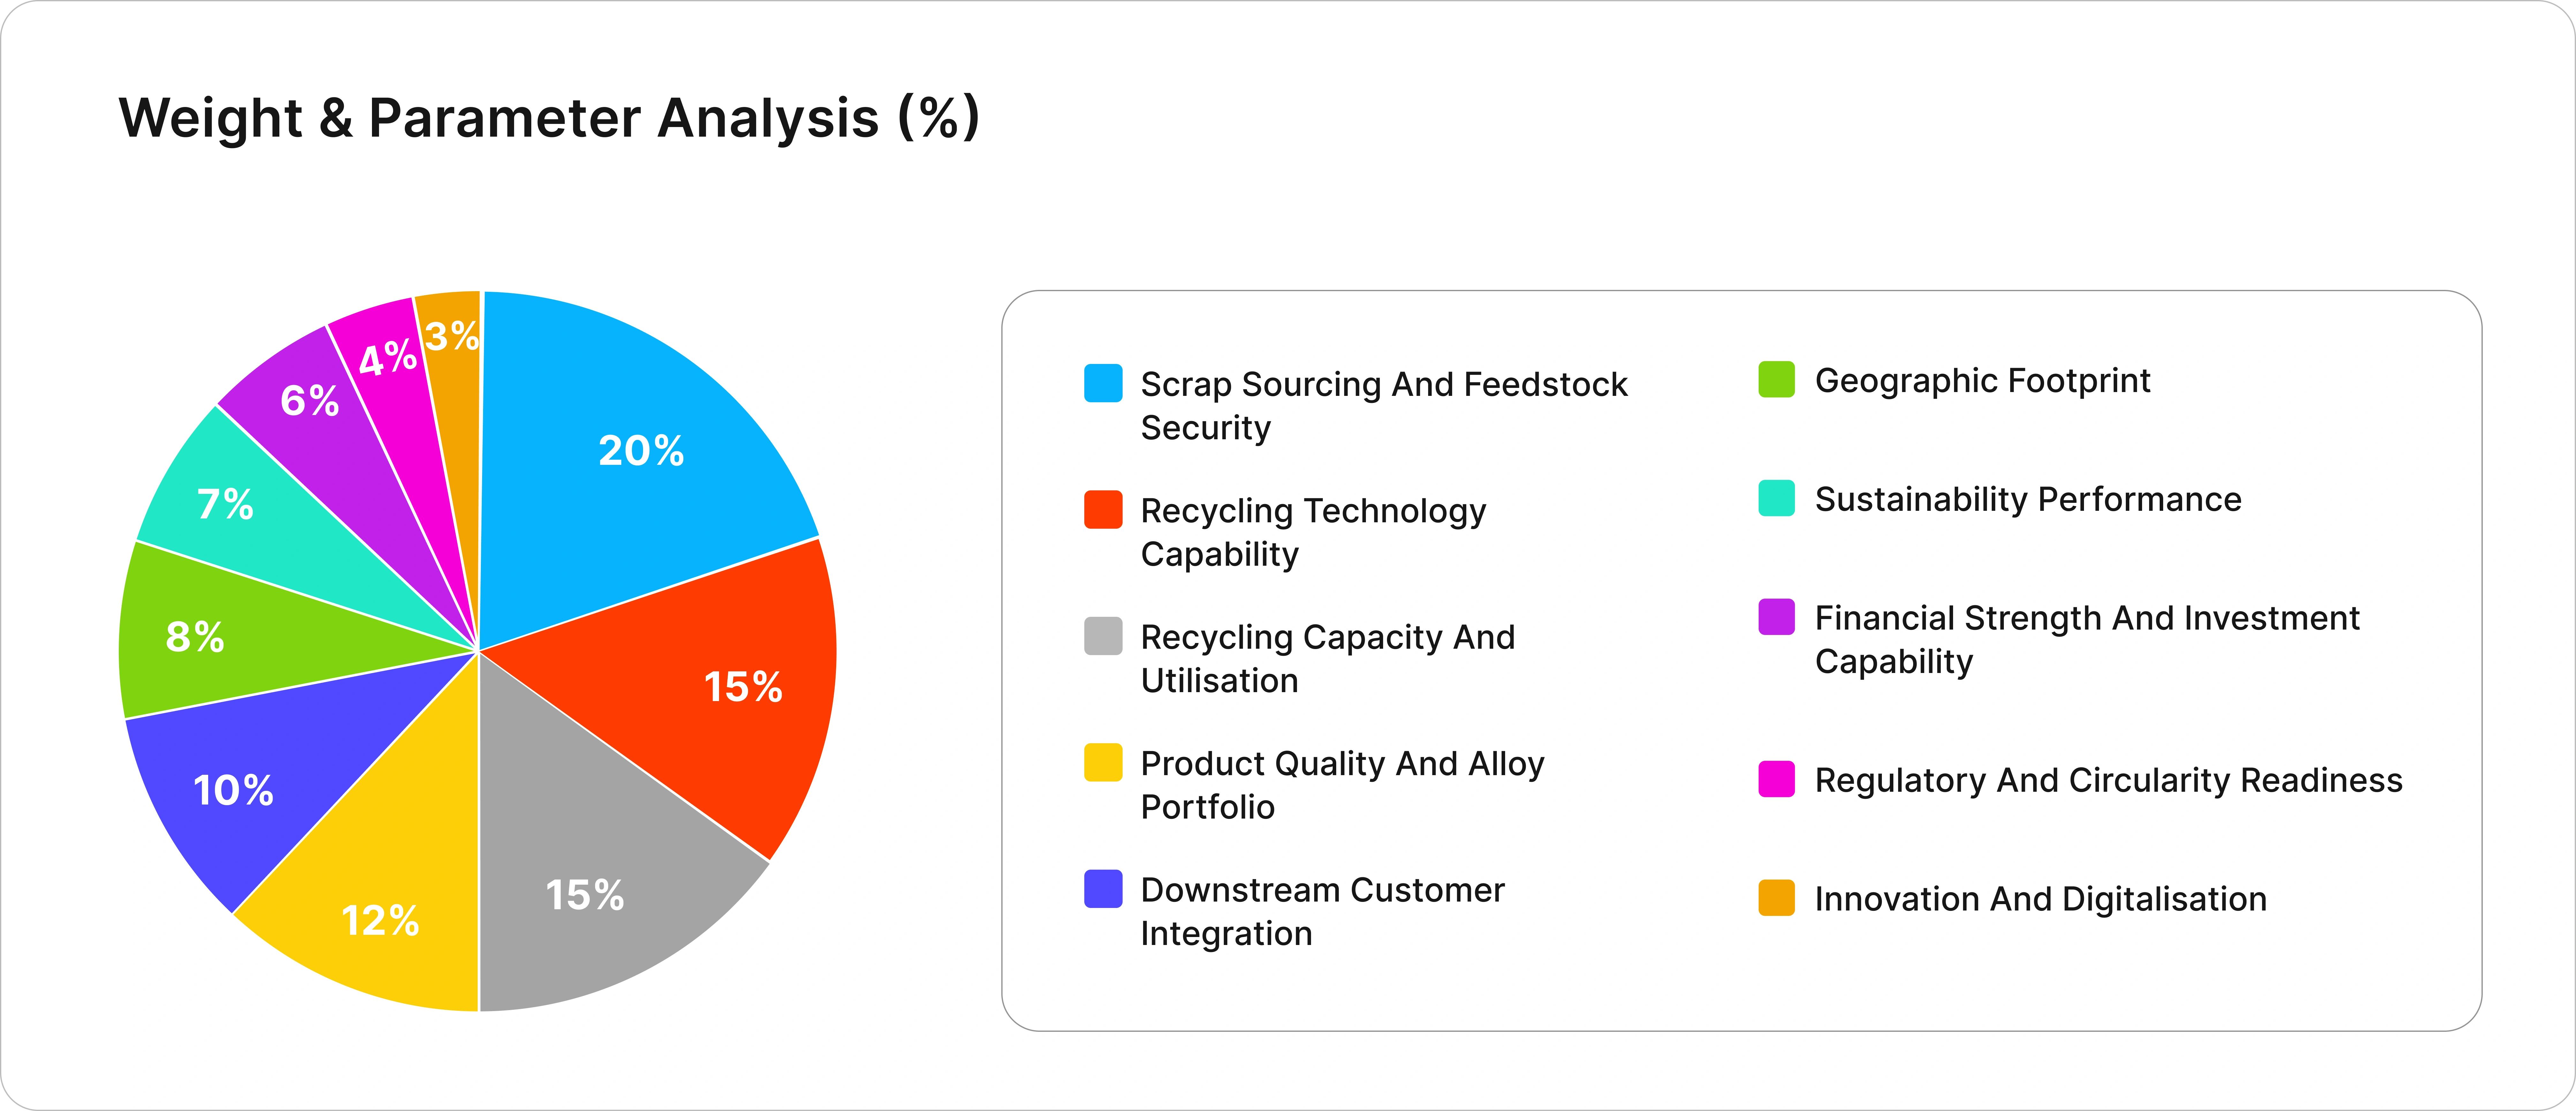
The framework gives the highest weight to scrap sourcing and feedstock security, as European recyclers are increasingly exposed to competition for available scrap and potential feedstock shortages. The European Commission's RecAL project estimates that unsuitable surplus aluminium scrap could reach 6 million tonnes by 2030, making advanced sorting and refining increasingly important. Technology capability therefore receives a substantial weighting, particularly for alloy identification, automated sorting, refining and impurity management. Recycling capacity and utilisation assess whether companies possess sufficient processing infrastructure and can maintain high throughput despite feedstock constraints. Product quality and alloy portfolio measure the ability to supply higher value wrought and automotive grades rather than relying on downcycling.
Downstream integration evaluates access to automotive, packaging and construction customers and the ability to establish closed loop supply arrangements. Sustainability performance considers carbon intensity, recycled content and energy efficiency, while financial strength captures investment capacity for plant expansion and technology upgrades. Regulatory readiness is also included because European policy is increasingly focused on retaining secondary resources and increasing circularity. The resulting score can distinguish companies with large recycling volumes from those possessing stronger technology, feedstock control and higher value product capabilities.