Key Findings
- The Asia Remote Patient Monitoring Market is projected to reach USD 7.6 billion by 2033, expanding at a CAGR of 14.0% during 2027–2033, driven by increasing digital healthcare adoption.
- Government reimbursement initiatives in Japan, South Korea, Singapore, and Australia are accelerating physician adoption and improving the commercial viability of RPM solutions.
- AI-enabled monitoring for cardiovascular diseases and diabetes represents the most mature and fastest-growing application segment due to high chronic disease prevalence and widespread wearable device adoption.
- China leads the regional IoT healthcare ecosystem, while Japan and South Korea remain technology leaders owing to advanced healthcare infrastructure and high digital health readiness.
- Wearable medical devices account for nearly 63% of connected healthcare devices, highlighting the transition from episodic hospital care to continuous home-based patient monitoring.
- Limited interoperability, fragmented reimbursement policies, and the absence of standardized clinical workflows remain the primary barriers to large-scale RPM implementation across Asia.
- Vendors offering integrated ecosystems comprising AI analytics, connected devices, cloud platforms, and EHR interoperability are expected to gain the strongest competitive advantage in the Asia Remote Patient Monitoring Market.
Asia Remote Patient Monitoring Market Outlook
Asia Remote Patient Monitoring Market recorded a value of USD 2.7 Billion in 2025 and is estimated to reach a value of USD 7.6 Billion by 2033 with a CAGR of 14.0% during the forecast period.
Asia Remote Patient Monitoring Market Outlook
Government reimbursement pilots for remote monitoring services in Japan, South Korea, Singapore, and Australia
Government reimbursement pilots in Japan, South Korea, Singapore, and Australia are emerging as key influencers in the Asia Remote Patient Monitoring Market, transitioning remote monitoring from a pilot-stage digital health initiative to a reimbursable clinical service. Japan, facing challenges due to its aging population where nearly 29% of citizens are 65 years or olderhas increased pressure on its healthcare systems to decrease hospital admissions and manage chronic diseases remotely. As part of its digital healthcare reforms, Japan is gradually expanding reimbursement for telemedicine and home-based monitoring, prompting hospitals to implement connected devices, such as ECG, blood pressure, and glucose monitors.
Similarly, South Korea's Digital Healthcare Act and national telemedicine pilot programs have accelerated the adoption of AI-enabled remote monitoring. This progress benefits from the country's high 5G penetration rate, exceeding 45% of mobile subscriptions, which facilitates continuous transmission of extensive patient data. In Singapore, the Healthier SG initiative promotes preventive and community-based care, creating opportunities for integrating remote patient monitoring solutions with primary care providers. Singapore's internet penetration is above 95%, supporting widespread digital health adoption.
Australia has emerged as a significant growth driver through the Medicare Benefits Schedule (MBS), which reimburses certain telehealth consultations and chronic disease management services. This system particularly benefits patients in geographically remote areas with limited access to specialists. By reducing financial uncertainty around remote monitoring deployment, these reimbursement mechanisms enhance provider return on investment and encourage increased physician participation.
The economic advantages are significant; studies indicate that remote patient monitoring can reduce hospital readmissions for chronic cardiovascular and respiratory conditions by 15–25% among appropriate patient populations while lowering overall healthcare utilization costs. As Asian governments increasingly prioritize value-based healthcare, preventive medicine, and decentralized care delivery, reimbursement frameworks are anticipated to expand beyond teleconsultations.
They are likely to include continuous physiological monitoring, AI-assisted clinical decision support, and home-based chronic disease management.
Therefore, evolving reimbursement policies are establishing sustainable commercial opportunities for device manufacturers, digital health platforms, and healthcare providers. This policy support is positioned as a crucial growth driver for the Asia Remote Patient Monitoring Market throughout the forecast period.
Lack of standardized clinical protocols for integrating RPM data into physician workflows
One of the most significant barriers to the scalability of the Asia Remote Patient Monitoring (RPM) Market is the absence of standardized clinical protocols for integrating RPM data into routine physician workflows. Despite the rapid adoption of connected medical devices, wearable sensors, and cloud-based monitoring platforms across hospitals in Asia, considerable variability remains in how clinicians interpret alerts, determine intervention thresholds, and incorporate continuously generated patient data into electronic health records (EHRs).
For instance, a patient with hypertension may generate hundreds of blood pressure readings each month; however, many healthcare systems lack evidence-based protocols that define which readings necessitate immediate intervention, follow-up consultations, or medication adjustments. This inconsistency often leads to "alert fatigue," with studies suggesting that 80–90% of clinical alarms in healthcare settings may be non-actionable, ultimately diminishing physician responsiveness to genuinely critical situations.
The challenge is particularly pronounced in Asia, where healthcare delivery models, reimbursement systems, and digital infrastructure vary significantly between countries such as Japan, India, Indonesia, and Vietnam, complicating efforts for regional standardization. Although advanced healthcare markets like Singapore, South Korea, and Australia have made strides in integrating RPM platforms with hospital information systems, issues with interoperability persist due to the presence of multiple electronic medical record vendors and proprietary device ecosystems.
Furthermore, many RPM solutions transmit physiological data without incorporating standardized clinical decision support algorithms, which requires physicians to manually sift through substantial amounts of information, thereby increasing consultation times. The lack of harmonized guidelines also hampers physician training, regulatory approvals, and reimbursement decisions, as healthcare providers struggle to demonstrate consistent clinical outcomes across diverse patient populations.
As the global number of connected medical devices is projected to exceed 30 billion across various industries by the end of the decade, with healthcare being one of the fastest-growing segments, the volume of patient-generated health data is set to surge. Without the establishment of standardized workflows, interoperable data formats, and clinically validated escalation protocols, healthcare providers may face reduced operational efficiency despite heightened digitalization.
Therefore, addressing workflow standardization is vital for unlocking the full clinical and commercial potential of the Asia Remote Patient Monitoring Market, ensuring that continuous patient monitoring translates into tangible improvements in care quality, physician productivity, and patient outcomes.
Asia Remote Patient Monitoring Market: AI-Based Disease Monitoring Adoption Matrix
The AI-Based Disease Monitoring Adoption Matrix reveals noteworthy differences in the maturity of artificial intelligence implementation across various disease categories. These variations are influenced by factors such as clinical demand, availability of data, reimbursement support, and the state of digital infrastructure within the Asia Remote Patient Monitoring Market.
Currently, cardiovascular diseases and diabetes are leading the way in AI adoption due to their significant patient populations and the consistent generation of physiological data that is conducive to machine learning algorithms. Asia houses over 60% of the global diabetes population, with more than 290 million adults affected by the condition. This reality has made continuous glucose monitoring (CGM) and AI-enhanced insulin optimization two of the fastest-growing applications in remote patient monitoring.
Cardiovascular diseases also account for a substantial number of deaths in many Asian countries, fueling the widespread use of AI technologies for ECG interpretation, arrhythmia detection, and heart failure prediction. These platforms are capable of identifying early signs of clinical deterioration, potentially preventing the need for hospitalization.
In addition, the monitoring of respiratory diseases is gaining momentum as wearable pulse oximeters and connected spirometry devices become integrated into management programs for chronic obstructive pulmonary disease (COPD) and asthma. However, other areas such as neurological disorders, chronic kidney disease, oncology, and maternal health remain in the medium-adoption phase. This slower progress is due to the ongoing evolution of clinical validation studies, reimbursement mechanisms, and standardized monitoring protocols.
Mental health monitoring currently exhibits the lowest level of AI penetration, despite its significant growth potential. This is largely attributed to concerns over privacy, fragmented regulatory frameworks, and the limited acceptance of AI-supported behavioral analytics within clinical practices.
Country-specific dynamics also play a crucial role in shaping adoption trends. Nations like Japan, South Korea, Singapore, and Australia enjoy advantages such as advanced electronic health record integration, high broadband connectivity, and supportive digital health policies. In contrast, emerging economies are still focused on enhancing infrastructure and ensuring that connected devices are affordable.
A key hallmark of the Asia Remote Patient Monitoring Market is the growing convergence of wearable sensors, cloud computing, and predictive analytics. This integration is enabling healthcare providers to shift from reactive treatment approaches to more preventive, data-driven disease management strategies. As AI algorithms continue to enhance diagnostic accuracy and minimize false-positive alerts, disease categories with moderate adoption such as oncology, post-operative recovery, and neurological care are anticipated to see accelerated commercialization. This shift is expected to create new opportunities for device manufacturers, digital health platforms, hospitals, and healthcare investors across the region in the coming decade.
Asia Remote Patient Monitoring Market: RPM Adoption Heat Map Across Asian Countries
The RPM Adoption Heat Map across Asian countries reveals that the uptake of remote patient monitoring is closely linked to several factors, including the digitalization of healthcare, the maturity of reimbursement systems, broadband connectivity, aging populations, and government investments in digital health infrastructure, rather than just the size of the population.
In this landscape, Japan leads in adoption due to its rapidly aging demographic, where nearly 29% of its citizens are 65 years or older. This is further bolstered by well-established telemedicine reimbursement policies and the widespread availability of home-based chronic disease management solutions. Following Japan, South Korea is notable for its highly advanced digital healthcare system, including 5G coverage that exceeds 95% of the population, which enables real-time transmission of data from connected medical devices.
Singapore also ranks high on the adoption scale, driven by the national Healthier SG initiative, with internet penetration exceeding 95% and extensive integration of electronic medical records across healthcare providers. Australia is categorized as a high-adoption country, thanks to Medicare-supported telehealth services, robust rural healthcare initiatives, and advanced hospital information systems that facilitate the use of RPM solutions for managing cardiovascular diseases, diabetes, and post-discharge care.
China shows significant growth potential despite uneven regional adoption. The nation is making large-scale investments in AI healthcare, the development of smart hospitals, and the expansion of digital health platforms beyond Tier-1 cities. In India, the Ayushman Bharat Digital Mission and rapidly increasing smartphone usage support medium-level adoption, although challenges remain due to inconsistent reimbursement frameworks, fragmented healthcare infrastructure, and disparities between urban and rural healthcare facilities.
Southeast Asian nations such as Malaysia, Thailand, and Vietnam are moving from pilot implementations toward broader commercialization. This transition is driven by the rising prevalence of chronic diseases, increasing private healthcare investments, and improving cloud connectivity. Conversely, countries like Indonesia and the Philippines are still emerging markets for RPM, facing challenges related to digital infrastructure, affordability, and physician adoption that limit market penetration, even though demand is substantial in the long term.
Overall, the Asia Remote Patient Monitoring Market showcases a distinct geographic adoption gradient. Countries with mature digital health policies, interoperable electronic health records, and supportive reimbursement ecosystems consistently outperform those that depend largely on out-of-pocket healthcare expenditures. This highlights that policy readiness and healthcare digitalization are the strongest factors influencing RPM adoption across the region.
Asia Remote Patient Monitoring Market: Connected Medical Device Penetration Analysis
The infographic illustrates a significant convergence between the expansion of IoT healthcare, the adoption of wearable devices, and the growth of remote patient monitoring (RPM) in the Asia region. It highlights the key factors driving the rapid growth of the Asia Remote Patient Monitoring Market. China is positioned as the regional leader, with projections indicating an IoT healthcare market exceeding USD 42 billion by 2025. This figure substantially surpasses that of Japan, estimated at around USD 27 billion, and India, which is projected to reach approximately USD 22 billion. China's preeminence is supported by extensive investments in smart hospitals, AI-driven diagnostic platforms, and a vast ecosystem of connected medical devices, facilitating the swift commercialization of cloud-based patient monitoring solutions.
Japan’s noteworthy IoT healthcare market reflects its aging population, with nearly 29% of its demographic aged 65 and older, which fuels demand for continuous monitoring of chronic conditions such as cardiovascular diseases, diabetes, and respiratory disorders. Conversely, while India's market is smaller, it is recognized as one of the fastest-growing segments, bolstered by advances in digital health infrastructure, over 75% smartphone penetration among internet users, and the Ayushman Bharat Digital Mission, which enhances access to connected healthcare services.
Additionally, the infographic emphasizes that wearable devices will account for 62.9% of connected healthcare devices by 2025, signaling a shift from traditional hospital-centric monitoring to user-friendly medical wearables. These devices will enable continuous monitoring of vital signs like heart rhythm, blood glucose levels, oxygen saturation, sleep quality, and physical activity. RPM applications are projected to constitute 37.5% of all connected healthcare device usage, underscoring a trend towards ongoing patient management rather than episodic diagnoses. This shift reflects a growing focus among healthcare providers on reducing hospital readmissions and facilitating proactive care through AI-driven analytics.
Furthermore, the Asia-Pacific IoT healthcare sector is set to grow at a projected compound annual growth rate (CAGR) of 27.9% from 2025 to 2035, underscoring the strong technological foundation supporting RPM adoption. As advancements in 5G connectivity, cloud computing, edge AI, and interoperable digital health platforms continue to be integrated into clinical workflows, the Asia Remote Patient Monitoring Market is poised to benefit from both increasing healthcare digitization and the rapid development of connected medical infrastructure. This creates significant long-term prospects for device manufacturers, software developers, healthcare providers, and digital health platform companies aiming to leverage the region's shift towards continuous, data-driven patient care.
Competitive Analysis
Key companies analyzed within the Asia remote patient monitoring market are: Medtronic plc, Koninklijke Philips N.V., GE HealthCare Technologies Inc., Abbott Laboratories, Siemens Healthineers AG, Baxter International Inc., OMRON Healthcare Co., Ltd., DexCom, Inc., Masimo Corporation, ResMed Inc., Nihon Kohden Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Huawei Technologies Co., Ltd., Biofourmis, Dozee, AliveCor, Inc., iRhythm Technologies, Inc., Tricog Health, Yuwell Medical, Terumo Corporation, Others.
Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) assesses companies in the Asia Remote Patient Monitoring Market by examining their competitive capabilities in technology, commercialization, clinical integration, and ecosystem development, rather than merely focusing on product diversity. In the current market environment, AI and predictive analytics capabilities are weighted most heavily at 18%, signaling that healthcare providers increasingly prioritize platforms that can detect patient deterioration before severe clinical symptoms manifest. AI-driven remote patient monitoring (RPM) solutions have shown the ability to decrease avoidable hospital readmissions by 15–25% for certain chronic disease groups, while also enhancing clinical decision-making through automated risk stratification.
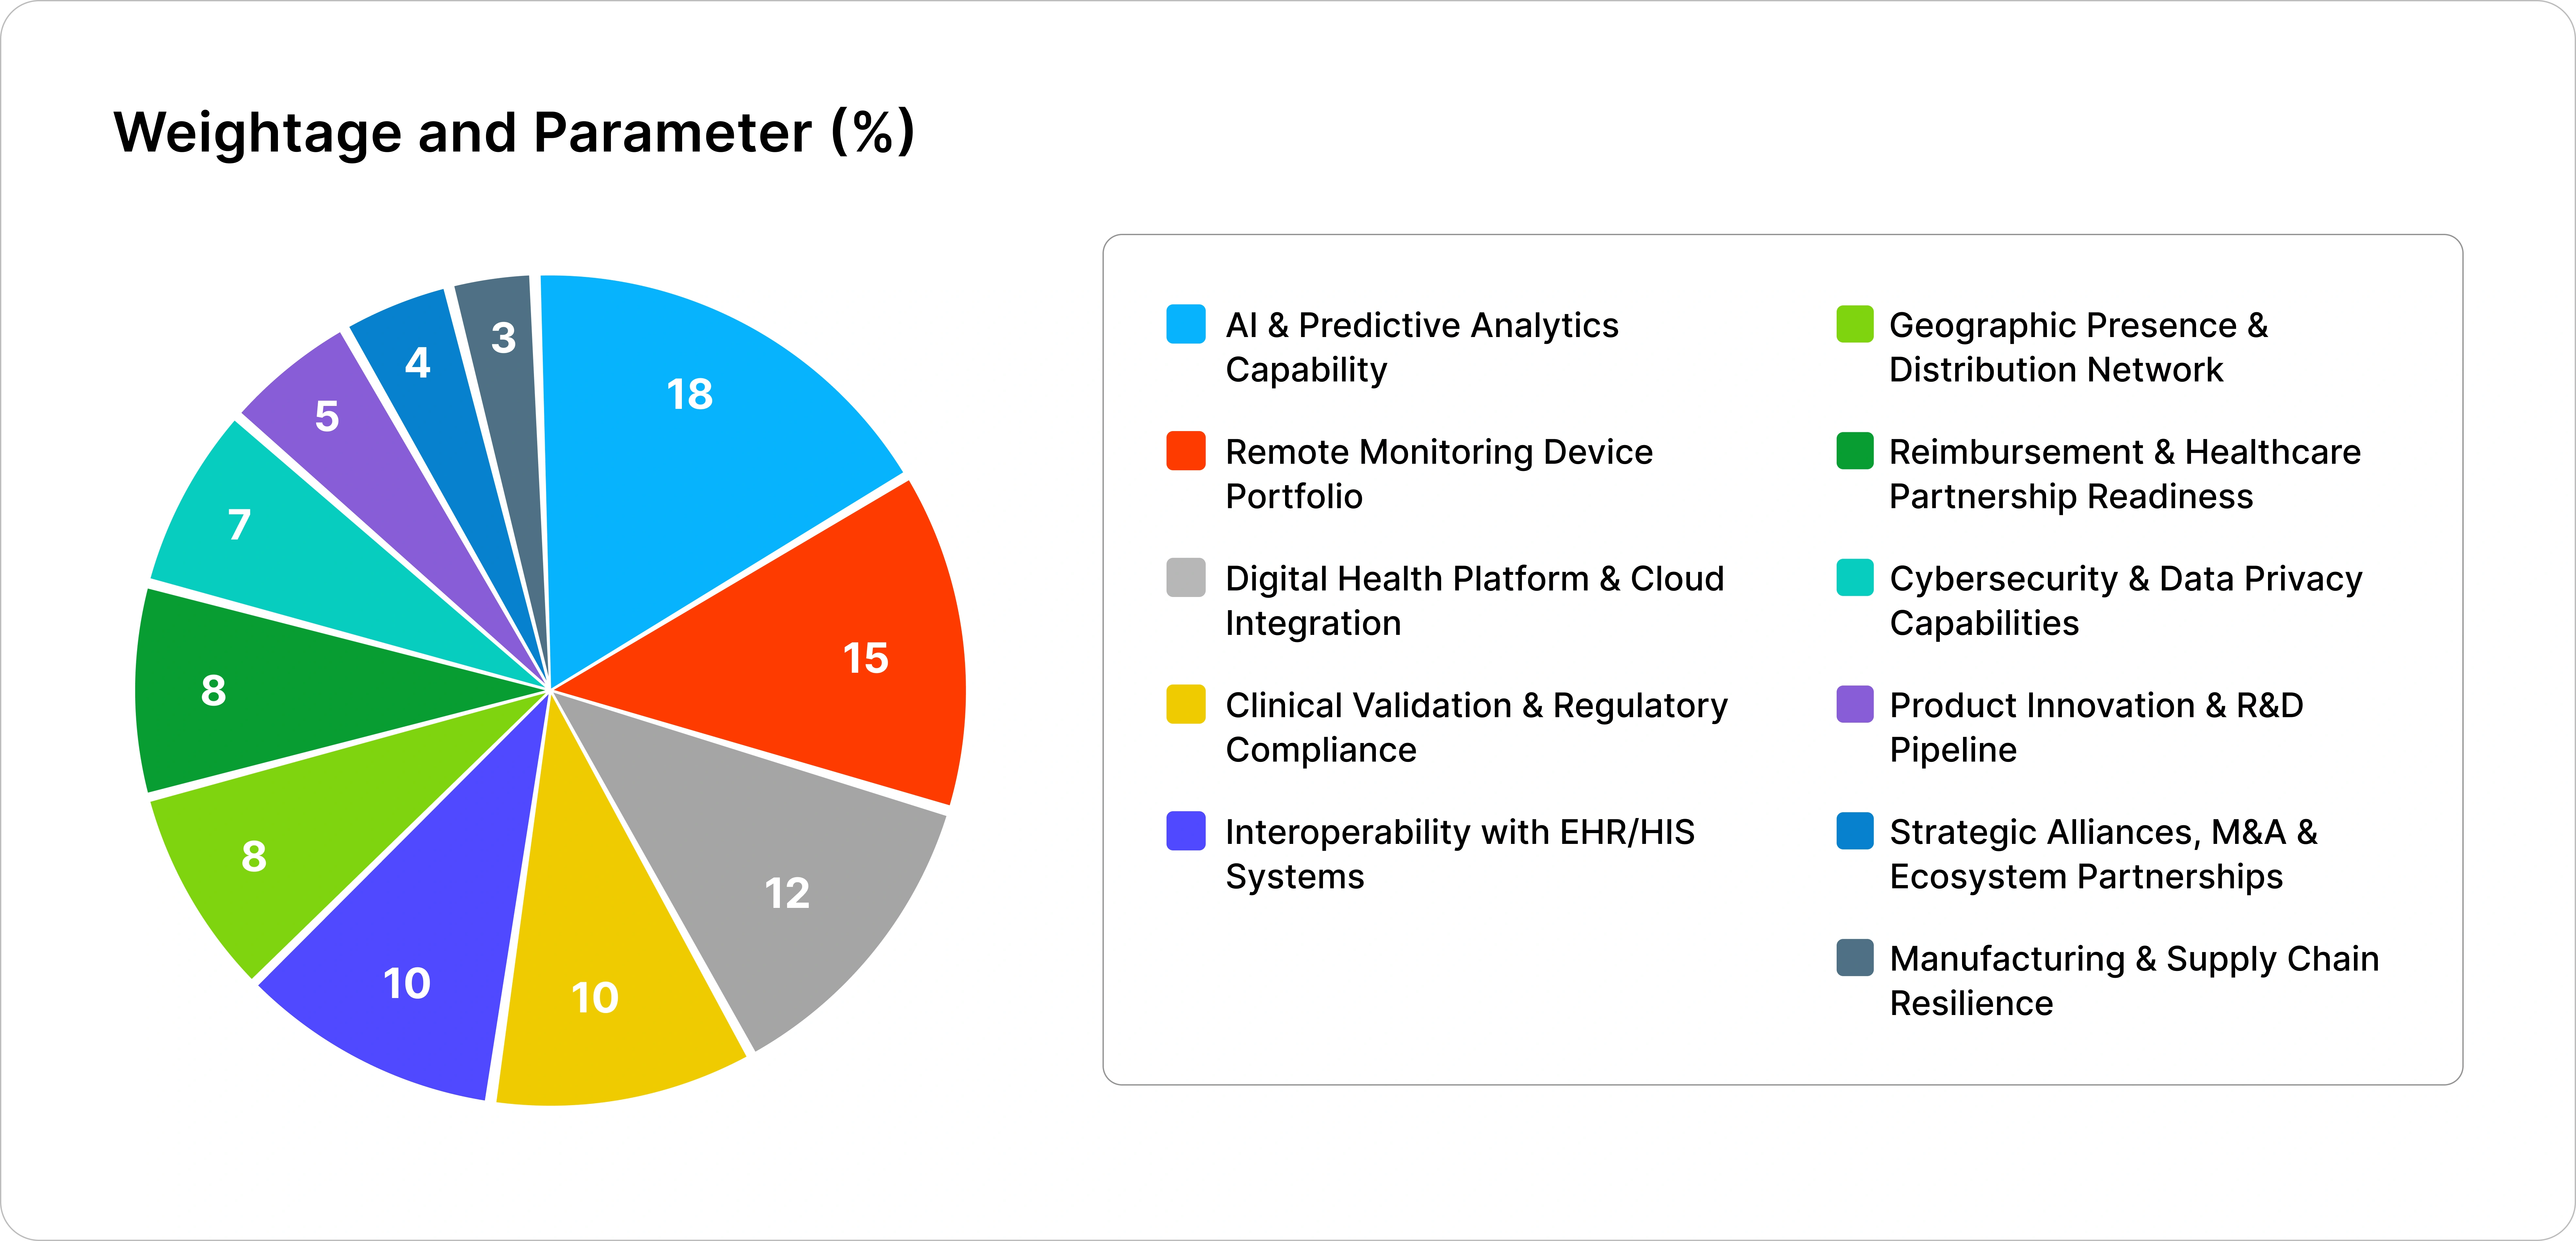
The second-highest weight of 15% is assigned to the remote monitoring device portfolio, highlighting the critical need for a range of clinically validated devices for conditions such as cardiovascular disease, diabetes, respiratory disorders, hypertension, and post-operative care, which collectively represent the majority of RPM implementations across Asia. The integration of digital health platforms (12%) and interoperability with electronic health records (10%) are key differentiators, as hospitals demand seamless connections with their existing Hospital Information Systems (HIS), FHIR-enabled electronic health records, and cloud-based clinical workflows instead of standalone monitoring solutions.
Clinical validation and regulatory compliance are vital, receiving a 10% weight, due to the varying approval timelines and evidence requirements across different countries including Japan, South Korea, China, Singapore, and India. Reimbursement readiness, which accounts for 8%, is also a significant competitive factor; countries with established reimbursement pathways tend to see quicker provider adoption and better long-term revenue visibility.
Furthermore, cybersecurity, weighing in at 7%, has become increasingly important due to the swift growth of connected medical devices and the expanding cross-border exchange of health data. Strategic partnerships with hospitals, insurers, telecommunications providers, and AI software developers play a crucial role in enhancing commercialization and are specifically considered within the framework. Lastly, manufacturing resilience and pricing competitiveness are key influences on procurement decisions, particularly in emerging Asian economies where affordability is a major purchasing factor.
By applying weighted importance to these strategic capabilities, the Epignosis Insights Competitive Assessment Framework (EICAF) provides investors, healthcare providers, and technology vendors with the tools to objectively evaluate competitive positioning within the Asia Remote Patient Monitoring Market, identify areas for improvement, and prioritize investment opportunities in a swiftly advancing digital healthcare landscape.

