U.S. Protein Ingredients Market Manufacturing Capacity and Investment Analysis 2024-2033
Analysis by Source, Product Type (Protein Concentrates, Protein Isolates, Protein Hydrolysates, Protein Texturates (TVP/TMP), Protein Blends) and Application


Analysis by Source, Product Type (Protein Concentrates, Protein Isolates, Protein Hydrolysates, Protein Texturates (TVP/TMP), Protein Blends) and Application
U.S. Protein Ingredients Market recorded a volume sales of 4.67 million tons in 2025 and is estimated to reach a volume of 6.90 million tons by 2033 with a CAGR of 6.0% during the forecast period.
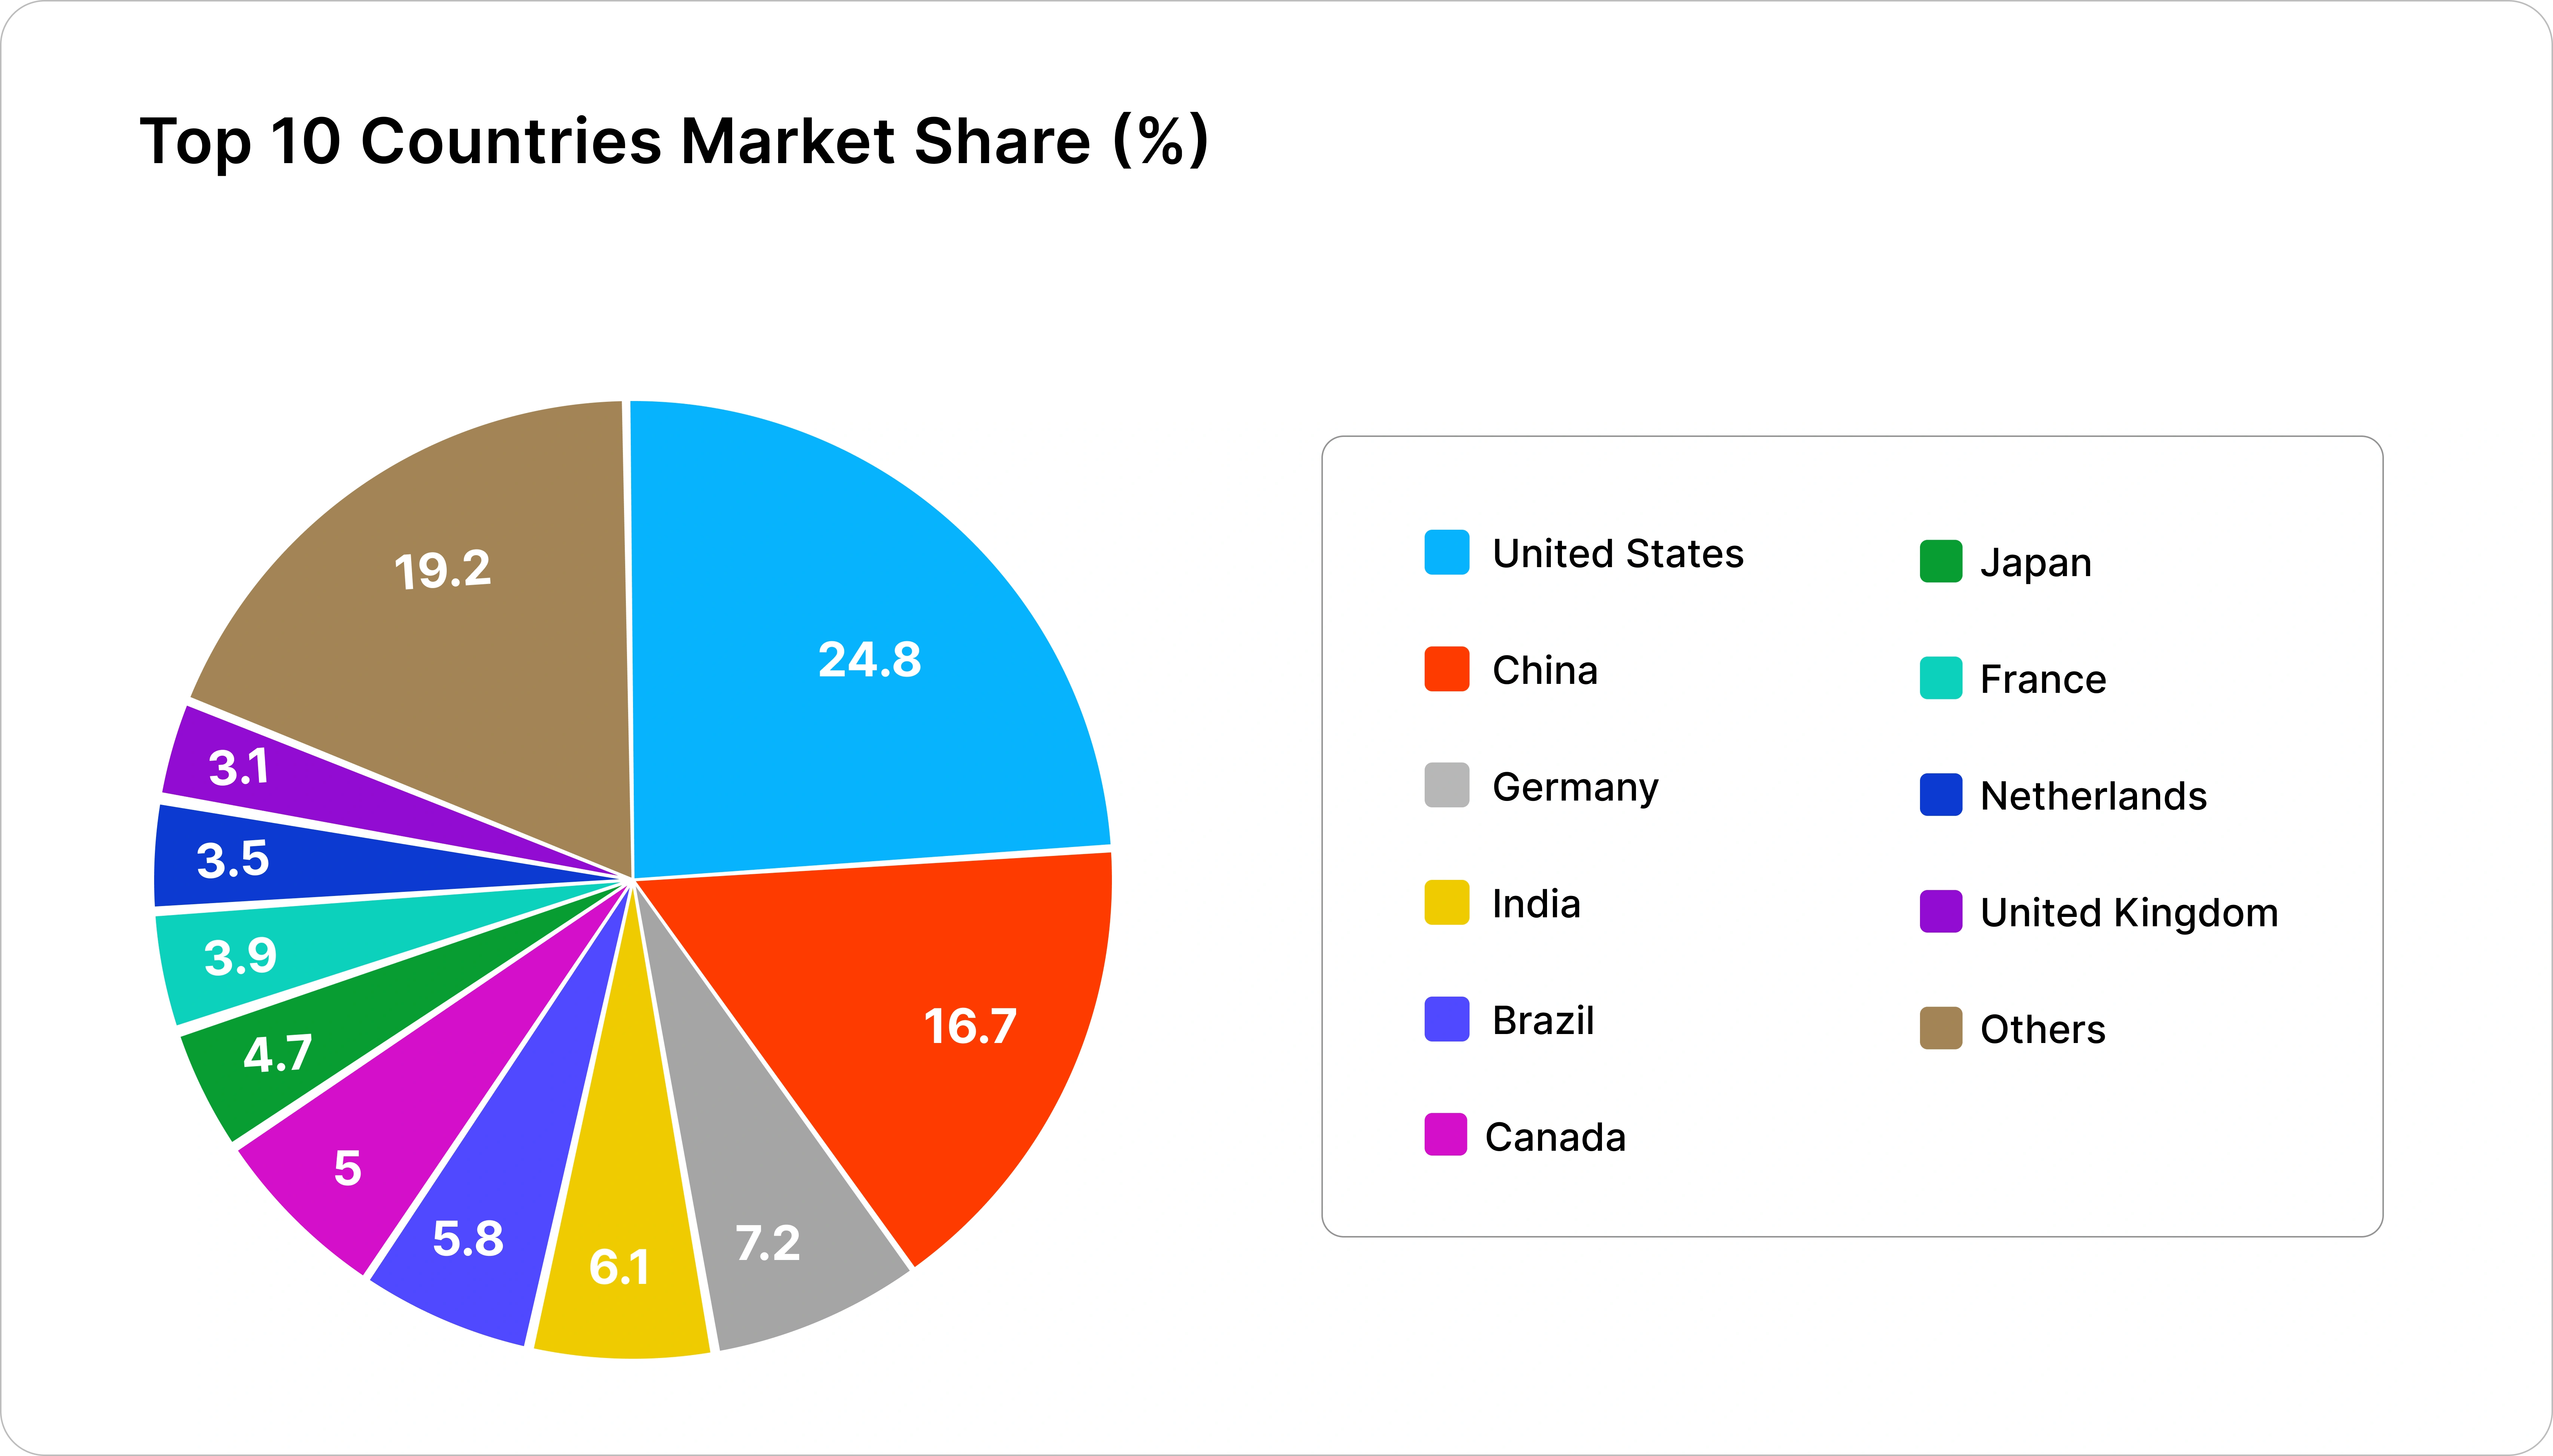
Global demand for protein ingredients reached 18.9 million tons in 2025 and is projected to increase to 28.9 million tons by 2033, registering a CAGR of 6.5% during the forecast period. Below figure depicts the top 10 countries within the global protein ingredients market:
Expansion of Domestic Pea Protein Processing Capacity
The expansion of domestic pea protein processing capacity is becoming a significant catalyst for growth in the U.S. protein ingredients market. This development not only bolsters supply chain resilience but also reduces dependence on imported plant protein ingredients. Currently, the United States ranks as one of the largest producers of dry peas, with annual harvests estimated at approximately 0.8 to 1.0 million metric tons, predominantly sourced from North Dakota, Montana, Washington, and Idaho.
The rise in yellow pea cultivation has prompted considerable investment in facilities designed for protein extraction and fractionation, allowing for the production of high-purity pea protein isolates and concentrates tailored for food and beverage applications. Key players in the industry, including ADM, Cargill, Ingredion, and PURIS, are ramping up their processing capabilities in response to increased demand from manufacturers of plant-based meat alternatives, dairy substitutes, sports nutrition products, and high-protein snacks.
Furthermore, domestic processing contributes to shorter procurement lead times, reduced transportation costs, and a lesser vulnerability to global trade disruptions and freight volatility. Innovations in dry fractionation, membrane filtration, and air classification technologies have enhanced protein recovery rates while lessening water and energy consumption compared to traditional wet processing techniques. This shift towards domestic production is proving to be more cost-effective and environmentally friendly.
There is also a growing preference among U.S. food manufacturers for locally sourced ingredients, which further encourages investments in regional processing infrastructure. As consumer interest shifts towards products with transparent and traceable supply chains, this preference is becoming increasingly important. Additionally, domestic pea protein production offers formulators a non-allergenic alternative to soy protein, facilitating clean-label product development and opening up opportunities in allergen-sensitive food categories.
The availability of locally processed pea protein is fostering innovation in sectors such as protein-fortified beverages, bakery items, ready-to-eat meals, and nutritional supplements. This ensures a consistent supply of functional ingredients with enhanced solubility and sensory attributes. As investments in processing technology, capacity expansion, and agricultural partnerships continue to grow, domestic pea protein production is anticipated to become an even more strategic element in the U.S. protein ingredients market, enhancing competitiveness while supporting the nation's shift towards a diversified and sustainable supply chain for protein ingredients.
Limited Consumer Acceptance of Fermentation-Derived Proteins
The limited consumer acceptance of fermentation-derived proteins presents a significant challenge for the U.S. protein ingredients market, despite the rapid advancements in technology and increasing investments in precision fermentation platforms. These proteins, which include dairy proteins, egg proteins, and microbial proteins produced without traditional livestock farming, provide notable environmental and functional benefits. However, their widespread commercialization is hindered by consumer perceptions and trust issues.
Consumer Perception Index (Analyst Estimate)
Surveys across the U.S. food sector reveal that a considerable number of consumers are unfamiliar with precision fermentation and often mistakenly conflate it with genetically modified organisms (GMOs), synthetic ingredients, or lab-grown meat. This confusion contributes to hesitance in purchasing products containing these proteins. Acceptance tends to be higher among younger consumers and early adopters but significantly declines in older demographics, who tend to prioritize familiarity and natural food claims.
Food manufacturers encounter difficulties in effectively communicating the safety, nutritional equivalence, and production processes behind fermentation-derived ingredients, often fearing the use of overly technical terminology may overwhelm consumers. Although the U.S. Food and Drug Administration has granted Generally Recognized as Safe (GRAS) status to several precision-fermented proteins, achieving broader market adoption necessitates transparent labeling, consumer education, and greater retail visibility.
Cost also remains a barrier since fermentation-derived proteins generally come at a premium compared to conventional whey, soy, or pea proteins, owing to high capital expenditures required for bioreactors, downstream purification, and specialized manufacturing infrastructure. However, investments in commercial-scale fermentation facilities, process optimization, and strain engineering are anticipated to enhance production efficiency and reduce unit costs over time.
Food manufacturers are increasingly incorporating fermentation-derived proteins into high-value applications such as premium dairy alternatives, nutrition beverages, and functional foods before targeting mass-market products. As awareness grows and economies of scale help lower production costs, consumer confidence is expected to rise, facilitating broader commercialization. To unlock the long-term growth potential of fermentation-derived proteins in the U.S. protein ingredients market, it will be essential to overcome perception barriers through scientific communication, regulatory transparency, and product familiarity.
The U.S. dairy industry serves as a foundational pillar in the protein ingredients market, acting as the primary source of high-value whey proteins, casein, milk protein concentrates (MPC), and milk protein isolates (MPI). These ingredients are essential across various sectors, including sports nutrition, functional foods, infant formula, and clinical nutrition. In 2024, the United States produced approximately 226 billion pounds (102.5 million metric tons) of milk, reinforcing its status as one of the world’s largest milk producers and providing a stable base for dairy protein manufacturing.
Cheese production, which surpassed 14 billion pounds annually, plays a vital role since whey protein is produced as a co-product during cheese processing. This establishes a direct connection between cheese output and the availability of whey ingredients. The increasing demand for high-protein ready-to-drink beverages, yogurt, meal replacement products, and medical nutrition has prompted dairy processors to invest in advanced membrane filtration, ultrafiltration, and microfiltration technologies. These investments enhance protein purity and improve functional properties such as solubility, heat stability, and emulsification.
Furthermore, major dairy cooperatives and processors have expanded their production of specialty proteins designed for clean-label formulations, high-protein snacks, and nutrition targeted at aging populations. This expansion allows food manufacturers to create premium products with superior amino acid profiles. The industry also benefits from export opportunities, with U.S. dairy proteins being supplied to manufacturers in the Asia-Pacific, Latin America, and the Middle East. This not only improves plant utilization rates but also supports economies of scale.
Additionally, advancements in genetics, precision livestock management, automated milking systems, and feed optimization have led to increased milk productivity per cow, allowing for greater protein availability without proportional herd expansion. These technological and operational enhancements improve manufacturing efficiency while meeting the consistent quality standards required by food and beverage companies. As consumer preferences continue to shift toward protein-enriched products with higher nutritional value, the strong integration of dairy farming, cheese manufacturing, and ingredient processing will remain a critical competitive advantage for the U.S. protein ingredients market. This enables manufacturers to provide premium dairy proteins with reliable supply, advanced functionality, and diverse applications across multiple end-use industries.
The strong connection between sports nutrition and the U.S. protein ingredients market is significantly driving product innovation, ingredient selection, and investments in manufacturing across the food and beverage sector. The United States boasts one of the largest fitness ecosystems globally, featuring over 72 million health club members and more than 40,000 fitness facilities. This robust environment creates a sustained demand for protein-enriched products that promote muscle recovery, endurance, and active lifestyles.
As the consumer base expands, the adoption of various protein sources including whey protein isolate, milk protein isolate, collagen peptides, egg protein, pea protein, and blended protein formulations across sports nutrition applications is accelerating. Unlike traditional protein supplements, manufacturers are now more frequently integrating functional proteins into ready-to-drink beverages, hydration products, protein coffees, energy bars, cereals, and portable snack formats, reflecting the shifting preferences of consumers towards convenient nutrition.
U.S. Sports Nutrition Market: Protein Ingredient Adoption Rate (2025)
Product differentiation is increasingly focusing on ingredients that offer rapid digestibility, high leucine content, complete amino acid profiles, and enhanced bioavailability. This shift is prompting ingredient suppliers to create customized formulations targeted at athletes, recreational fitness enthusiasts, and active aging populations. Concurrently, e-commerce has emerged as a significant growth driver, with direct-to-consumer nutrition brands expanding across the nation via digital platforms, subscription models, and personalized nutrition programs, thereby boosting the demand for premium protein ingredients.
Innovation in flavor masking, instantization, and heat-stable protein technologies is further enabling manufacturers to launch protein-fortified beverages and shelf-stable products without sacrificing taste or texture. Additionally, professional sports organizations, collegiate athletics, and the increasing popularity of endurance events like marathons, triathlons, and cycling competitions are reinforcing the role of protein consumption as a vital aspect of performance nutrition.
Manufacturers are also developing hybrid formulations that combine dairy and plant proteins, providing balanced nutrition while catering to flexitarian consumers. These evolving trends are strengthening the demand for high-quality functional proteins, positioning sports nutrition as one of the most influential sectors driving innovation, product diversification, and long-term growth within the U.S. protein ingredients market.
The U.S. protein ingredients market is characterized by a concentrated regional structure, with both production and consumption primarily occurring in states that boast strong agricultural output, advanced food processing infrastructure, and established manufacturing ecosystems for ingredients. California stands at the forefront, holding an estimated 14.8% market share, driven by its extensive functional food industry, innovations in plant-based proteins, and one of the largest nutraceutical manufacturing clusters in the country. This state’s concentration of food technology companies and health-conscious consumer brands significantly boosts demand for premium protein ingredients in beverages, dietary supplements, and clean-label food products.
U.S. Protein Ingredients Market: State-wise Market Share (2025, Analyst Estimate)
Wisconsin ranks second with a 12.6% share, leveraging its position as the top cheese-producing state, which generates a considerable supply of whey, milk protein concentrates, and specialty dairy proteins for both domestic and international markets. Minnesota, accounting for approximately 10.9%, is propelled by substantial investments in pea protein processing, agricultural biotechnology, and value-added ingredient manufacturing.
Illinois contributes 9.8% to the market, aided by major ingredient manufacturers and world-class transportation infrastructure that enables efficient sourcing and distribution through extensive agricultural supply chains. Texas, with an 8.7% share, is rapidly emerging as a hub for sports nutrition products, functional beverages, and contract food manufacturing, reflecting the rising investment in protein-fortified consumer goods.
Iowa strengthens the market with its large-scale soybean processing and protein extraction capabilities, while both Idaho and Pennsylvania are expanding their dairy protein production by modernizing milk processing facilities. New York plays a crucial role in the realms of premium nutrition, medical foods, and product innovation. Furthermore, Nebraska benefits from integrated livestock and agricultural processing operations that support the production of animal-based protein ingredients.
Together, the top ten states constitute approximately 83% of the U.S. protein ingredients market, underscoring the significance of regional manufacturing clusters, the availability of agricultural resources, transportation connectivity, and robust food innovation ecosystems in shaping national production capacity and the long-term competitiveness of the industry.
Key companies analyzed within the U.S. protein ingredients market are: Archer Daniels Midland (ADM), Cargill, Incorporated, Ingredion Incorporated, International Flavors & Fragrances (IFF), Kerry Group, Glanbia Nutritionals, Roquette, Arla Foods Ingredients, Fonterra Co-operative Group, Hilmar Cheese Company, Milk Specialties Global, PURIS, Perfect Day, Nature's Fynd and other.
Contract manufacturing has emerged as a vital growth driver within the U.S. protein ingredients market, allowing consumer brands to broaden their product offerings without the need to invest in dedicated manufacturing facilities. The U.S. hosts numerous specialized contract manufacturers that provide services such as formulation, blending, spray drying, packaging, and regulatory compliance for protein-based products spanning food, beverage, and nutrition categories.
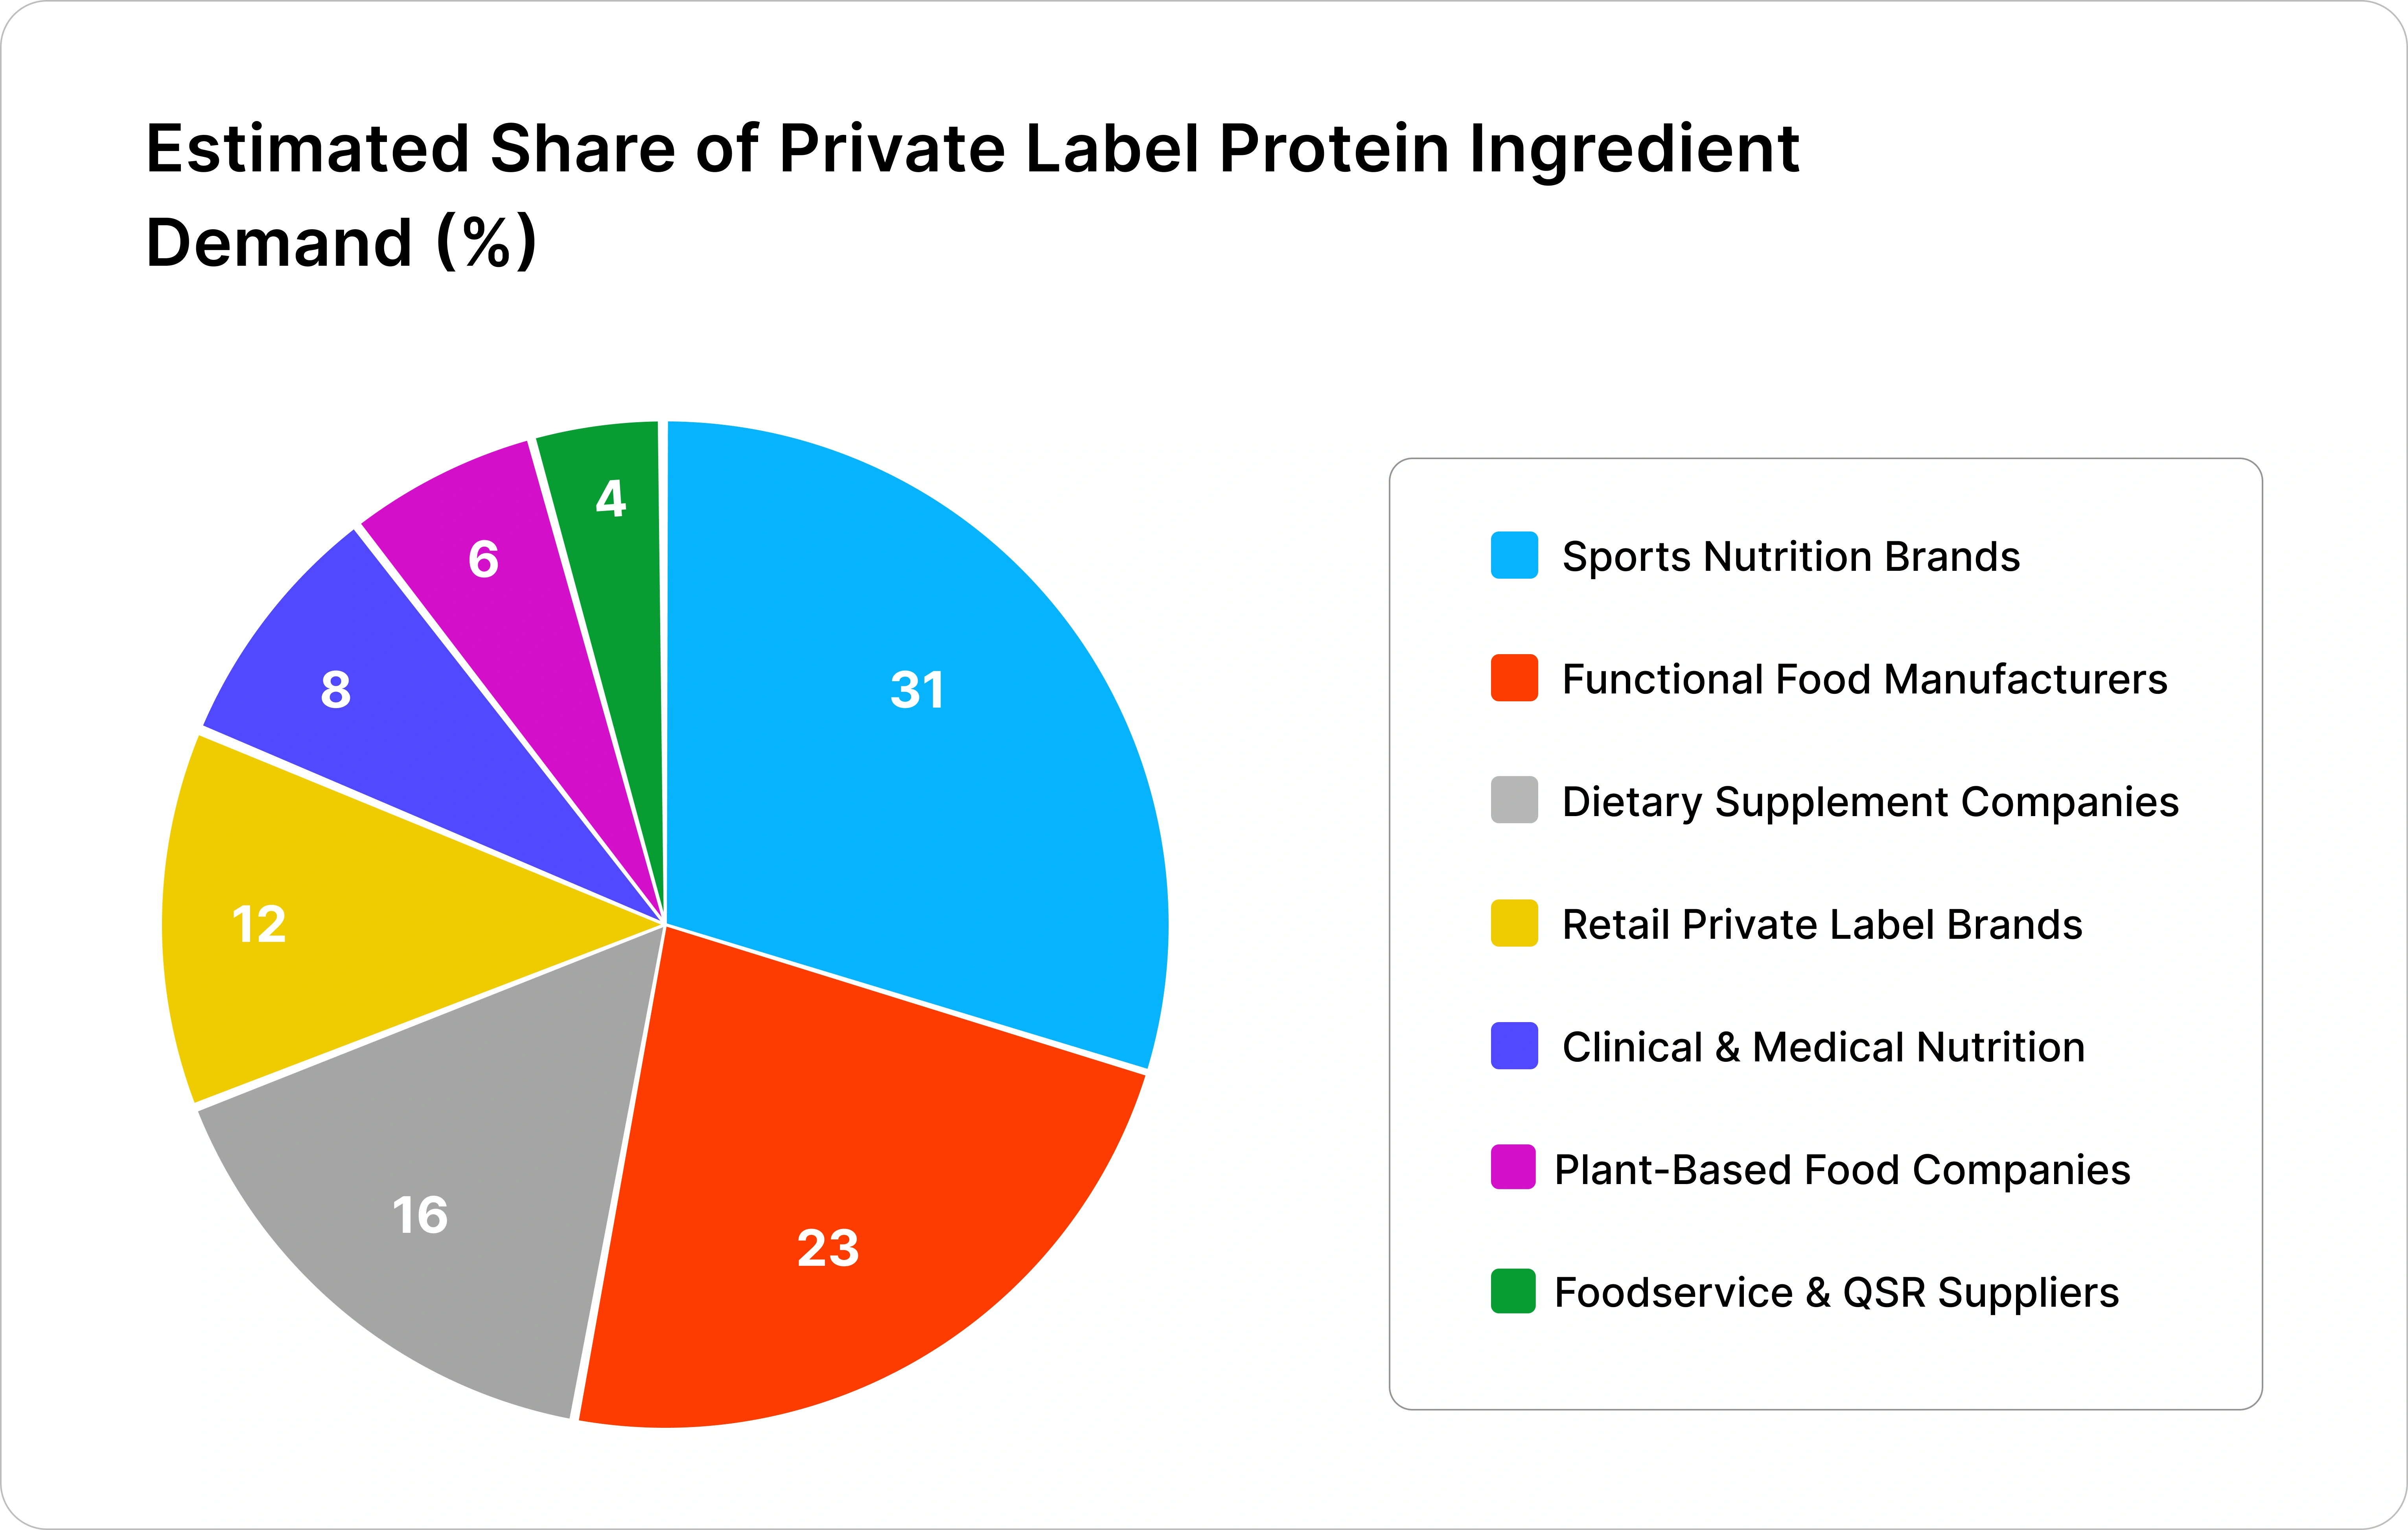
Industry estimates show that over 60% of new sports nutrition and dietary supplement brands utilize third-party manufacturers during their commercialization phases, which facilitates quicker product launches and minimizes capital expenditures. This trend of outsourcing has gained momentum as companies strive for flexible production capacities that enable them to respond swiftly to shifting consumer preferences and shorter product development cycles.
Private-label retail brands have also seen substantial growth, with major supermarket chains, warehouse clubs, and e-commerce retailers launching protein powders, ready-to-drink beverages, meal replacements, and nutrition bars under their own labels to boost profit margins and enhance customer loyalty.
To stand out in the competitive landscape, contract manufacturers are increasingly providing turnkey solutions that encompass ingredient sourcing, flavor development, quality assurance, packaging design, and regulatory documentation, which helps to simplify operations for brand owners. Advances in automated blending systems, continuous processing technologies, and digital quality monitoring have enhanced production efficiency while ensuring consistent product quality across batches.
Moreover, manufacturers that can produce allergen-controlled, organic, non-GMO, kosher, halal, and clean-label protein formulations are establishing long-term partnerships with premium consumer brands seeking unique market positioning. The rapid growth of e-commerce and direct-to-consumer nutrition companies has further fueled demand for small- and medium-volume manufacturing runs, allowing brands to experiment with new formulations prior to scaling production nationwide.
As customization, formulation flexibility, and swift commercialization become increasingly crucial competitive advantages, contract manufacturers will play an essential role in driving innovation throughout the U.S. protein ingredients market. This will support both established multinational companies and fast-growing nutrition startups through scalable and cost-effective production capabilities.
The Epignosis Insights Competitive Assessment Framework (EICAF) offers a structured approach for evaluating competitive positioning in the U.S. protein ingredients market by assigning weighted scores to key factors that significantly influence long-term business success. Unlike traditional benchmarking, which often focuses solely on revenue or market share, EICAF assesses operational strength, innovation capability, manufacturing resilience, and commercial execution to provide a comprehensive evaluation of ingredient suppliers.
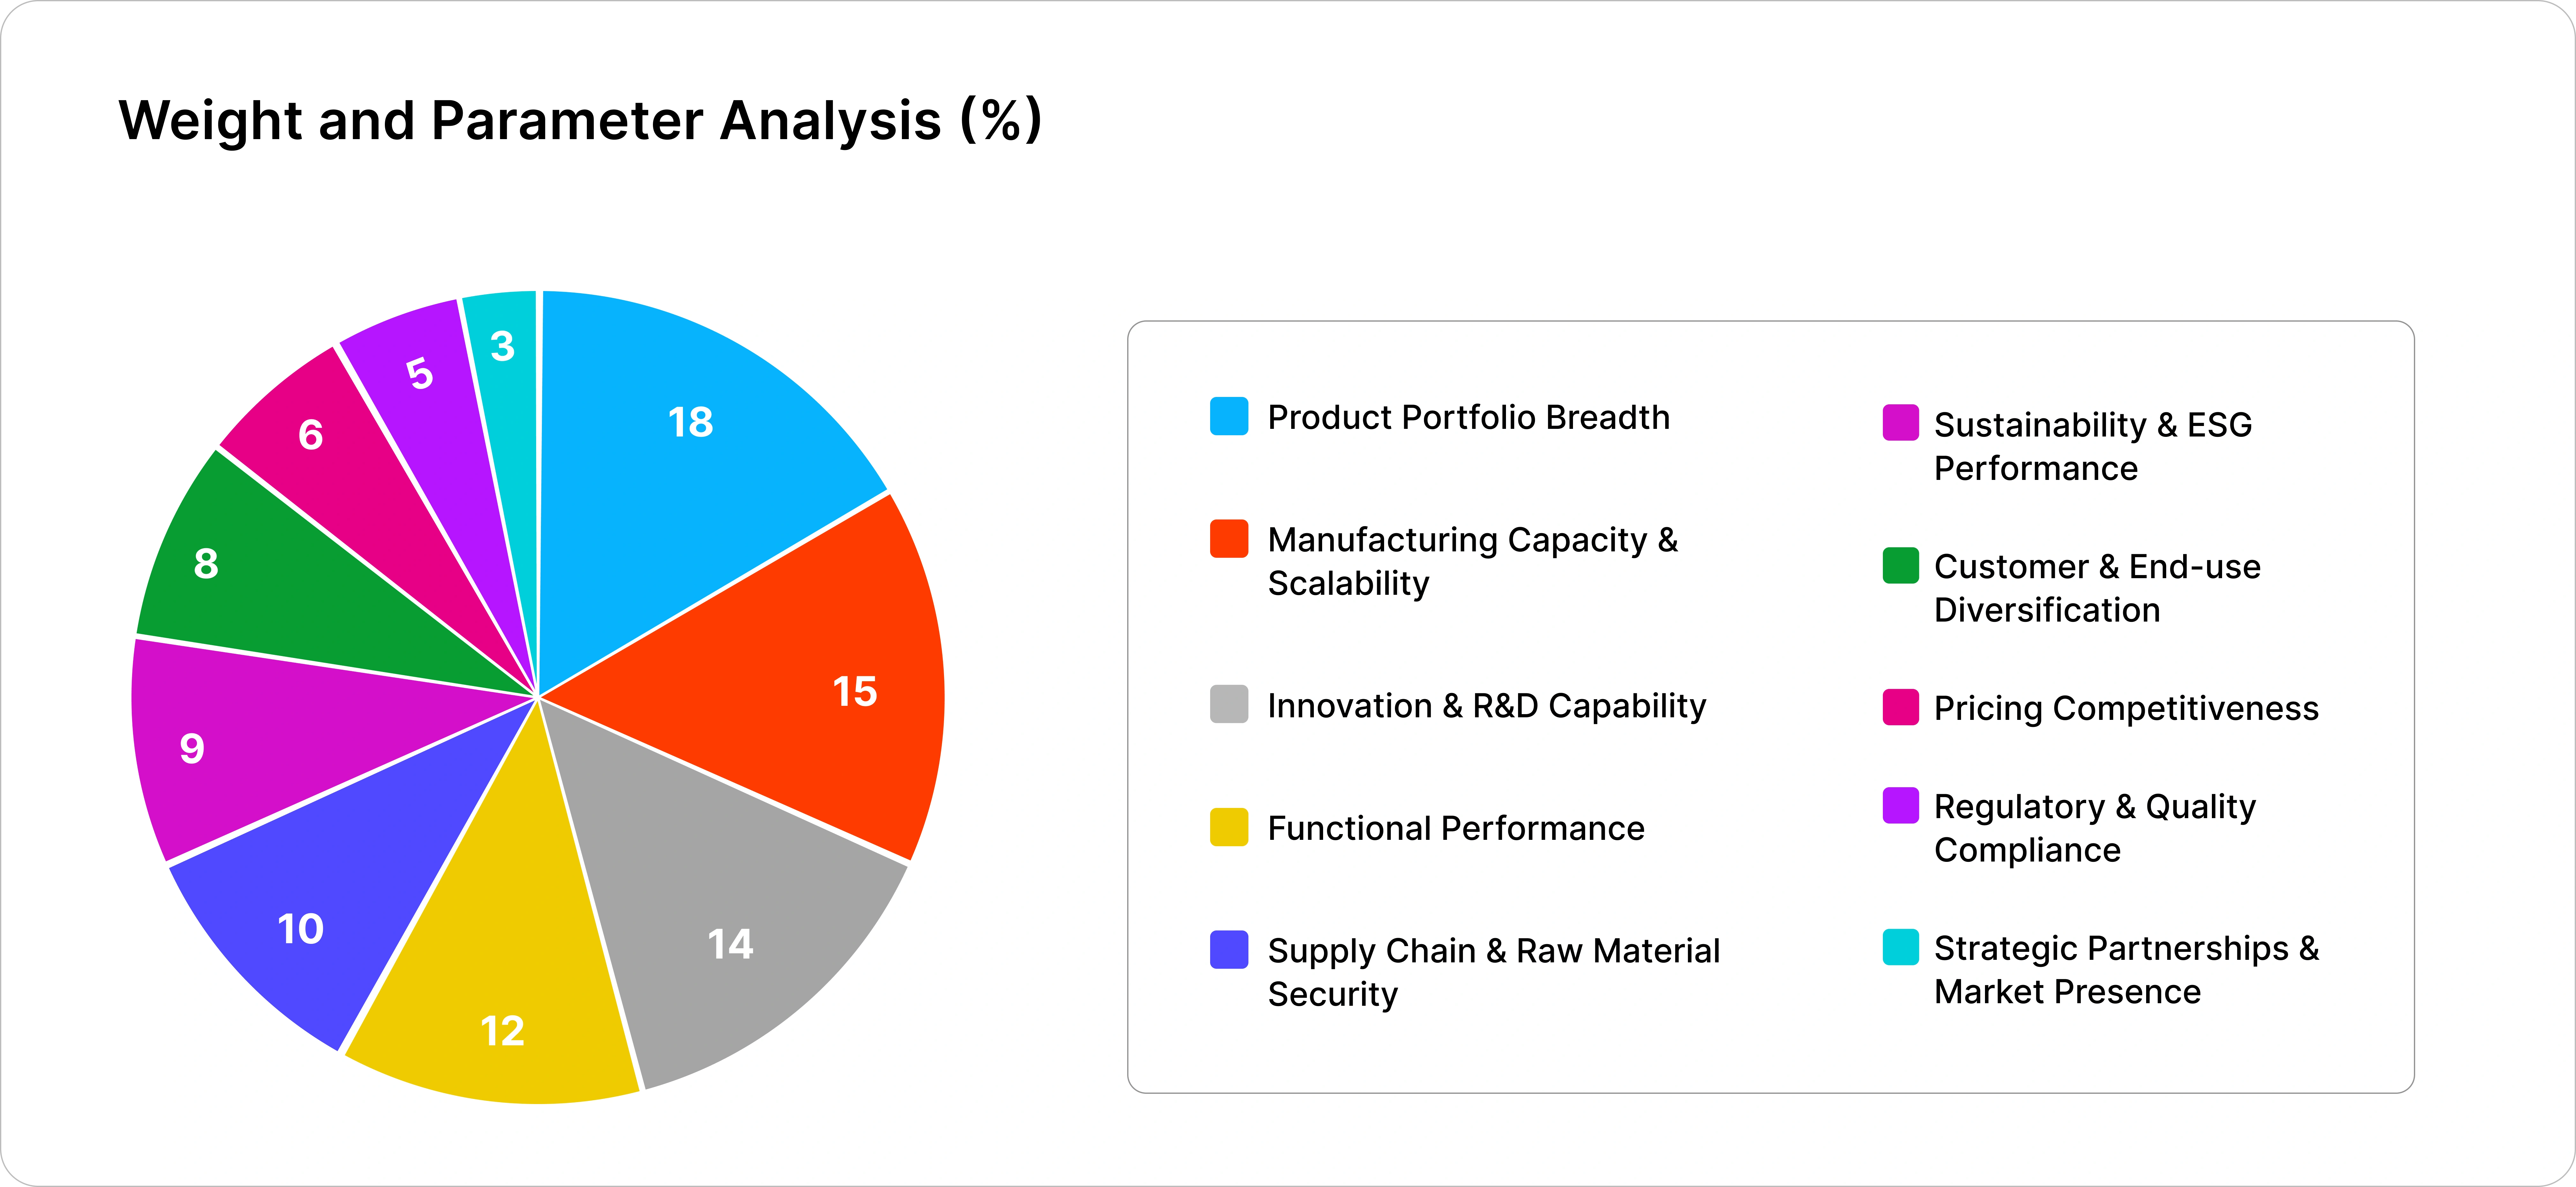
The framework prioritizes product portfolio breadth at 18%, recognizing that manufacturers with a diverse range of protein solutions including dairy, plant, collagen, microbial, and specialty proteins are better equipped to meet various high-growth applications while minimizing reliance on a single product category. Manufacturing capacity and scalability are the second-most important criteria, with a 15% weighting. This reflects the significance of efficient production expansion and consistent service levels in maintaining customer loyalty and supply reliability.
Innovation and research capability also play a crucial role, accounting for 14% of the framework. As companies invest in advanced extraction technologies, precision fermentation, and tailored ingredient development, they aim to distinguish themselves in a highly competitive market. Functional performance, weighted at 12%, underscores the importance of protein solubility, heat stability, emulsification, and texture enhancement in food and beverage formulations.
Supply chain security and sustainable sourcing collectively represent 19% of the assessment, emphasizing the critical nature of raw material availability, traceability, environmental performance, and robust procurement strategies. Additionally, commercial diversification across sectors like sports nutrition, functional foods, dairy, clinical nutrition, and animal nutrition enhances competitive resilience by lessening vulnerability to demand fluctuations in individual areas.
The framework also acknowledges the significance of pricing competitiveness, regulatory compliance, and strategic partnerships as vital supporting factors that foster customer confidence and contribute to long-term profitability. By integrating quantitative weightings with qualitative business intelligence, EICAF provides investors, manufacturers, and food companies with the tools to benchmark competitors objectively, identify strategic strengths, and assess future growth opportunities within the dynamic U.S. protein ingredients market.