Global Scrap Recycling Market: Strategic Consulting Perspective on Circular Economy, Technology and Industry Transformation 2026
Analysis by Scrap Type (Ferrous Scrap, Non Ferrous Scrap), Source, Recycling Process and End Use


Analysis by Scrap Type (Ferrous Scrap, Non Ferrous Scrap), Source, Recycling Process and End Use
Scrap recycling Market recorded a recycling volume of 986 million tons in 2025 and is estimated to reach a volume of 1,472 million tons by 2033 with a CAGR of 5.4% during the forecast period.
Global Scrap Recycling Market Dynamics
Declining Availability of High Grade Scrap Tightens Feedstock Economics
The Scrap recycling market is entering a supply quality constraint rather than simply facing a shortage of total material. High quality prompt scrap is increasingly difficult to expand because manufacturing processes are becoming more material efficient, reducing the amount of internally generated and fabrication scrap available to recyclers. This matters because prompt scrap is concentrated, relatively clean, and contains fewer unwanted materials, making it more valuable than mixed end of life scrap. At the same time, the rapid expansion of EAF based steelmaking is increasing competition for suitable metallic feedstock. EAFs can technically operate with up to 100% scrap, but steelmakers producing demanding flat products require tighter control of residual elements such as copper and tin.
The strategic constraint is therefore quality adjusted availability. As easily recoverable, clean scrap becomes increasingly contested, recyclers must invest in advanced sorting, shredding and residual metal separation to convert lower quality obsolete scrap into furnace suitable feedstock. This creates a widening cost differential between operators with sophisticated processing infrastructure and fragmented collectors selling minimally processed material. The issue is particularly important for automotive sheet and other flat products, where even small concentrations of tramp elements can create manufacturing defects.
For the Scrap recycling market, this dynamic shifts competitive advantage from simply securing the largest scrap volumes toward securing high yield, low contamination feedstock at predictable delivered cost. Regions with growing obsolete scrap availability will therefore become strategically attractive only when collection and separation infrastructure develops alongside the expanding material pool. worldsteel expects obsolete scrap availability to increase by about 500 Mt over the next three decades, but notes that much of this growth will occur in developing economies where collection and separation infrastructure remains a critical bottleneck.
Limited Traceability Restricts Premium Pricing for Recycled Material
In the Scrap recycling market, traceability is increasingly becoming a commercial differentiator rather than only a compliance requirement. Recycled material can command stronger commercial value when buyers can verify its origin, grade, processing route, contamination profile, and recycled content. However, fragmented collection networks and multiple ownership transfers make it difficult to maintain a consistent material record from generation through sorting and processing to the final metal producer. This creates an information gap between recyclers and industrial buyers, particularly when manufacturers are targeting specific recycled content or carbon intensity thresholds. The European Commission identifies improved scrap quality classification and better matching of secondary raw material supply with demand as priorities, highlighting the economic importance of more standardized material information.
The commercial consequence is significant: when provenance and quality cannot be reliably demonstrated, buyers tend to value material according to broad commodity grades rather than verified sustainability attributes. This limits the recycler's ability to capture a premium for cleaner, lower carbon or specification compliant material. The problem is particularly relevant for steel and aluminum supply chains where downstream manufacturers increasingly need evidence supporting recycled content and environmental claims. The European Commission's planned Digital Product Passport framework specifically identifies iron and steel as a priority sector and expects relevant information to include material composition, recycled content, sustainability attributes and traceability documentation.
For the Scrap recycling market, the strategic opportunity is therefore to shift from transaction based scrap trading toward data enabled material certification. Recyclers with digital weighbridge records, automated sorting data, batch level composition testing and chain of custody systems can create auditable material profiles and differentiate their output. The EU DPP Registry became operational in July 2026, while the Commission expects iron and steel specific requirements to progress during 2026. This could gradually change procurement from simply asking “What grade is this scrap?” toward “Can the recycler prove exactly what this material contains and where it came from?” That shift creates an opportunity for larger integrated recyclers to capture higher value through verified recycled content, while smaller operators without digital traceability infrastructure risk remaining concentrated in lower margin commodity trading.
The Scrap recycling market shows a pronounced difference between ferrous and non ferrous materials, but the comparison needs to distinguish overall end of life recycling from material specific recovery metrics. Steel has a structural advantage because its magnetic properties enable efficient collection and its established scrap infrastructure supports high recovery. worldsteel estimates the current steel recycling rate at approximately 85% globally, while recovery varies considerably by application, reaching around 90% for automotive and machinery products and about 85% for construction. Aluminium demonstrates similarly strong circularity economics, with the International Aluminium Institute reporting a global recycling efficiency rate of 76%, while more than 30 million tonnes of aluminium scrap are recycled annually. Copper has a different recovery profile, with approximately 40% of copper recycled at product end of life, increasing to 56% when pre consumer scrap is included.
US data illustrates why geographic comparisons require caution. EPA estimates a 27.8% recycling rate for ferrous metals from durable goods compared with approximately 68% for non ferrous metals in its 2018 dataset. These figures measure a different waste stream from the global steel recycling rate and therefore should not be directly ranked as equivalent metrics.
Geographically, Europe demonstrates particularly strong aluminium recovery infrastructure, with aluminium beverage can recycling reaching 76.3% across the EU, UK, Switzerland, Norway and Iceland in 2023. For aluminium efficiency specifically, historical IAI regional data placed Europe at 81%, compared with North America at 57% on recycling input rate terms. More recent beverage can data shows East Asia and Pacific at 94.6% and Latin America and Caribbean at 94.0%, illustrating how high material value can drive recovery even where broader waste infrastructure differs.
The consulting implication for the Scrap recycling market is that future growth opportunity is less about increasing already high ferrous recovery rates and more about raising recovery of lower performing nonferrous streams, improving collection of complex products, and investing in regional processing capacity where valuable scrap remains outside formal channels.
The Scrap recycling market plays a strategic role in circular manufacturing by converting discarded metals into secondary feedstock that can reenter production without requiring the same level of virgin resource extraction. The strongest economic benefit is not simply waste diversion but resource displacement. In steelmaking, every tonne of scrap used avoids approximately 1.4 tonnes of iron ore, 740 kg of coal and 120 kg of limestone consumption, while avoiding about 1.5 tonnes of CO₂ emissions. This gives scrap a direct role in reducing both raw material intensity and production emissions. Aluminium provides an even stronger resource efficiency case because recycling requires up to 95% less energy than primary aluminium production, while more than 30 million tonnes of aluminium scrap are recycled globally each year.
The Scrap recycling market also reduces dependence on landfill and extends the productive life of materials already embedded in the economy. This is particularly important for metals because their physical properties can generally be retained through repeated recycling. Approximately 75% of all aluminium ever produced remains in productive use, effectively creating a large above ground material stock that can become future feedstock as products reach end of life. Copper illustrates another dimension: recycled copper currently meets approximately 32% of global copper demand, while around 40% of copper is recovered at product end of life.
For manufacturers, the strategic value extends beyond waste reduction. Integrating secondary metals into procurement can reduce exposure to mining supply disruptions, shorten material supply chains and improve recycled content credentials. However, circular manufacturing depends on maintaining sufficient scrap quality, collection efficiency and processing capacity. The commercial opportunity for the Scrap recycling market therefore shifts toward building closed loop supply relationships with manufacturers, where recyclers can deliver specification compliant secondary materials rather than simply selling commodity scrap. This creates a more predictable feedstock cycle and allows manufacturers to treat scrap as a strategic raw material rather than a waste stream.
The Scrap recycling market is exposed to a combination of commodity, feedstock, regulatory, energy, trade, and operational risks, with margin sensitivity being the most immediate concern. Scrap recyclers typically purchase material before processing and resell recovered metals, meaning a rapid decline in benchmark metal prices can compress inventory margins before selling prices adjust. This exposure becomes more significant for processors carrying large inventories or operating on thin spreads. Feedstock availability is another structural risk. Worldsteel estimates that more than 800 million tonnes of ferrous scrap are recycled annually, while obsolete scrap availability is expected to increase from approximately 650 million tonnes currently to 900 million tonnes by 2050. The growth in supply therefore exists, but the timing and geographic distribution of recoverable material remain critical constraints.
Energy costs create a second major margin variable because shredding, baling, sorting, melting, and material handling require substantial electricity and fuel. Aluminium recycling is particularly sensitive to electricity economics despite requiring up to 95% less energy than primary aluminium production.
Regulatory and trade risks can also rapidly redirect material flows. Steel safeguard measures, tariffs, export restrictions, waste shipment rules, and changing classifications can shift scrap toward alternative destinations, creating regional oversupply or shortages. The EU's transition toward tighter waste shipment controls is particularly relevant for recyclers dependent on cross border flows.
For the Scrap recycling market, operational risk is increasingly linked to processing sophistication. Contaminated feedstock, equipment downtime, fire incidents at shredding facilities, inconsistent scrap grades, and insufficient sorting capacity can reduce recovery yields and increase cost per tonne. Consequently, the strongest risk mitigation strategy is not simply securing greater scrap volumes, but combining multi source procurement, inventory discipline, energy management, automated sorting, diversified end markets, and geographically balanced processing capacity.
China is the largest participant in the Scrap recycling market by absolute volume, consuming 209.67 million tonnes of recycled steel in 2024, despite a 1.9% year on year decline. Its scale is driven primarily by the enormous domestic steel industry rather than an exceptionally high scrap intensity, with recycled steel accounting for only 20.9% of crude steel output. China also has more than 700 steel scrap recyclers with reported capacity exceeding 150 Mt/year, demonstrating substantial processing infrastructure but also a fragmented operating structure.
The Scrap recycling market in the United States has a fundamentally different profile. US recycled steel usage reached 55.3 Mt in 2024, equivalent to 69.2% of crude steel production, making the country one of the most scrap intensive major steel markets. US apparent iron and steel scrap consumption was approximately 63 Mt, while domestic steel scrap exports were approximately 15 Mt, highlighting the country's dual role as a large domestic consumer and major scrap supplier.

Turkey is strategically important despite having a much smaller steel industry than China because recycled steel represented approximately 84.8% of crude steel production in 2024. Turkey also imported 20.095 Mt of recycled steel, making it the world's largest recycled steel importer. This creates an unusually strong linkage between international scrap trading and domestic steel production.
For the Scrap recycling market, India represents a different growth opportunity. Recycled steel usage increased strongly during the first half of 2025, reaching 19.65 Mt, up 15.3% year on year, while the country's share of recycled steel in crude production reached 24.5%. This indicates that India's expanding steel production is gradually creating additional demand for secondary metallic feedstock.
Japan, South Korea and the EU 27 combine mature collection systems with relatively high scrap intensity. The EU's 59.2% scrap share and Japan's 36.7% demonstrate stronger integration of secondary steel than China and India. Consequently, future opportunity is less about simply increasing recycling volumes in these markets and more about securing high quality scrap, improving sorting yields and developing closed loop supply relationships with steelmakers.
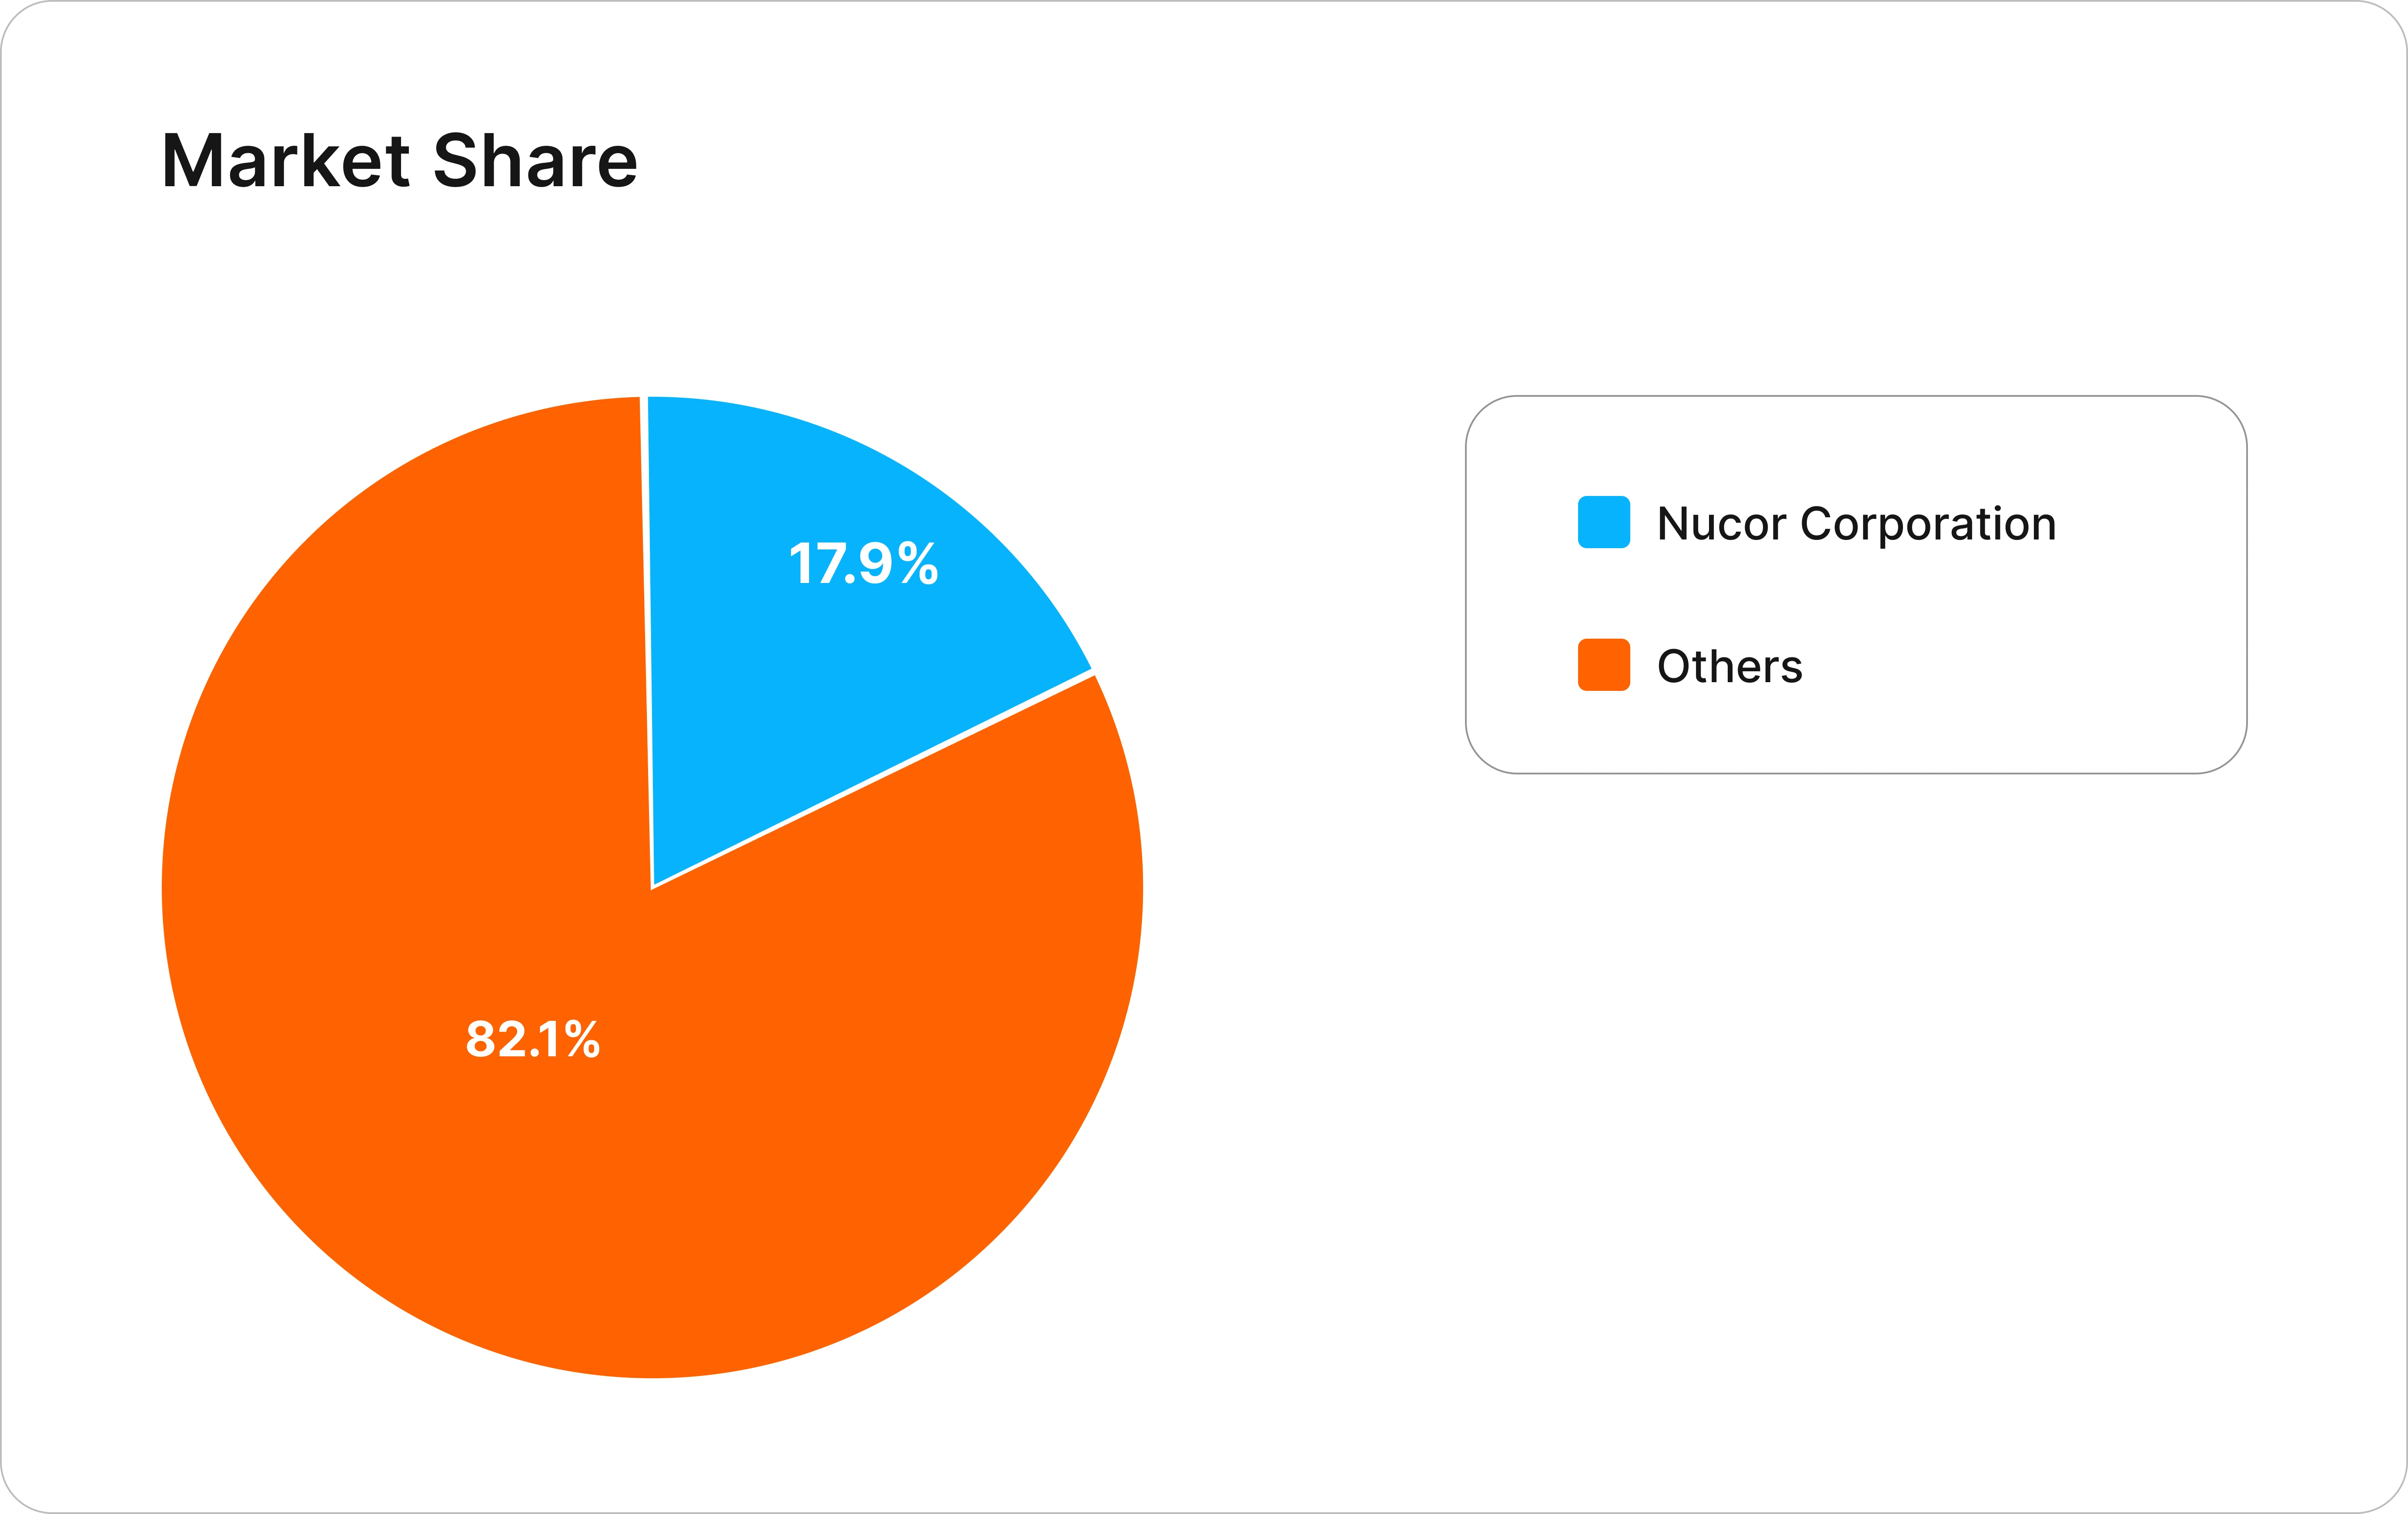
Key companies analyzed within the global scrap recycling market are: Sims Limited, EMR, Commercial Metals Company, Nucor Corporation, Radius Recycling (formerly Schnitzer Steel Industries; now a Toyota Tsusho subsidiary), Derichebourg, Aurubis AG, Kuusakoski, Stena Recycling, Harsco Environmental (division of Enviri Corporation, formerly Harsco Corporation), Dowa Holdings, Hanwa Co., TSR Recycling, OmniSource, SA Recycling, PADNOS and others.
The Epignosis Insights Competitive Assessment Framework (EICAF) for the Scrap recycling market evaluates companies based on their ability to secure feedstock, process diverse scrap grades efficiently, monetize recovered materials, and expand across high value end markets. Rather than relying only on revenue or company size, EICAF combines operating scale, processing capabilities, geographic reach, feedstock access, technology, customer integration, financial strength, sustainability positioning, and strategic execution.
This is particularly relevant because the global scrap recycling industry remains highly fragmented and company capabilities differ significantly between ferrous focused recyclers, integrated steelmakers, and non ferrous specialists. The framework assigns the highest weighting to scrap processing scale and feedstock access, as consistent access to suitable scrap directly determines capacity utilization and revenue generation. Geographic footprint and collection network receive the next highest weighting because proximity to scrap sources reduces transportation costs and improves procurement resilience.
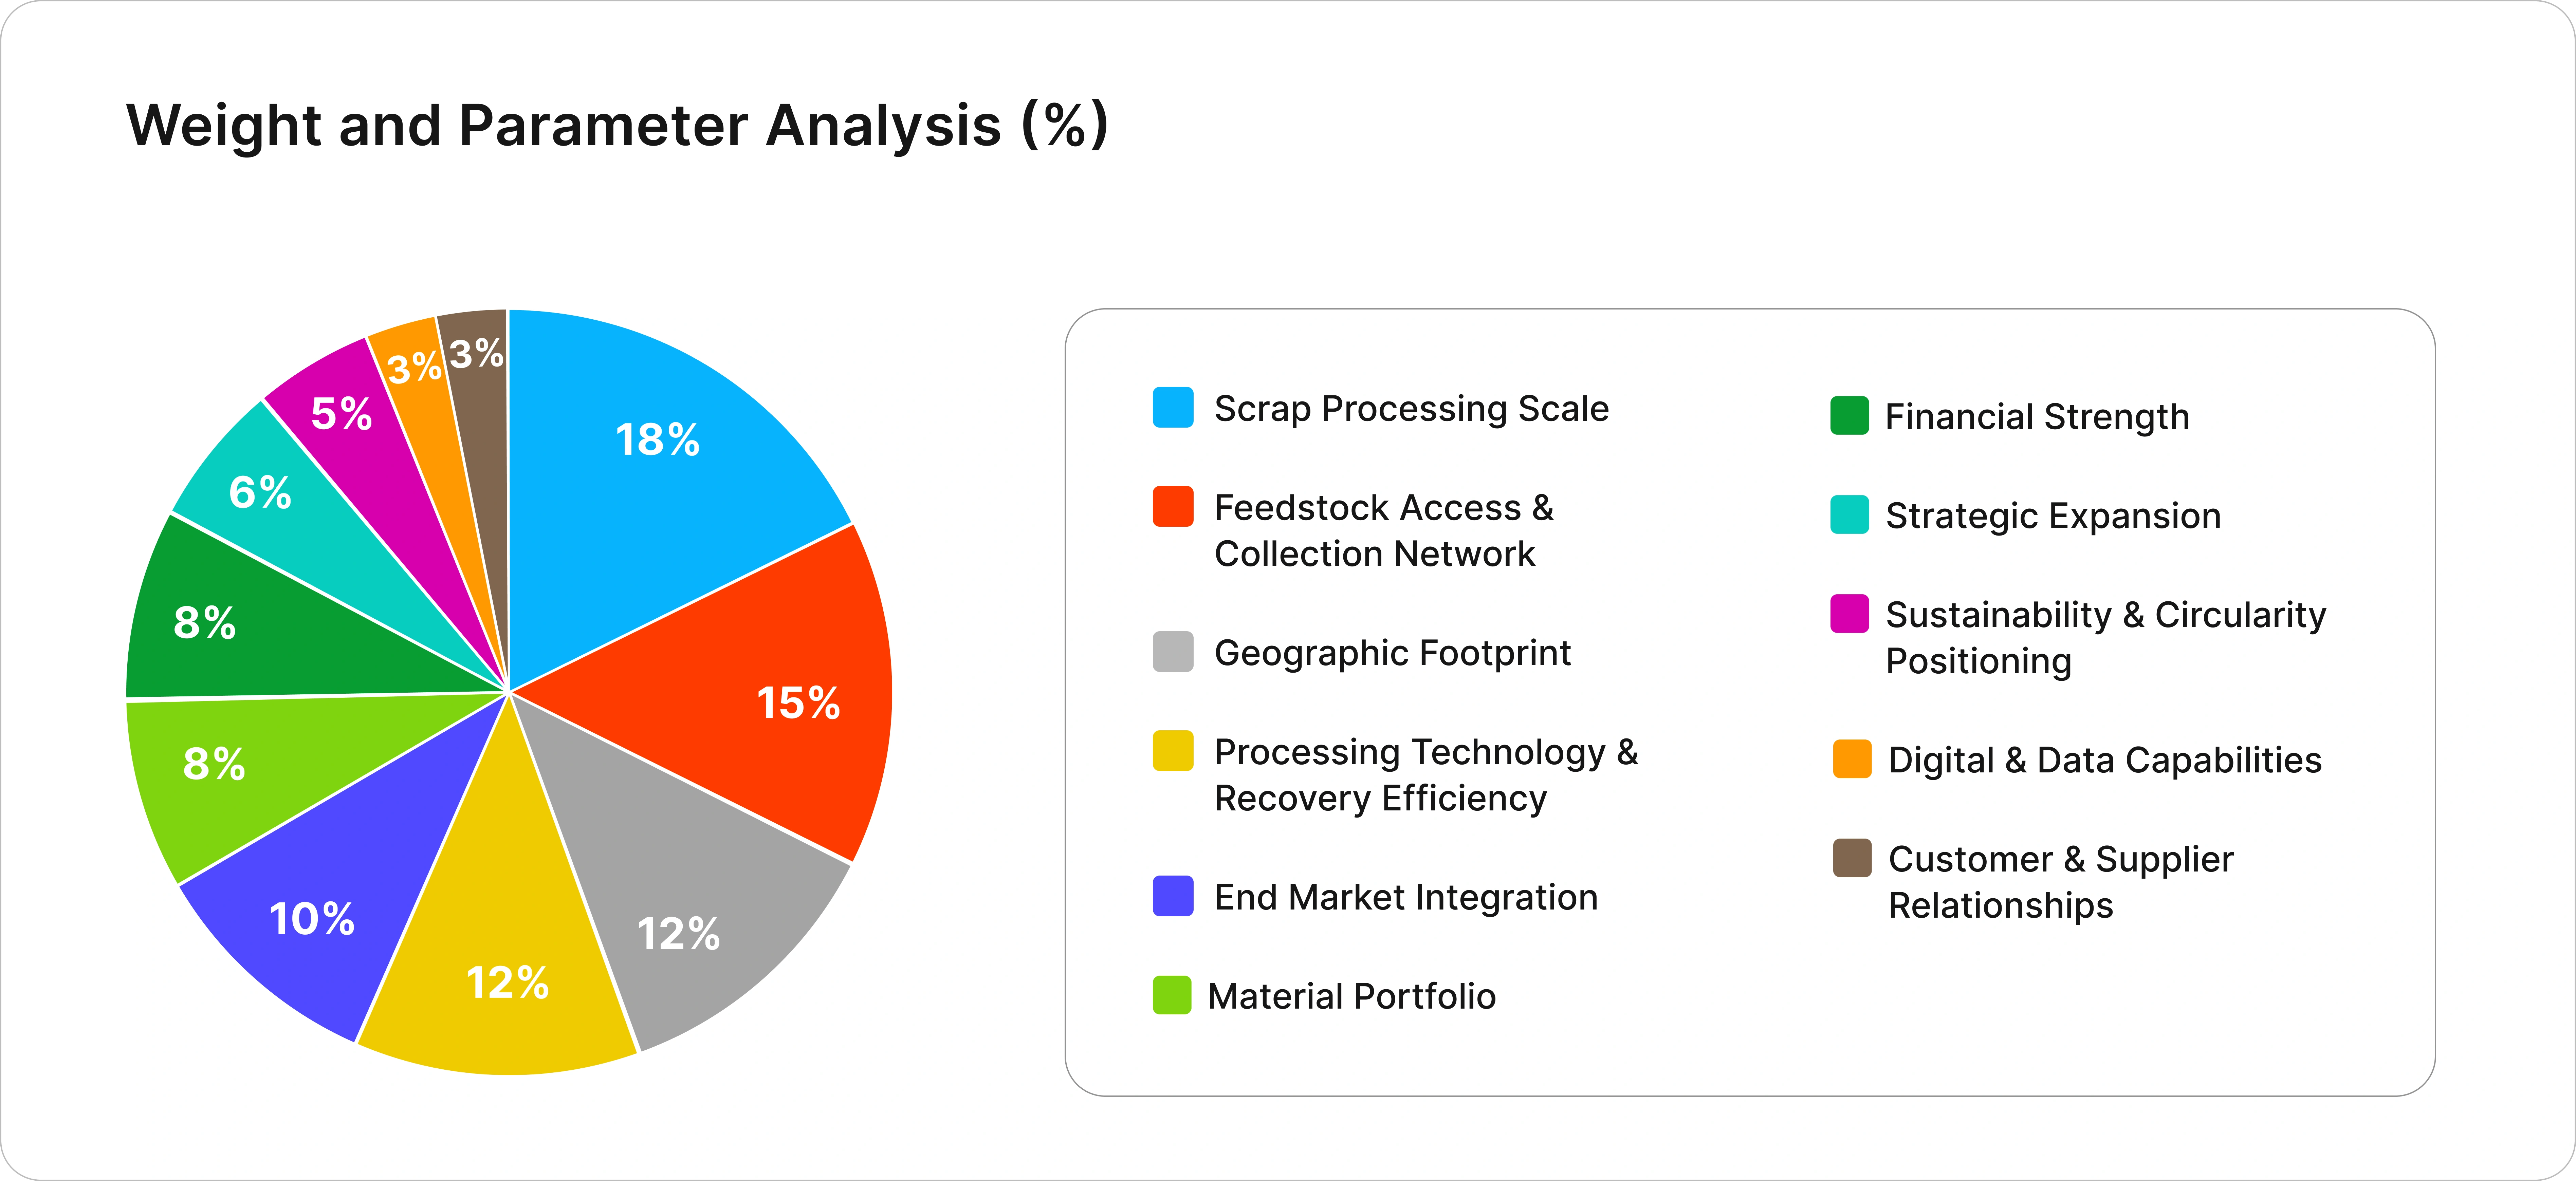
Processing technology and recovery efficiency are also heavily weighted because advanced sorting, shredding, separation, and refining capabilities allow companies to process lower quality material while improving recovered metal yields. End market integration measures access to steel mills, foundries, manufacturers, and downstream metal consumers, which can improve demand visibility and reduce dependence on spot markets. Financial and strategic strength captures investment capacity, acquisitions, facility expansion, and ability to withstand commodity price cycles. Sustainability capabilities are included because recycled content, emissions reduction, traceability, and circularity credentials increasingly influence industrial procurement. The Scrap recycling market therefore requires a competitive framework that distinguishes between scale and actual strategic capability.
EICAF can classify companies into Leaders, Strong Contenders, Emerging Competitors, and Regional Specialists, enabling clients to identify acquisition targets, partnership opportunities, market entry gaps, and capability benchmarks. The framework can also be applied separately to ferrous and non ferrous recycling because competitive advantages vary materially between the two segments.