Key Findings
- The North America Eco-Friendly Packaging Market is projected to grow from USD 63.0 billion in 2024 to USD 117.7 billion by 2034, registering a 7.7% CAGR (2027–2033).
- Market volume is expected to increase from 31.8 million tons in 2024 to 52.8 million tons by 2034, reflecting a 6.3% CAGR (2027–2033).
- The average selling price is forecast to rise from USD 1,980/ton in 2024 to USD 2,230/ton by 2034, supported by increasing adoption of premium sustainable materials.
- Paper & Paperboard is the largest material segment, accounting for 34% of the market.
- Corrugated Fiberboard holds the second-largest share at 19%, driven by sustained e-commerce and logistics demand.
- Recycled Plastics (rPET, rHDPE, rPP) represent 10% of the market and are among the fastest-growing material categories due to recycled-content mandates.
- Food & Beverages is the leading end-use industry with a 44% market share, followed by Healthcare & Pharmaceuticals (11%) and E-commerce & Logistics (10%).
North America Eco Friendly Packaging Market Outlook
North America Eco Friendly Packaging Market recorded a sales volume of 33.6 million tons in 2025 and is estimated to reach a volume of 52.8 million tons by 2033 with a CAGR of 6.3% during the forecast period.
North America Eco Friendly Packaging Market Dynamics
Brand Owners Replacing Virgin Plastics with High Recycled-Content Packaging to Meet ESG Targets
The shift from virgin plastics to high recycled-content packaging is emerging as a significant growth driver for the North America eco-friendly packaging market. Consumer goods companies are increasingly aligning their packaging strategies with environmental, social, and governance (ESG) objectives and circular economy commitments. Major global consumer brands in North America have set ambitious targets to incorporate 25–50% recycled content into their plastic packaging over the next decade while aiming to reduce their reliance on fossil-based virgin resins.
This growing commitment is driving demand for food-grade recycled polyethylene terephthalate (rPET), recycled high-density polyethylene (rHDPE), and recycled polypropylene (rPP). It is also fostering long-term supply agreements between packaging manufacturers and recycling companies. Each year, the United States collects over 2 billion pounds of PET bottles and containers for recycling, which provides an expanding feedstock base for bottle-to-bottle applications. However, the demand for high-quality recycled polymers continues to outstrip supply.
In response to this trend, several U.S. states have implemented minimum post-consumer recycled-content requirements for beverage containers and select plastic packaging formats, further spurring the adoption of recycled materials. Major packaging converters are making significant investments in advanced technologies for washing, decontaminating, and pelletizing recycled resins, with the aim of enhancing the quality and consistency of materials suitable for food-contact applications.
The increase in high recycled-content packaging not only helps brand owners lower lifecycle greenhouse gas emissions but also improves resource efficiency and enhances ESG disclosures required by investors and corporate sustainability frameworks. Retailers are placing a premium on suppliers that can provide packaging with verified recycled content, which accelerates the procurement of circular packaging materials across various sectors, including food and beverage, household care, healthcare, and personal care.
Despite ongoing challenges related to feedstock availability and fluctuations in resin prices, continued investment in mechanical recycling capacity and closed-loop collection systems is expected to improve supply security in the coming years. As ESG performance becomes a critical competitive differentiator, the adoption of recycled-content packaging is set to remain a strategic priority that supports innovation, regulatory compliance, and sustainable value creation throughout the North America eco-friendly packaging market.
Limited Collection and Recycling Infrastructure for Flexible Plastic Packaging
The limited collection and recycling infrastructure for flexible plastic packaging is one of the most significant structural challenges facing the eco-friendly packaging market in North America. Flexible packaging formats including pouches, wraps, films, sachets, and multilayer laminates provide benefits such as lower material consumption, reduced transportation emissions, and extended product shelf life. However, the management of these materials at their end-of-life is lagging behind that of rigid packaging systems.
In the United States, the overall recycling rate for plastic packaging is under 15%, and the recovery rate for household flexible plastic packaging is even lower, largely because most municipal curbside recycling programs do not accommodate lightweight films. Issues such as contamination, mixed polymer structures, and multilayer barrier materials further diminish recyclability, leading to increased reliance on landfills or energy recovery processes. While store drop-off collection programs for polyethylene films have grown, consumer engagement and geographical coverage remain inconsistent across North America.
Recycling facilities face additional challenges as they require specialized sorting equipment, optical scanners, and film-washing systems to process flexible plastics effectively, resulting in significant capital investment needs for material recovery facilities. In response, packaging manufacturers are working on developing mono-material polyethylene and polypropylene structures that are more easily recyclable than traditional multilayer laminates, but widespread commercial adoption is still underway.
Investments in advanced mechanical and chemical recycling technologies are anticipated to enhance the recovery of difficult-to-recycle flexible packaging by producing recycled feedstocks that can be used for new packaging applications. Concurrently, several consumer goods companies are redesigning their packaging portfolios to improve recyclability and compatibility with existing recycling infrastructures. However, the absence of standardized collection systems across U.S. states and Canadian provinces continues to hinder economies of scale and the availability of high-quality post-consumer recycled materials.
To increase recycling rates, it will be essential to expand residential film collection, modernize material recovery facilities, enhance consumer education, and strengthen collaboration among municipalities, recyclers, retailers, and packaging manufacturers. Addressing these infrastructure challenges will not only improve circular material flows but also reduce dependency on landfills, thereby enhancing the long-term sustainability and competitiveness of the eco-friendly packaging market in North America.
North America Eco-Friendly Packaging Market: Material Cost and Pricing Trend Analysis
Material costs are one of the most significant factors influencing profitability and procurement strategies in the North American eco-friendly packaging market. The prices of sustainable packaging materials are impacted by the availability of recovered fiber, the supply of recycled polymers, energy costs, transportation expenses, and investments in advanced recycling infrastructure.
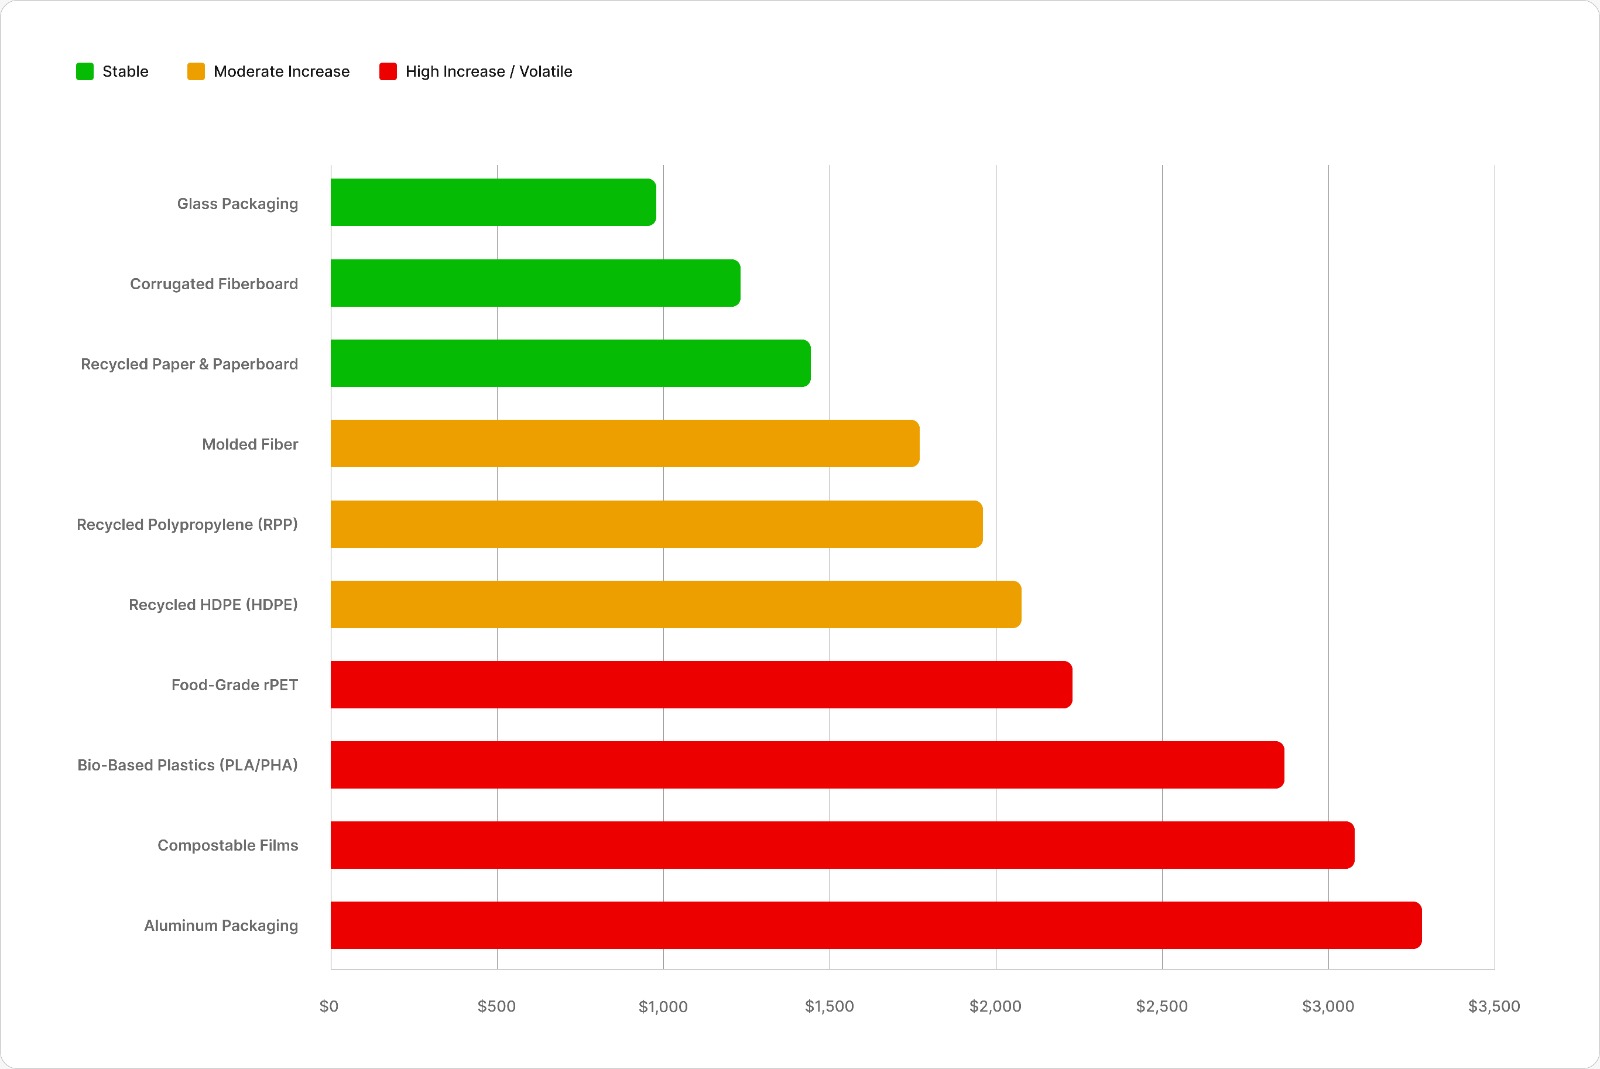
Recycled paper and corrugated fiber tend to offer relatively stable pricing because North America benefits from a mature paper recovery system, with recycling rates for paper and paperboard consistently exceeding 65% in recent years. On the other hand, food-grade recycled plastics, such as rPET and rHDPE, command premium prices due to limited supply and increasing demand from beverage, food, and personal care manufacturers aiming to meet recycled-content commitments. Virgin resin price volatility, which is tied to fluctuations in crude oil and natural gas markets, also affects the competitiveness of recycled materials.
To stabilize feedstock availability and reduce exposure to raw material price fluctuations, packaging converters are increasingly entering long-term procurement agreements with recyclers. Investments in mechanical recycling facilities, resin purification technologies, and domestic collection infrastructure are gradually enhancing supply security and facilitating more predictable pricing.
Fiber-based packaging is gaining commercial preference as lightweight designs and manufacturing efficiencies help to offset the higher costs associated with specialty coatings and barrier technologies. Additionally, advancements in digital manufacturing, AI-assisted packaging optimization, and lightweight material engineering are contributing to reduced overall material consumption per package, improving cost efficiency despite inflationary pressures.
While eco-friendly packaging generally comes with a price premium compared to conventional alternatives, major consumer brands are increasingly focusing on lifecycle value, regulatory compliance, and carbon reduction advantages rather than just short-term material costs. As domestic recycling capacity improves and economies of scale are realized, pricing volatility is anticipated to decrease, enhancing long-term competitiveness and supporting broader adoption across food and beverage, healthcare, e-commerce, retail, and industrial sectors within the North American eco-friendly packaging market.
North America Eco Friendly Packaging Market: Material Analysis
Material costs are one of the most significant factors influencing profitability and procurement strategies in the North American eco-friendly packaging market. The prices of sustainable packaging materials are impacted by the availability of recovered fiber, the supply of recycled polymers, energy costs, transportation expenses, and investments in advanced recycling infrastructure.
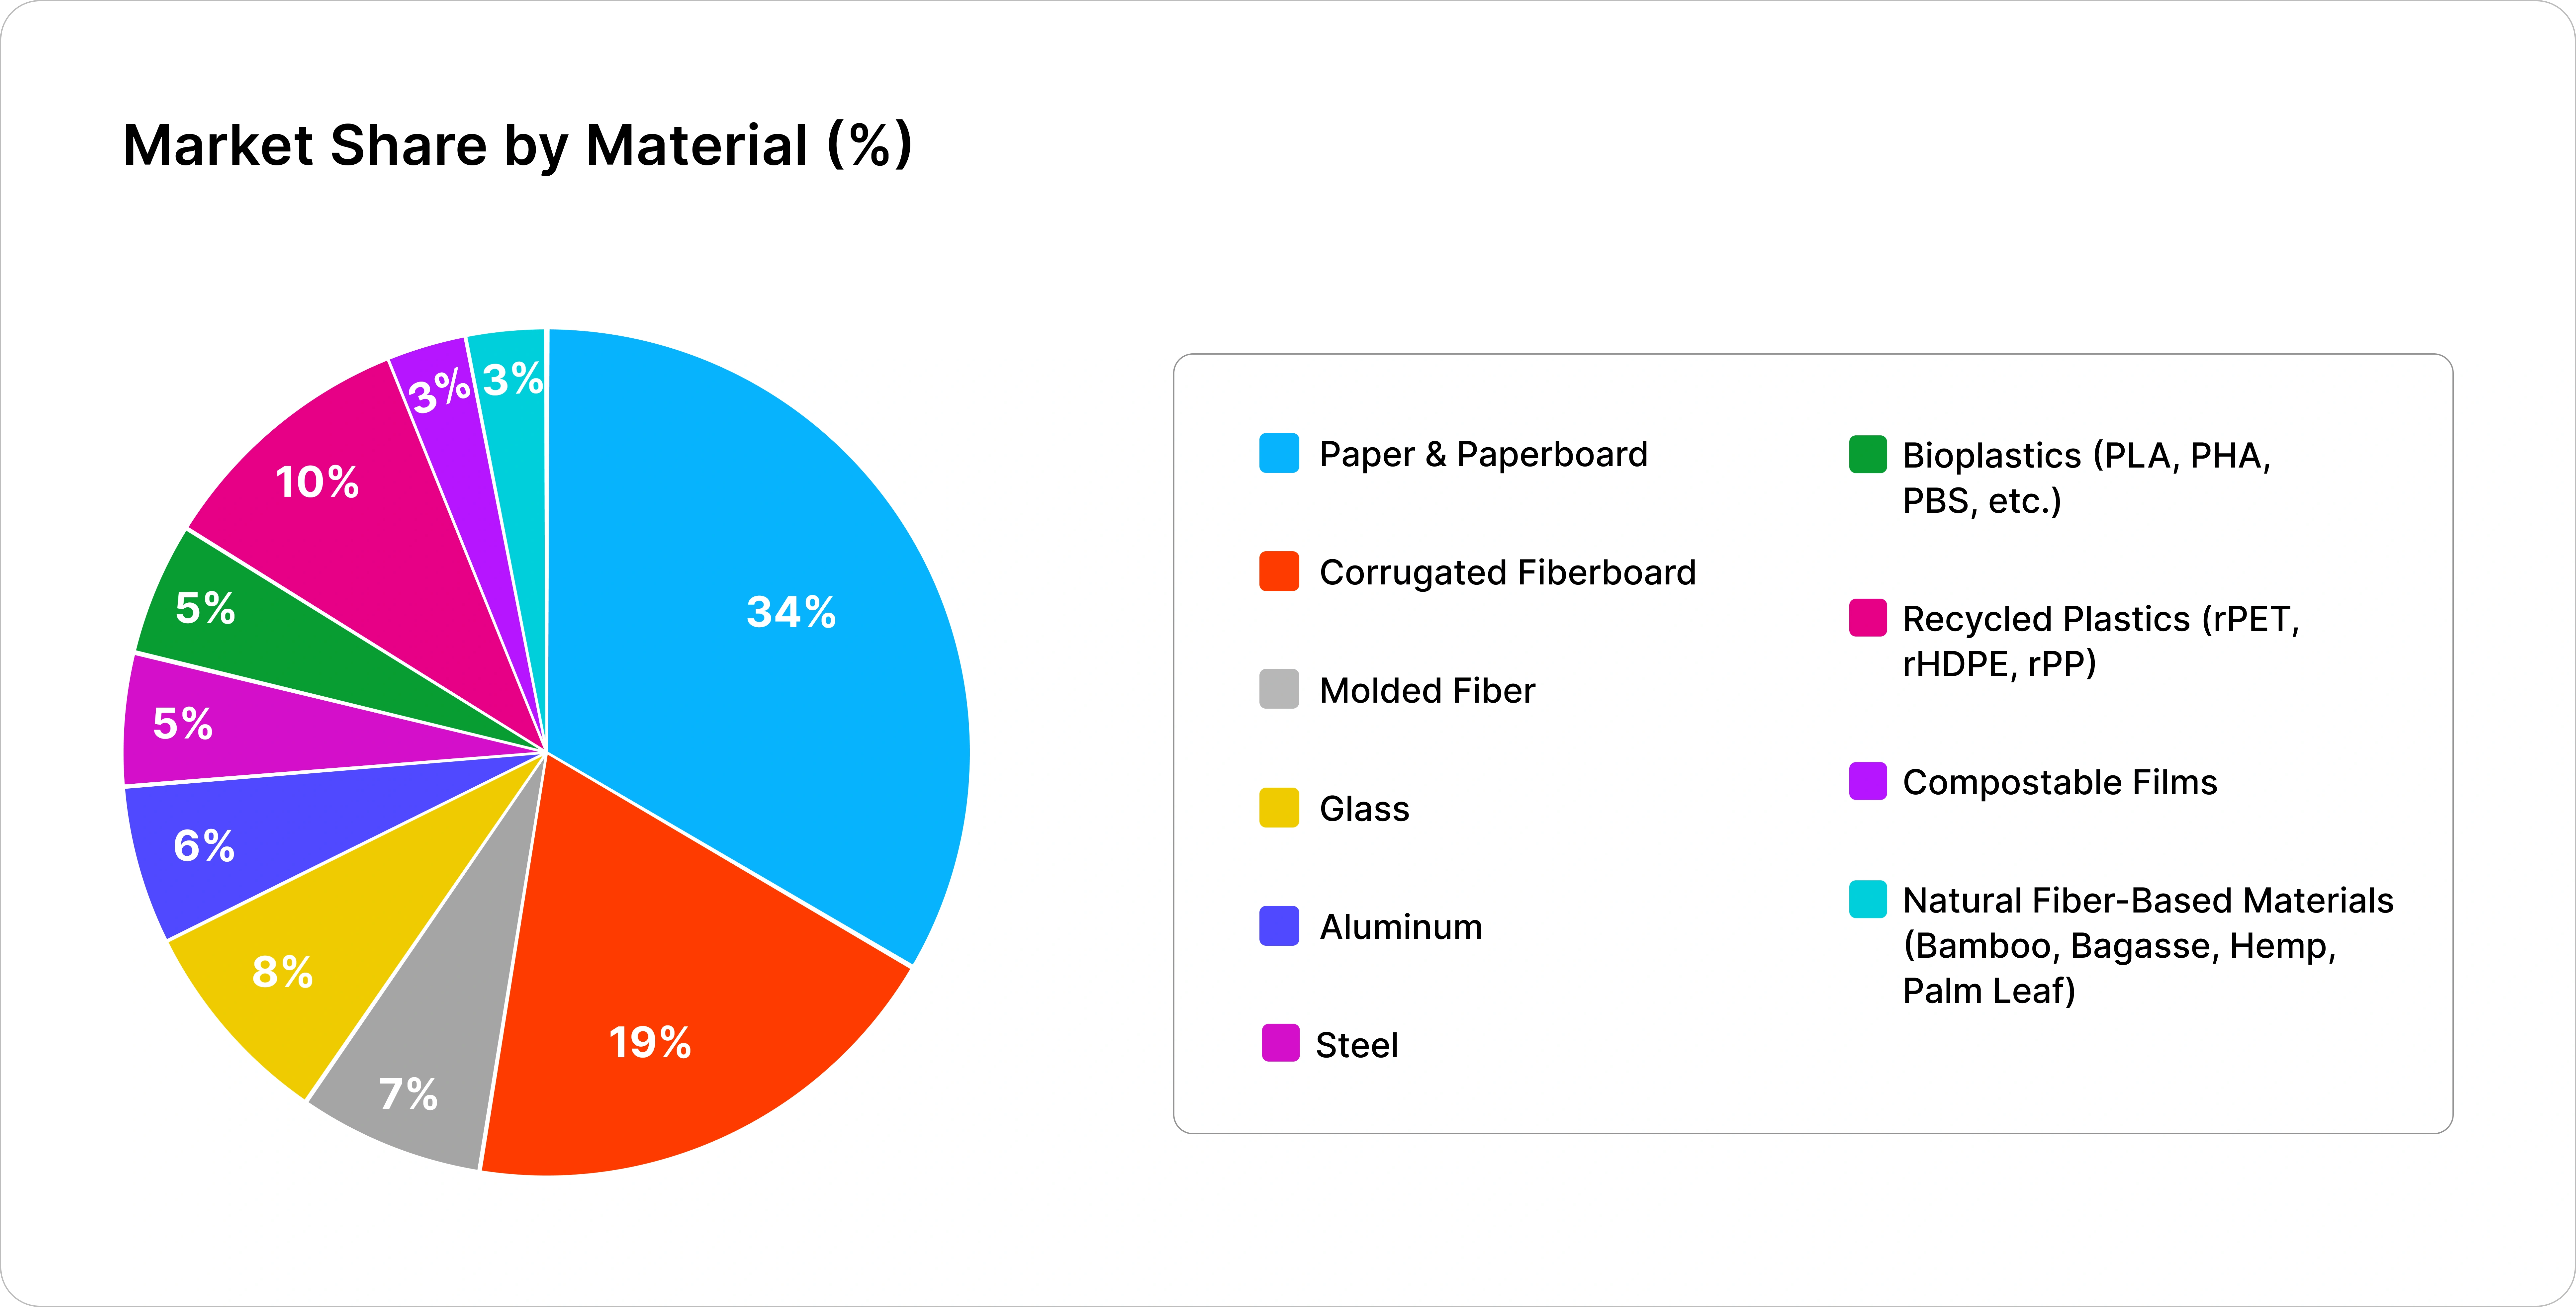
Recycled paper and corrugated fiber tend to offer relatively stable pricing because North America benefits from a mature paper recovery system, with recycling rates for paper and paperboard consistently exceeding 65% in recent years. On the other hand, food-grade recycled plastics, such as rPET and rHDPE, command premium prices due to limited supply and increasing demand from beverage, food, and personal care manufacturers aiming to meet recycled-content commitments. Virgin resin price volatility, which is tied to fluctuations in crude oil and natural gas markets, also affects the competitiveness of recycled materials.
To stabilize feedstock availability and reduce exposure to raw material price fluctuations, packaging converters are increasingly entering long-term procurement agreements with recyclers. Investments in mechanical recycling facilities, resin purification technologies, and domestic collection infrastructure are gradually enhancing supply security and facilitating more predictable pricing.
Fiber-based packaging is gaining commercial preference as lightweight designs and manufacturing efficiencies help to offset the higher costs associated with specialty coatings and barrier technologies. Additionally, advancements in digital manufacturing, AI-assisted packaging optimization, and lightweight material engineering are contributing to reduced overall material consumption per package, improving cost efficiency despite inflationary pressures.
While eco-friendly packaging generally comes with a price premium compared to conventional alternatives, major consumer brands are increasingly focusing on lifecycle value, regulatory compliance, and carbon reduction advantages rather than just short-term material costs. As domestic recycling capacity improves and economies of scale are realized, pricing volatility is anticipated to decrease, enhancing long-term competitiveness and supporting broader adoption across food and beverage, healthcare, e-commerce, retail, and industrial sectors within the North American eco-friendly packaging market.
North America Eco-Friendly Packaging Market: State-Level Sustainability Policy Comparison
State-level sustainability policies are increasingly influencing investment strategies, product development, and material selection within the North America eco-friendly packaging market. Unlike regions operating under a unified regulatory framework, North America features a diverse policy landscape where individual U.S. states and Canadian provinces are enacting legislation aimed at reducing packaging waste, promoting recycled-content utilization, and enforcing producer responsibility. California is at the forefront with comprehensive regulations demanding reductions in single-use plastic packaging and setting ambitious targets for recycling and recycled-content.
Several states, including Oregon, Colorado, Maine, and Minnesota, have implemented Extended Producer Responsibility (EPR) programs that shift the financial burden of packaging collection and recycling from municipalities to manufacturers. Meanwhile, Canada is making strides toward nationwide packaging circularity through provincial EPR systems, with several provinces enhancing their blue-box recycling programs and establishing producer-funded recovery initiatives.
Currently, more than 75% of the U.S. population resides in states that have adopted at least one major packaging sustainability policy focused on recycled content, plastic reduction, or producer responsibility. This trend encourages manufacturers to standardize sustainable packaging across their national product lines. At the same time, over 30 U.S. states have enforced or expanded restrictions on select single-use plastic items, accelerating the shift toward recyclable, reusable, and fiber-based alternatives.
Beverage container deposit systems in 10 U.S. states are achieving higher recovery rates than traditional curbside collection, which enhances access to quality recycled PET and aluminum feedstocks. However, varying reporting requirements, labeling regulations, recycled-content standards, and compliance timelines introduce operational challenges for packaging manufacturers operating across multiple jurisdictions. To streamline production, cut compliance costs, and future-proof their product portfolios, companies are increasingly designing packaging that adheres to the most rigorous state regulations.
The growing alignment among industry associations, state governments, and recycling organizations is expected to enhance policy consistency over time. As sustainability legislation continues to evolve across North America, leadership at the state level will remain a crucial driver of innovation, investment, and competitive differentiation in the eco-friendly packaging market.
Competitive Landscape
Key companies analyzed within the North America eco friendly packaging market are: International Paper, Smurfit WestRock, Amcor, Sonoco Products Company, Sealed Air, Berry Global, Graphic Packaging International, Packaging Corporation of America (PCA), Pactiv Evergreen, Georgia-Pacific, Pratt Industries, Cascades Inc., Novolex, NatureWorks, Ball Corporation, Crown Holdings, O-I Glass, Dow, Eastman, Origin Materials and others.

Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) provides a comprehensive evaluation of participants in the North American eco-friendly packaging market. This framework utilizes a weighted, multi-dimensional methodology that considers both current competitive strength and long-term strategic readiness. Unlike other assessments that focus solely on revenue or market share, EICAF incorporates factors such as manufacturing scale, sustainable material capabilities, circular economy initiatives, innovation, regulatory preparedness, and customer reach, offering a holistic perspective on market leadership.
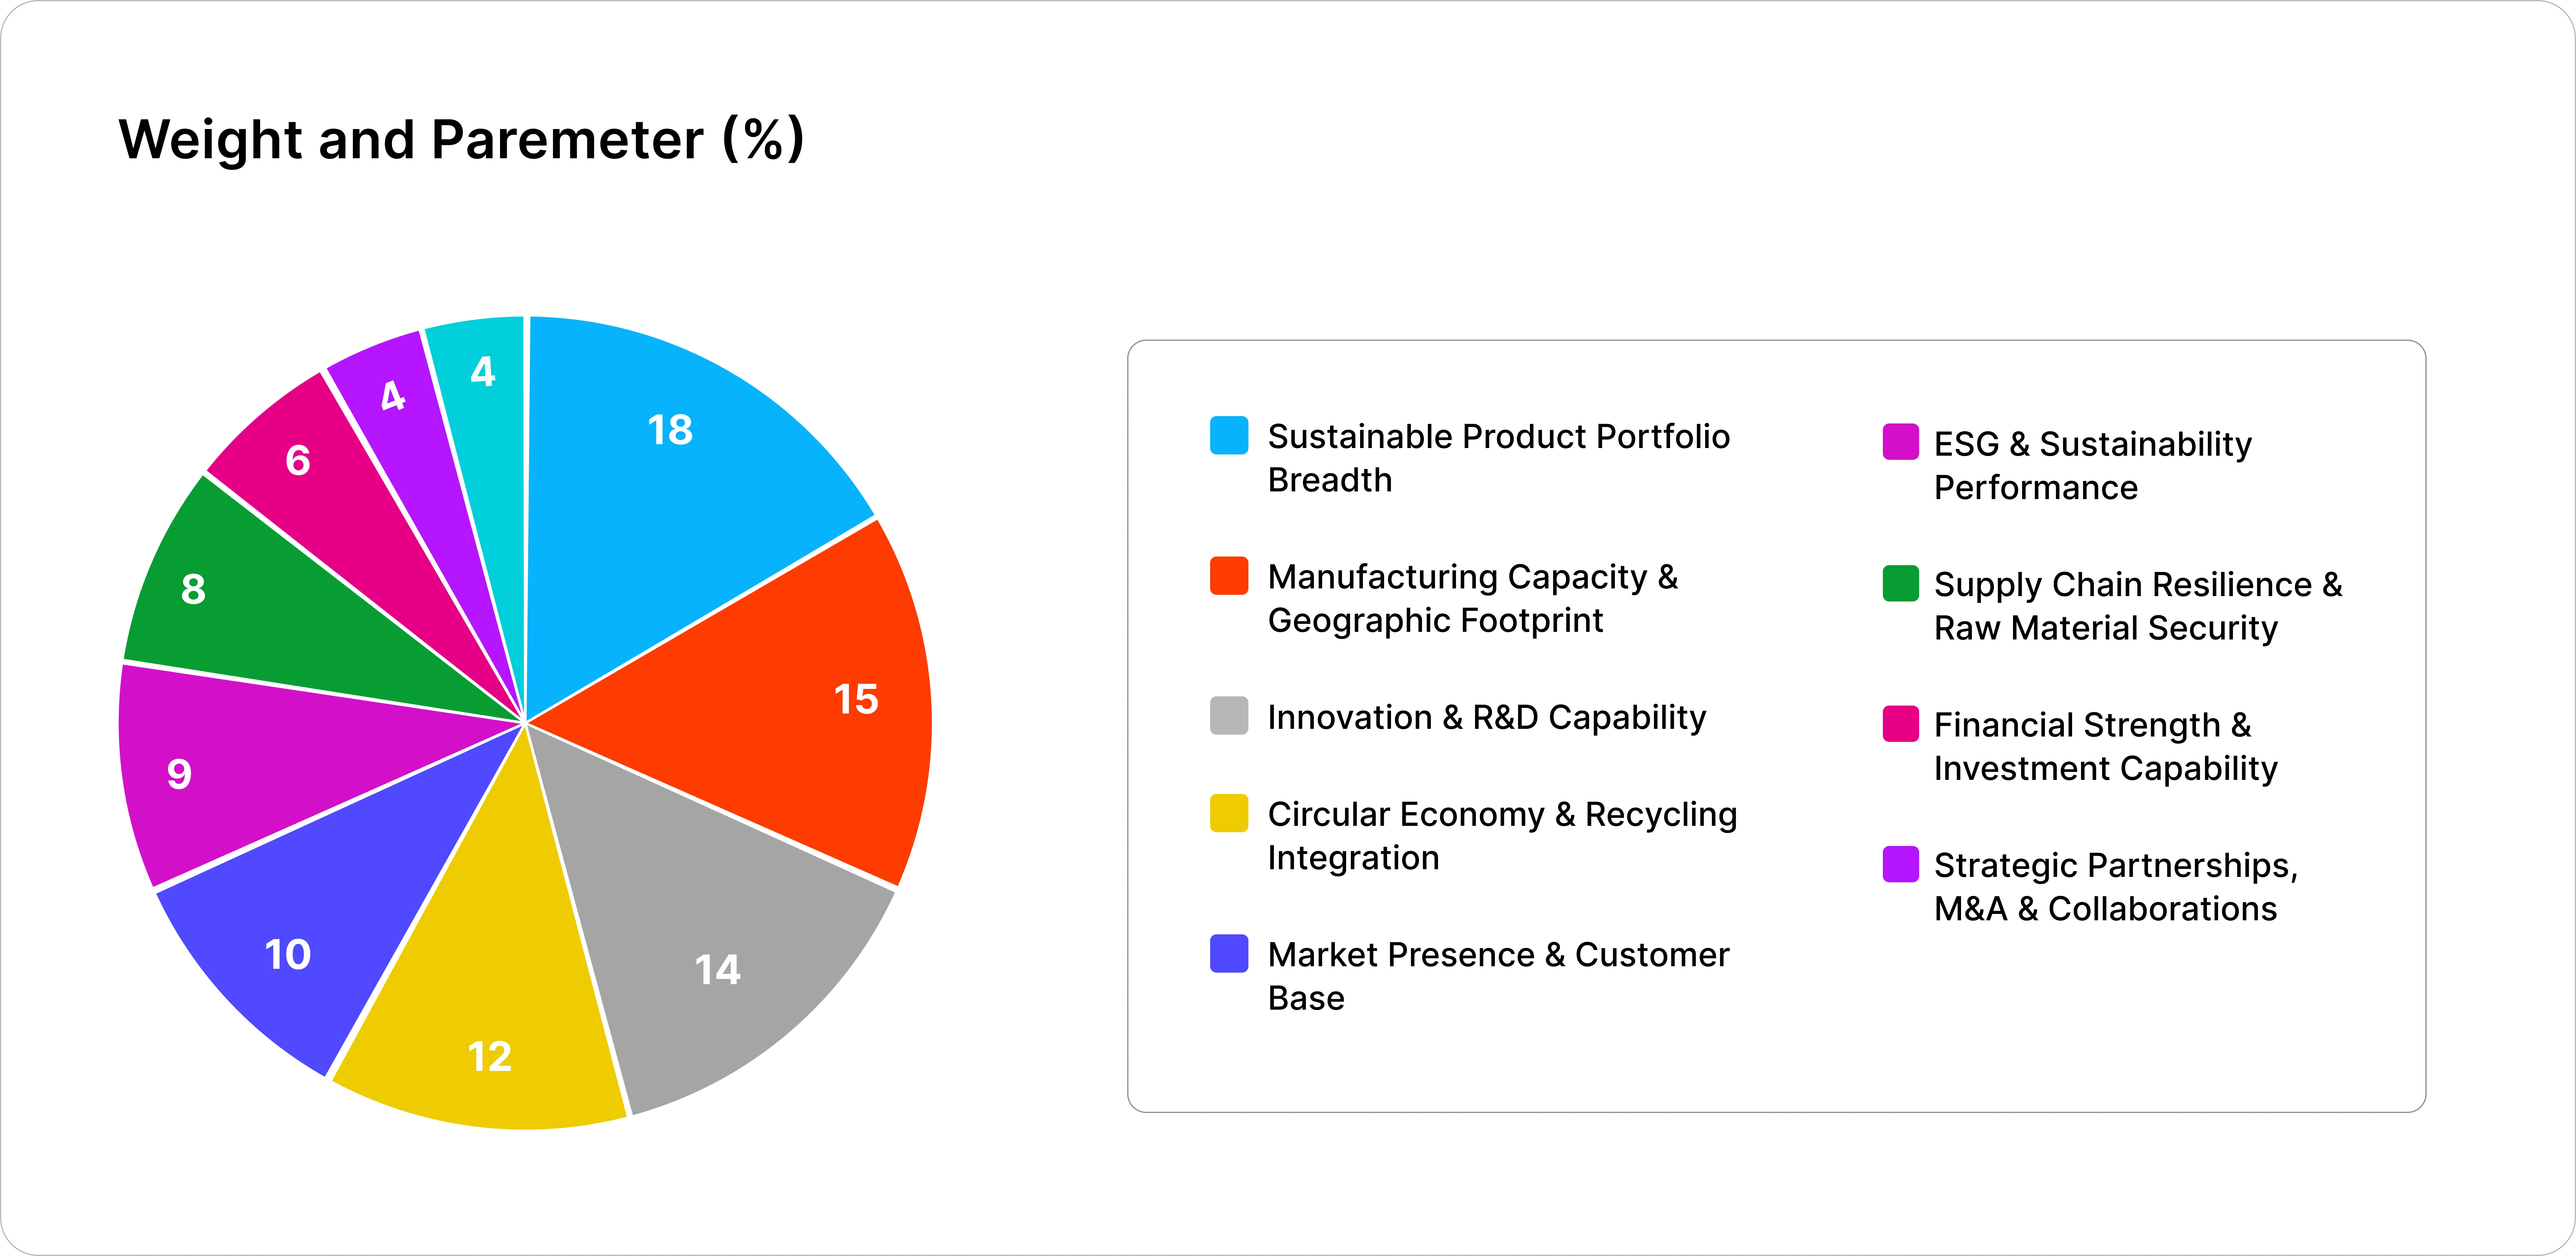
Companies that operate with vertically integrated processes, have strong recycling partnerships, and maintain diversified portfolios in paper, recycled plastics, bioplastics, glass, and metal packaging tend to achieve higher scores. Their diverse offerings allow them to effectively meet evolving customer demands across various industries. The framework also highlights the importance of investments in advanced recycling technologies, lightweight packaging design, bio-based materials, and digital manufacturing, all of which enhance resource efficiency and support corporate sustainability goals.
Furthermore, EICAF assesses geographic production coverage, supply chain resilience, and the stability provided by long-term procurement agreements for recycled feedstocks. It places additional emphasis on Environmental, Social, and Governance (ESG) performance, the speed of product commercialization, strategic partnerships, mergers and acquisitions, and the ability to adapt to changing packaging regulations across U.S. states and Canadian provinces.
By merging quantitative performance metrics with qualitative strategic considerations, the EICAF empowers investors, packaging manufacturers, raw material suppliers, and brand owners to benchmark competitors, identify capability gaps, prioritize partnership opportunities, and evaluate future growth potential within the rapidly evolving North American eco-friendly packaging market.

