Key Takeaways
- 18% of competitive strength in the Middle East Vertical Farming Market is driven by Technology Innovation & Automation Capability.
- 16% of market competitiveness depends on Commercial Farm Scale & Production Capacity.
- The top two assessment parameters account for 34% of the overall EICAF score in the Middle East Vertical Farming Market.
- 66% of the total competitive evaluation is concentrated in the top five assessment parameters, emphasizing operational and technological leadership.
- 12% of the framework evaluates Geographic Presence across key countries in the Middle East Vertical Farming Market.
- 20% of the total assessment is allocated to Product Portfolio Diversification and Strategic Partnerships, highlighting their role in market expansion.
Middle East Vertical Farming Market Outlook
Middle East Vertical Farming Market recorded a value of USD 396 million in 2025 and is estimated to reach a value of 1,116.5 million by 2033 with a CAGR of 14.0% during the forecast period, as per the analysis published by Epignosis Insights.
Middle East Vertical Farming Market Dynamics
The rising demand from premium retail chains for locally grown, pesticide-free vegetables is significantly driving the Middle East vertical farming market. This trend is particularly evident in countries like the United Arab Emirates, Saudi Arabia, and Qatar, where food retailers are reworking their strategies for fresh produce sourcing. Supermarkets, gourmet retailers, and organic food outlets are focusing on locally cultivated leafy greens, herbs, and microgreens to meet consumer preferences for freshness, traceability, and chemical-free production.
Unlike imported vegetables that typically travel between 2,000 and 8,000 kilometers often taking 5 to 10 days to reach retail shelves vertically farmed produce can be harvested and delivered within 24 to 48 hours. This rapid turnaround preserves nutritional value and extends shelf life while also reducing post-harvest losses, which account for nearly 14% of global food production before it reaches retail channels. As a result, the Middle East vertical farming market is becoming increasingly vital to improving food security in the region.
In the Gulf Cooperation Council (GCC) region, approximately 80 to 90 percent of fresh vegetables have historically been imported, making the supply chain vulnerable to logistics disruptions, fluctuating freight costs, and geopolitical uncertainties.
Consequently, major retailers are establishing long-term partnerships with local vertical farming operators to ensure a stable year-round supply. This strategy highlights the important role of the Middle East vertical farming market in providing consistent access to fresh produce.
Controlled-environment agriculture within the Middle East vertical farming market allows for pesticide-free cultivation via biosecure indoor systems and can reduce water consumption by 90 to 95 percent compared to traditional open-field farming an essential advantage in one of the world's most water-scarce areas. Additionally, premium retailers leverage locally sourced produce as a competitive differentiator, responding to a growing consumer willingness to pay higher prices for fresh, sustainably produced vegetables with transparent origin labeling.
High-value crops such as lettuce, kale, arugula, basil, spinach, and specialty herbs are particularly appealing due to their premium retail margins and fast production cycles of around 20 to 35 days under optimized indoor conditions. The expansion of luxury hospitality, gourmet dining, and health-conscious urban consumers further fuels the demand within the Middle East vertical farming market for consistent, high-quality locally produced vegetables year-round.
Consequently, procurement contracts driven by retail demand are prompting vertical farm operators to enhance production capacity, invest in automation, and diversify their crop offerings. This trend underscores the significance of premium retail demand as a primary factor in the growth of the Middle East vertical farming market, paving the way for commercial-scale vertical farming investments across the region.
Middle East Vertical Farming Market Product Matrix
Hydroponics Leads the Middle East Vertical Farming Market with Superior Commercial Viability
The product matrix for the Middle East Vertical Farming Market highlights hydroponics as the leading farming system, thanks to its established commercial viability, reduced operational complexity, and suitability for large-scale indoor cultivation.
This method is widely used in the United Arab Emirates and Saudi Arabia, as it can save up to 90–95% more water compared to traditional agriculture while consistently producing leafy greens, herbs, and specialty vegetables that are in high demand from premium retailers and hospitality chains. Hydroponics' integration with automated nutrient dosing, climate control, and AI-driven monitoring systems enhances its commercial appeal, making it the benchmark technology for new indoor farming investments in the region.
Aeroponics holds the second position in the market, providing superior oxygen delivery to plant roots and exceptional water-use efficiency, which makes it ideal for high-value crops where maximizing productivity per square meter is crucial. However, its higher installation costs, precision maintenance needs, and technical complexities currently limit its widespread commercial use compared to hydroponics.
Aquaponics sees moderate adoption, particularly in integrated food production projects that merge vegetable cultivation with aquaculture. Nonetheless, its commercial scalability faces challenges due to the necessity of maintaining a biological balance between fish and plant production systems.
Soil-based vertical farming remains a niche segment with limited market penetration, as natural growing media can hinder automation efficiency, increase water consumption, and yield lower planting densities than soilless cultivation methods.
In the Middle East Vertical Farming Market, investors are increasingly focusing on farming systems that ensure year-round production, rapid crop cycles, and reliable yields, even under extreme climatic conditions. As a result, hydroponics and aeroponics are expected to attract the majority of future commercial investments, bolstered by innovations in LED lighting, precision irrigation, robotic harvesting, and intelligent farm management platforms. With governments enhancing food security initiatives and promoting controlled-environment agriculture, technologies that maximize water productivity, resource efficiency, and operational scalability will continue to lead market growth across the region.
Segment & Country Analysis
By Component: Hardware Infrastructure Dominates Capital Investment in the Middle East Vertical Farming Market
The hardware segment stands out as the largest contributor to revenue in the Middle East Vertical Farming Market, encompassing the primary capital expenditures necessary for establishing and running commercial indoor farming facilities. Unlike software and service components, investments in hardware occur both during the initial setup of farms and during periodic technology upgrades, underscoring its essential role in market growth.
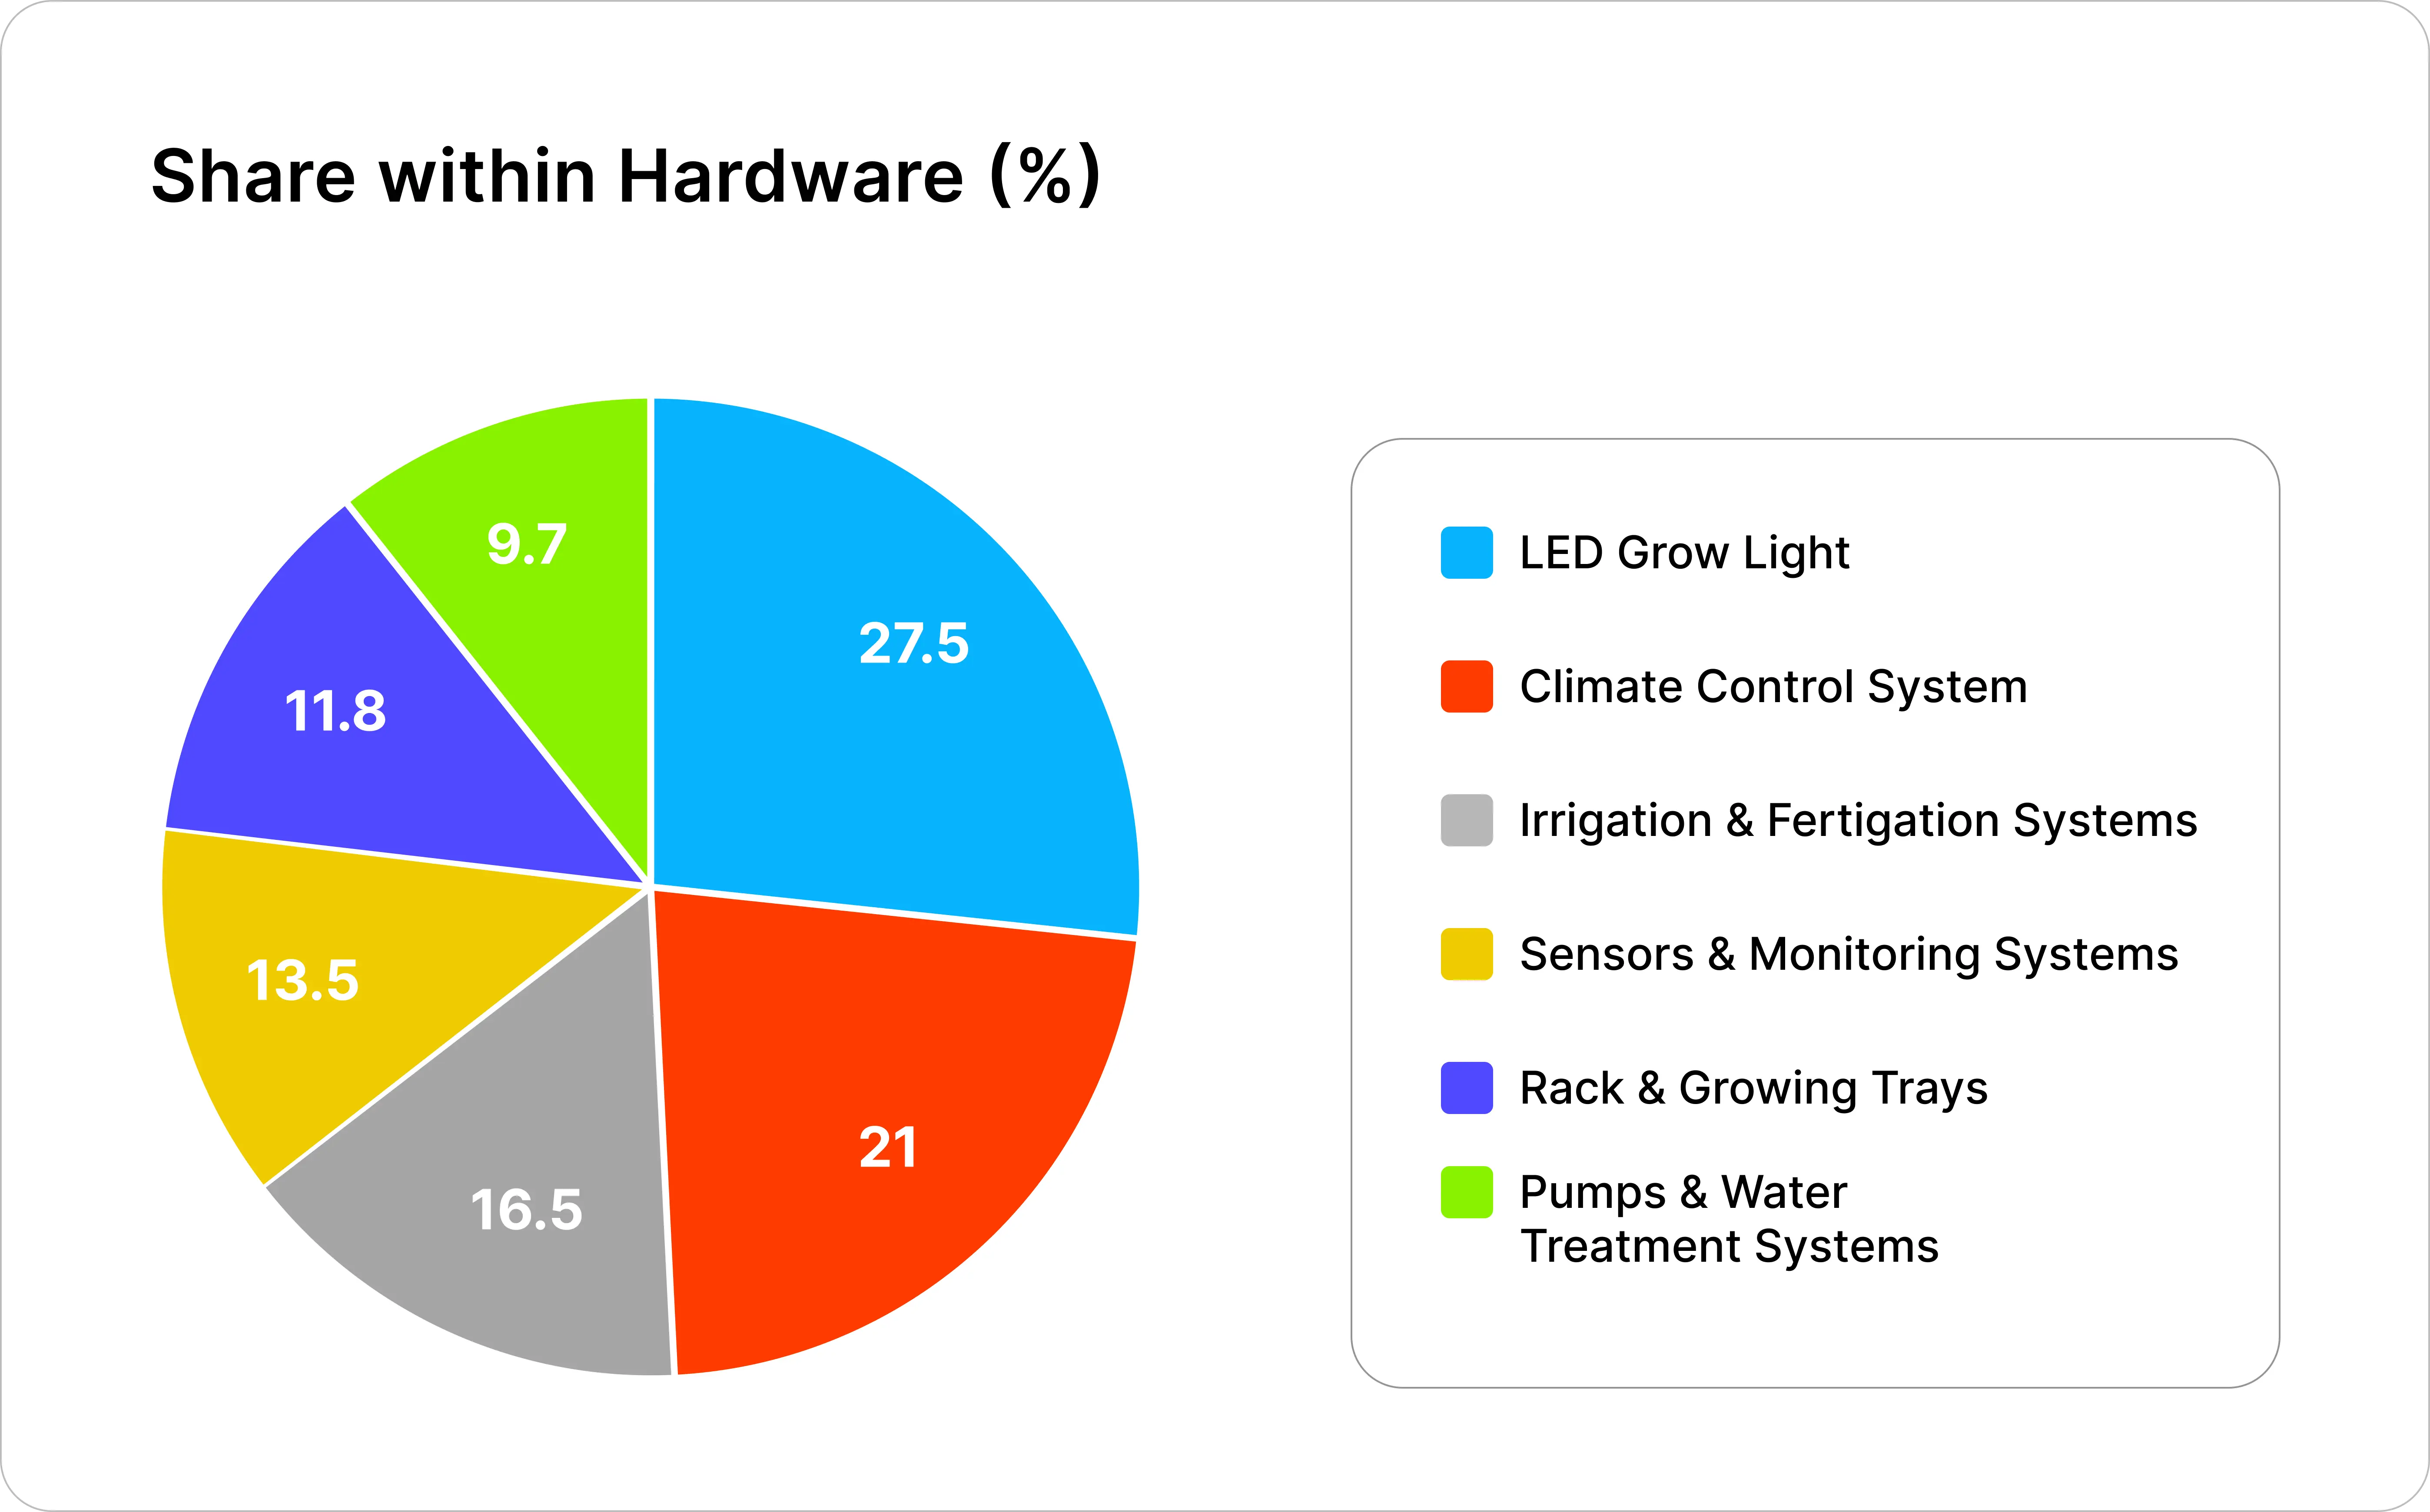
Within the hardware category, LED grow lights hold the largest share, thanks to their capability to deliver optimized light spectra for photosynthesis while cutting electricity consumption compared to traditional lighting systems. As electricity costs constitute a significant operating expense for indoor farmers, commercial operators in the UAE and Saudi Arabia are increasingly turning to high-efficiency LEDs that offer adjustable light intensity and spectrum control to enhance crop yields and accelerate growing cycles.
Climate control systems represent the second-largest hardware segment, highlighting the necessity of maintaining stable temperature, humidity, and CO₂ levels, especially when outdoor temperatures often soar above 45°C in summer. These systems facilitate year-round production of leafy greens, herbs, and specialty vegetables while protecting crops from harsh desert conditions.
Additionally, irrigation and fertigation systems account for a considerable portion of hardware expenditures, as both hydroponic and aeroponic farms depend on precise nutrient delivery to ensure uniform crop production and optimize water usage. Advanced pumps, filtration units, and water treatment equipment support recirculating irrigation systems that can lessen water consumption by up to 90–95% compared to conventional agricultural methods.
The adoption of sensors and monitoring systems is currently accelerating within the hardware segment, as growers increasingly implement real-time monitoring devices to track pH, electrical conductivity, dissolved oxygen, temperature, humidity, and nutrient concentration. This integration with automated control platforms enables predictive crop management and reduces the need for manual intervention.
Moreover, modular racks and growing trays are gaining popularity as commercial farms aim to maximize cultivation density within constrained urban environments. The trend toward standardized, scalable hardware architectures is further driving investments in prefabricated farming modules that facilitate easier facility expansion.
As government initiatives supporting food security and private investments in larger controlled-environment agriculture projects continue, the demand for advanced hardware systems is projected to remain a key revenue driver. This trend will further solidify the hardware segment's leading position in the Middle East Vertical Farming Market over the forecast period.
By Country: Saudi Arabia and the United Arab Emirates Account for the Largest Concentration of Commercial Vertical Farms
The landscape of commercial vertical farming in the Middle East is largely shaped by Saudi Arabia and the United Arab Emirates, which together account for over half of the region's operational facilities. Saudi Arabia takes the lead with the highest number of farms, driven by significant investments in national food security initiatives, the growth of controlled-environment agriculture, and the launch of commercial hydroponic and aeroponic farms aimed at reducing the reliance on imported fresh produce. The burgeoning urban population and the increasing demand for locally grown vegetables, along with advancements in irrigation technologies, continue to fuel the development of large-scale indoor farming projects.
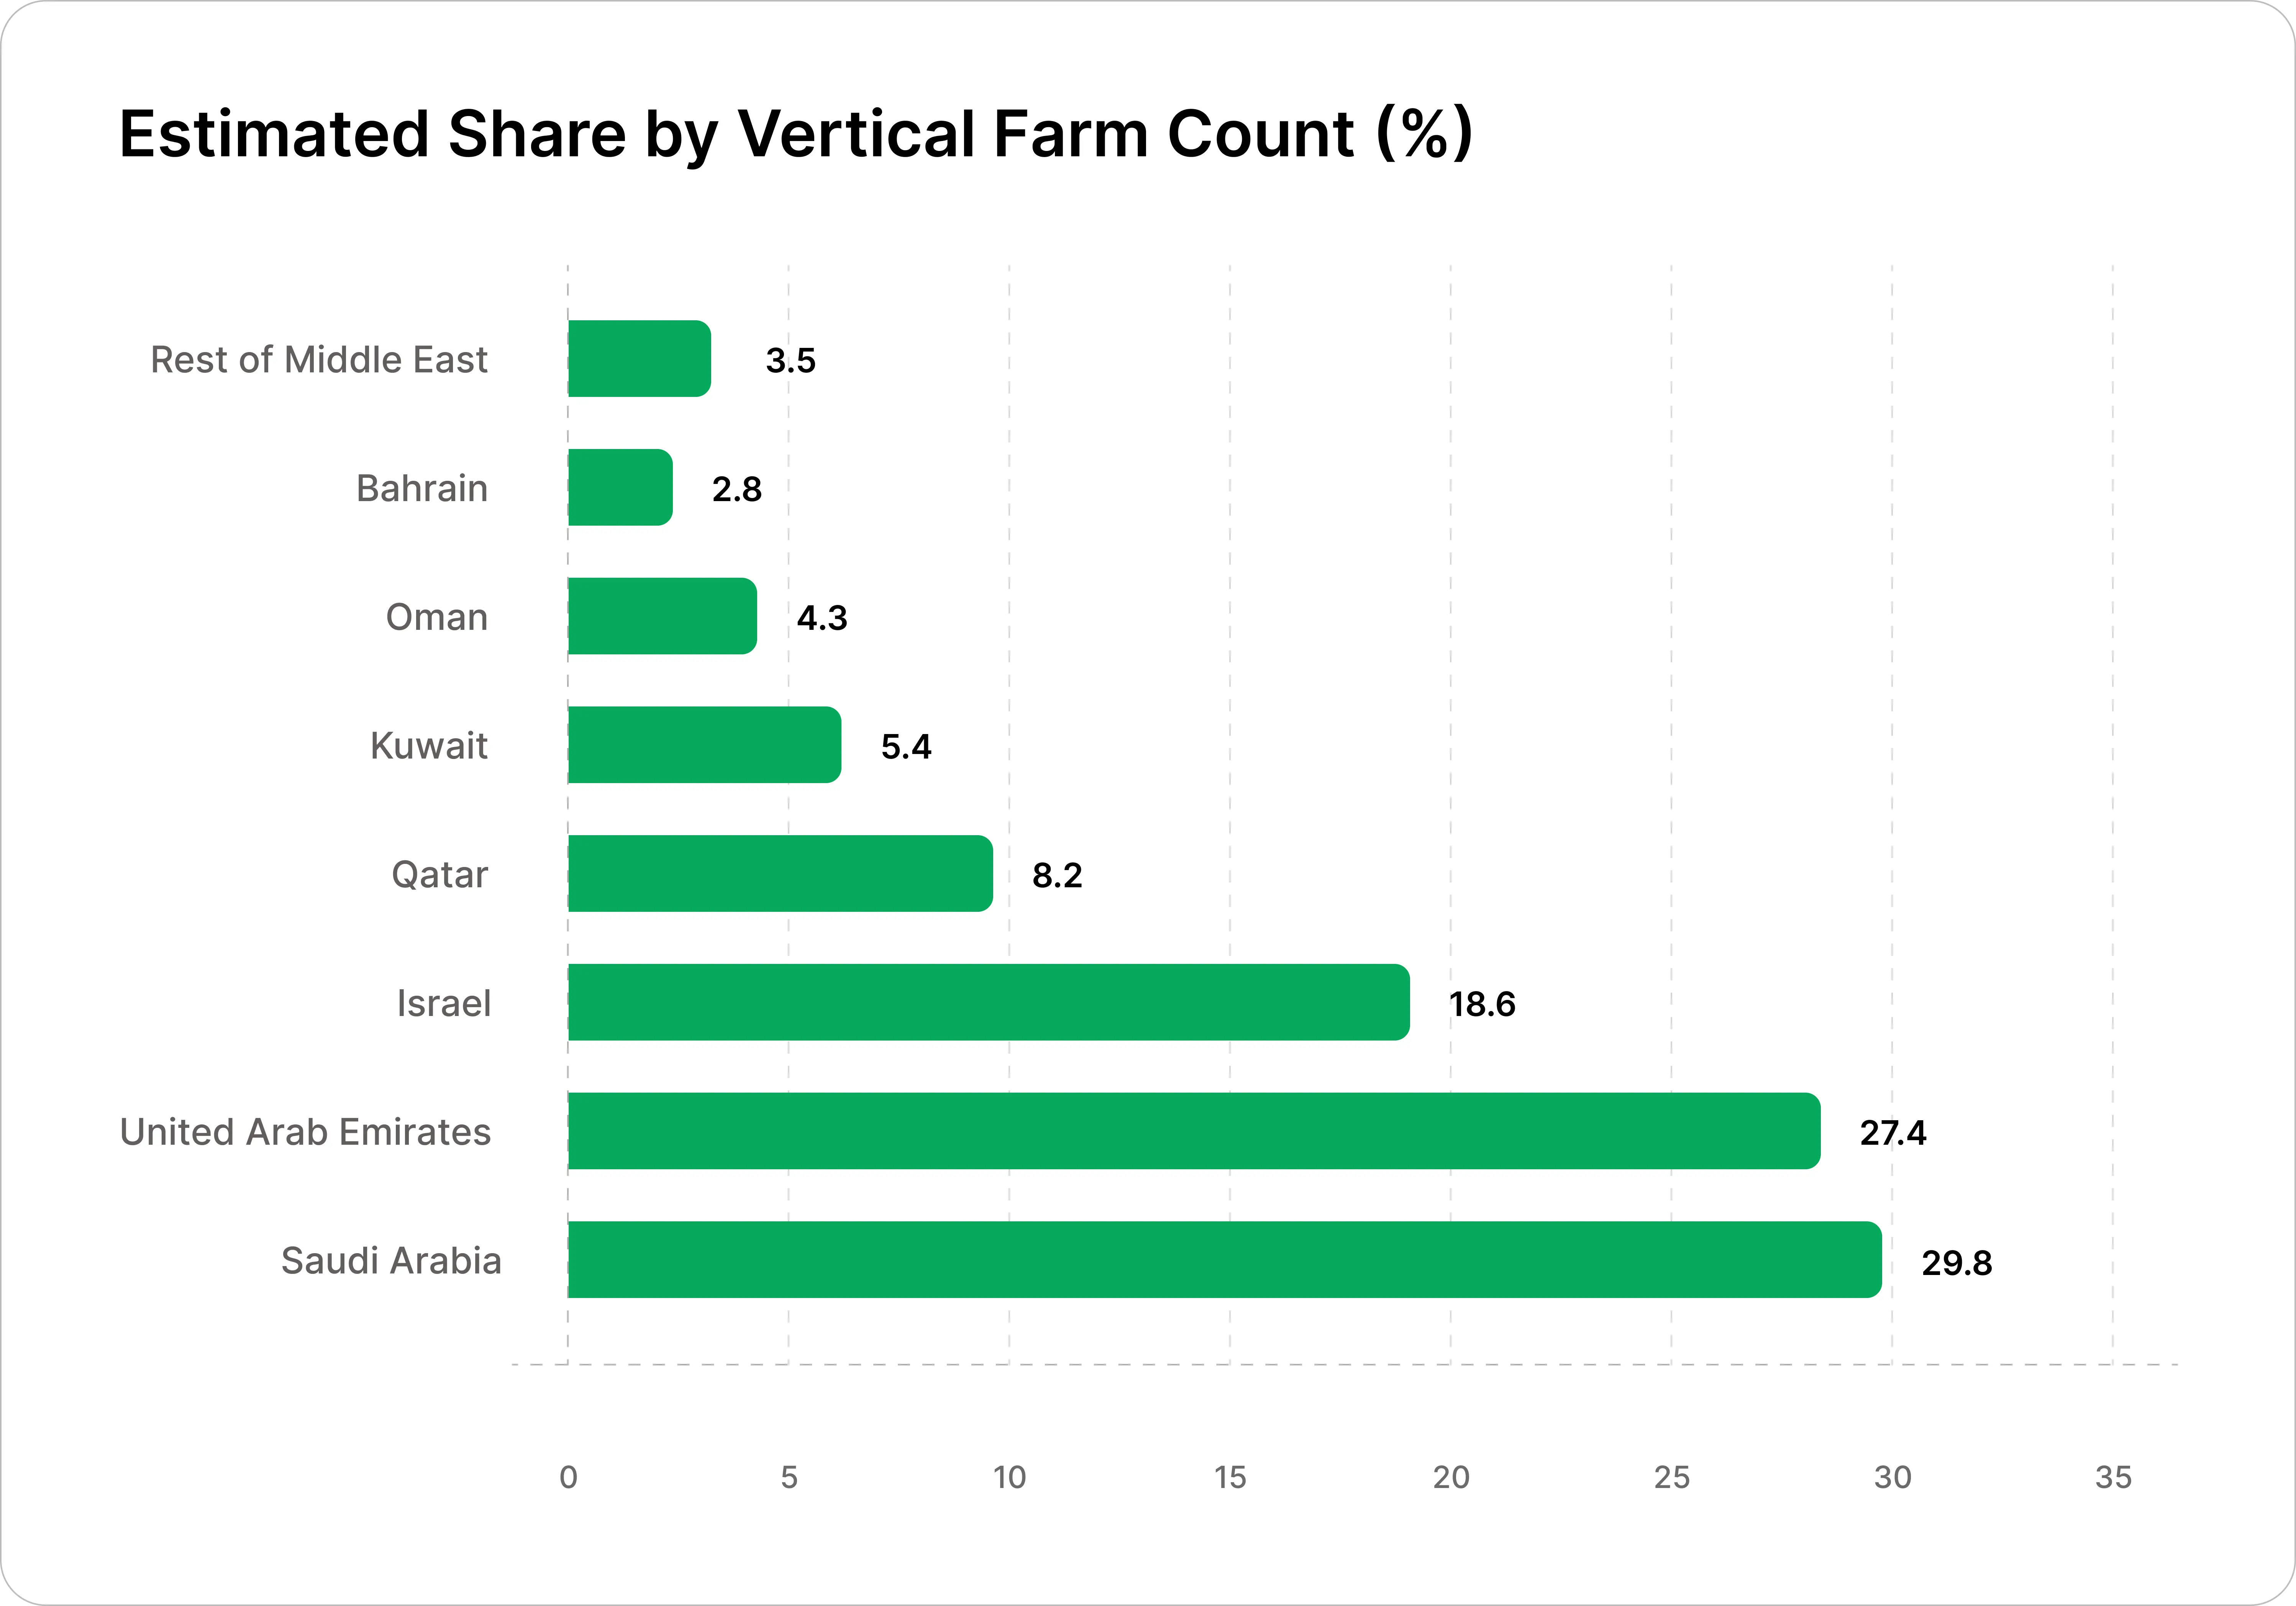
Following closely is the United Arab Emirates, which boasts a well-established AgriTech ecosystem, favorable investment policies, and a number of commercially successful vertical farms catering to supermarkets, premium retailers, and the hospitality sector. Israel ranks third, bolstered by its renowned agricultural technology industry and ongoing innovations in irrigation, automation, precision farming, and climate-controlled growing systems.
Qatar is also making strides, steadily increasing its number of commercial vertical farms to enhance domestic food production and bolster resilience against supply chain disruptions. In contrast, Kuwait, Oman, and Bahrain are emerging markets where the growth of vertical farming is primarily influenced by pilot projects, government-backed sustainable agriculture initiatives, and private investments in hydroponics.
Overall, the remaining countries in the Middle East account for a smaller share of operational farms, indicating that the market is still in its early stages of development. However, there is a rising trend in investments in water-efficient farming technologies and growing awareness of controlled-environment agriculture that are expected to expedite the establishment of commercial farms in these nations and gradually broaden the geographic reach of vertical farming in the region.
Competitive Analysis
Key companies analyzed within the Middle East vertical farming market are: Pure Harvest Smart Farms, Emirates Flight Catering, Madar Farms, VeggiTech Hydroponic Technologies, Badia Farms, Red Sea Farms, Emirates Hydroponics Farms, Vertical Field, iFarm, Others.
Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) serves as a tool for evaluating companies within the Middle East Vertical Farming Market. It emphasizes operational capabilities that contribute to long-term competitiveness rather than focusing solely on revenue or production volume. The framework assigns the highest weight of 18% to Technology Innovation & Automation Capability, highlighting its significance for commercial success in the region. This success hinges on the effective integration of AI-driven crop monitoring, precision irrigation, and automated nutrient dosing, robotics, and climate control systems that can sustain production in extreme desert conditions.
| Assessment Parameter |
Weight (%) |
| Technology Innovation & Automation Capability |
18 |
| Commercial Farm Scale & Production Capacity |
16 |
| Geographic Presence Across the Middle East |
12 |
| Product & Crop Portfolio Diversification |
10 |
| Strategic Partnerships & Retail Supply Agreements |
10 |
| Resource Efficiency (Water & Energy Optimization) |
9 |
| R&D and AgriTech Innovation |
8 |
| Financial Strength & Investment Capability |
7 |
| Supply Chain & Distribution Network |
5 |
| ESG & Sustainability Performance |
5 |
Following that, Commercial Farm Scale & Production Capacity is weighted at 16%, reflecting the ability of operators to consistently supply premium retailers, foodservice companies, and institutional buyers throughout the year. Geographic Presence, with a 12% weighting, assesses a company’s footprint across key regional markets such as Saudi Arabia, the United Arab Emirates, Israel, and Qatar, where government support and commercial adoption are notably strong.
Product & Crop Portfolio Diversification and Strategic Partnerships each receive a weight of 10%, underlining the importance of cultivating a variety of high-value crops and securing long-term agreements with supermarket chains, hotels, and restaurant groups. Resource Efficiency, weighted at 9%, looks at water recycling, energy optimization, and yield per square meter essential factors in water-scarce environments.
Moreover, the framework considers R&D capability, financial strength, supply chain resilience, and ESG performance collectively, as these elements reflect a company's ability to commercialize new cultivation technologies, finance growth, maintain continuous product availability, and adhere to regional sustainability goals. Overall, EICAF provides a comprehensive methodology for benchmarking both established operators and emerging AgriTech companies in the Middle East Vertical Farming Market, enabling an objective comparison across strategic, operational, technological, and sustainability dimensions.
Related Insights
Vertical Farming and Food Security in the Middle East
Top Vertical Farming Companies in the Middle East (2026)
Hydroponics vs. Aeroponics vs. Aquaponics in the Middle East
Circular Economy and the Future of Middle East Vertical Farming

