Key Findings
- Power semiconductor devices account for approximately 55–60% of total market revenue, supported by strong adoption in consumer electronics, electric vehicles, industrial automation, and renewable energy systems.
- GaN devices reduce switching losses by 40–80% and enable operating frequencies exceeding 1 MHz, significantly outperforming conventional silicon MOSFETs in high-efficiency power conversion.
- USB-C GaN chargers ranging from 65 W to 240 W are driving high-volume shipments, with GaN-based adapters being 30–50% smaller than equivalent silicon-based designs.
- China and the United States together represent approximately 53% of global GaN semiconductor consumption, driven by AI infrastructure, 5G deployment, EV production, and advanced electronics manufacturing.
- Japan, South Korea, and Taiwan collectively contribute around 25% of global demand, leveraging their leadership in semiconductor fabrication, automotive electronics, and consumer devices.
Global Gallium Nitride Semiconductor Market Outlook
Gallium Nitride Semiconductor Market recorded a demand of 2,580 million units in 2025 and is estimated to reach a volume of 19,904 million units by 2033 with a CAGR of 29.5% during the forecast period.
Global Gallium Nitride Semiconductor Market Dynamics
Transition from silicon MOSFETs to GaN for higher switching frequencies and reduced energy losses
The transition from conventional silicon MOSFETs to gallium nitride (GaN) devices is fundamentally reshaping the landscape of power electronics. This shift enables significantly higher switching frequencies, reduced conduction losses, and enhanced power density across various sectors, including consumer electronics, industrial applications, automotive, and data centers. Unlike silicon MOSFETs, which typically operate efficiently in the tens to hundreds of kilohertz range for many high-power applications, GaN devices can achieve switching frequencies exceeding 1 MHz while maintaining substantially lower switching losses. This capability allows engineers to reduce the size of transformers, inductors, and capacitors by 30–70%, depending on the system architecture.
GaN transistors feature near-zero reverse recovery charge and lower gate charge, leading to switching losses that can be reduced by 40–80% compared to similar silicon solutions in high-frequency power conversion circuits. These enhancements prove especially valuable for USB-C fast chargers, where manufacturers are now capable of delivering 65 W, 100 W, 140 W, and even 240 W charging solutions in compact designs that were previously unrealistic with silicon MOSFET technology.
The momentum is also growing in AI servers and hyperscale data centers, where even a slight improvement of 1–2% in power supply efficiency can result in millions of kilowatt-hours of annual energy savings across large-scale facilities. In the realm of electric vehicles, GaN-based onboard chargers and DC-DC converters are enabling the development of lighter, smaller, and more efficient power electronics, contributing to longer driving ranges and enhanced thermal performance.
Similarly, industrial motor drives, renewable energy inverters, and telecommunications power supplies are benefiting from GaN's ability to achieve efficiency levels exceeding 98% in optimized designs, while simultaneously reducing cooling requirements and overall system weight.
As wafer manufacturing progresses toward larger 8-inch GaN-on-silicon production and fabrication yields continue to improve, the cost gap between silicon and GaN technologies is steadily closing. This trend makes the adoption of GaN economically viable across higher shipment volumes. These technological and manufacturing advancements are expected to act as a significant catalyst for the Global Gallium Nitride Semiconductor Market, as original equipment manufacturers increasingly transition from silicon MOSFETs to GaN devices. This transition aims to achieve superior energy efficiency, enhanced switching performance, and lower total system costs in next-generation electronic systems.
High manufacturing costs associated with defect-free GaN epitaxial wafer production
One of the most significant barriers to widespread commercialization in the Global Gallium Nitride Semiconductor Market is the high manufacturing cost associated with producing defect-free GaN epitaxial wafers. This cost directly impacts device yield, reliability, and overall production economics. Unlike conventional silicon wafers, GaN epitaxial layers are typically produced using advanced techniques such as Metal-Organic Chemical Vapor Deposition (MOCVD) on substrates like silicon, silicon carbide (SiC), or sapphire. The manufacturing process demands extremely precise control over temperature, gas flow, pressure, and crystal growth conditions to minimize issues such as threading dislocation densities, wafer bowing, cracking, and lattice mismatch.
Even minor crystal defects can lead to significant reductions in breakdown voltage, increased leakage current, and shorter device lifetimes, making yield optimization a key challenge for manufacturers. High-performance power and RF applications often require defect densities below 10⁶ defects/cm², which calls for sophisticated process controls and extensive wafer inspections. The cost of a single MOCVD production tool ranges from US$2–5 million, and establishing a commercial GaN fabrication line can require investments that reach hundreds of millions of dollars when factoring in cleanroom infrastructure, metrology systems, and process equipment.
Additionally, the production of GaN epitaxy involves the use of expensive precursor gases like trimethylgallium (TMGa) and ammonia, which further increases manufacturing costs. Wafer yields continue to be lower than those seen in mature silicon production, especially for larger-diameter wafers, leading to a higher cost per functional device despite ongoing improvements in processes. While the industry is gradually transitioning from 6-inch to 8-inch GaN-on-silicon wafers, scaling production while maintaining low defect densities remains a technically challenging task.
Every percentage point improvement in wafer yield can significantly reduce manufacturing costs and enhance profitability, driving continuous investment in epitaxial process optimization, in-line defect inspection, and advanced wafer characterization technologies. Moreover, manufacturers are investing in AI-assisted process monitoring and automated quality control to improve crystal uniformity and decrease production variability. Until defect-free and high-volume GaN wafer manufacturing achieves cost levels closer to those of silicon semiconductor production, manufacturing economics will continue to be a primary constraint affecting pricing, supply expansion, and competitive dynamics within the Global Gallium Nitride Semiconductor Market.
Global Gallium Nitride Semiconductor Market Cross Segment Analysis
Power Semiconductor Devices Lead Multi-Industry Adoption Across the Global Gallium Nitride Semiconductor Market
The cross-segment analysis indicates that Power Semiconductor Devices are the leading contributors to both revenue and volume in the Global Gallium Nitride Semiconductor Market. This trend is particularly evident in sectors such as consumer electronics, electric vehicles, renewable energy systems, industrial automation, data centers, and EV charging infrastructure. The consumer electronics sector continues to dominate shipment volumes as GaN technology has become standard in USB-C fast chargers with power ratings of 65 W, 100 W, 140 W, and 240 W. These chargers enable power adapters that are up to 50% smaller, achieving efficiencies that exceed 95–96%.
In the electric vehicle segment, GaN power devices are increasingly being integrated into onboard chargers and DC-DC converters operating between 400 V and 800 V battery architectures, resulting in a reduction of power losses by 30–50% compared to traditional silicon solutions. Hyperscale data centers are also rapidly adopting GaN power supplies to improve energy conversion efficiency by 1–3 percentage points. While this may seem like a modest enhancement, it translates to substantial reductions in electricity consumption and cooling costs for multi-megawatt facilities.
RF Semiconductor Devices are experiencing their strongest penetration in telecommunications and aerospace & defense applications, thanks to GaN’s high electron mobility, which allows operation at frequencies above 30 GHz with superior power density. This is particularly beneficial for 5G massive MIMO base stations, satellite communications, phased-array radar, and electronic warfare systems.
Optoelectronic Devices remain relatively niche but are seeing increased adoption in healthcare, where GaN-based ultraviolet LEDs are being utilized for sterilization, medical diagnostics, and laboratory instrumentation, as well as for aerospace sensing applications. Additionally, GaN Integrated Circuits (ICs) are emerging as one of the fastest-growing categories in the market. They integrate power transistors, gate drivers, and protection circuitry into compact monolithic solutions, which reduces component count, PCB footprint, and overall system costs while enhancing reliability.
The acceleration in the adoption of GaN ICs spans consumer electronics, industrial power supplies, telecom infrastructure, and AI server power architectures. This cross-segment demand pattern reveals that while consumer electronics drive shipment volumes, sectors like telecommunications, data centers, automotive electrification, and defense applications generate higher average selling prices and greater profitability. Collectively, these factors contribute to a diversified demand base that bolsters the long-term growth prospects of the Global Gallium Nitride Semiconductor Market.
Global Gallium Nitride Semiconductor Market Regional Pockets
How AI Infrastructure, EVs, and 5G Deployment Are Reshaping Regional Demand in the Global Gallium Nitride Semiconductor Market
The Global Gallium Nitride Semiconductor Market is experiencing concentrated consumption in countries with robust semiconductor ecosystems, advanced manufacturing capabilities, and rapidly evolving electrification initiatives. The United States stands out as the largest consumer, thanks to its leadership in AI computing, hyperscale cloud infrastructure, defense modernization, and aerospace technologies. Hyperscale operators are significantly investing in AI-ready data centers, where GaN-based power supplies enhance energy efficiency and minimize cooling requirements.
China is a close contender, bolstered by its dominance in smartphone production, exports of consumer electronics, electric vehicle manufacturing, and the swift deployment of 5G infrastructure. The country produces over 30 million vehicles annually, and its extensive electronics manufacturing base drives considerable demand for compact, high-efficiency GaN power devices.
Japan, South Korea, and Taiwan together constitute the world’s most advanced semiconductor manufacturing cluster, supplying essential GaN devices for automotive electronics, sophisticated industrial equipment, AI servers, and high-end consumer electronics. Taiwan's foundry ecosystem and South Korea's prowess in memory semiconductors and smartphones further enhance regional consumption.
In Europe, Germany leads the demand due to its automotive, industrial automation, and renewable energy sectors, where GaN technology contributes to high-efficiency inverters, onboard chargers, and factory automation equipment. France and the United Kingdom also generate stable demand from aerospace, satellite communications, radar systems, and defense electronics, which require high-performance RF GaN devices capable of operating at elevated frequencies and power densities.
India is emerging as one of the fastest-growing markets for consumption, driven by the expansion of electronics manufacturing, government-supported semiconductor initiatives, a nationwide rollout of 5G, and increasing adoption of electric vehicles. As investments in AI infrastructure, renewable energy integration, industrial digitalization, and high-speed communication networks continue to surge worldwide, these regional hubs are expected to remain the principal demand centers. They will significantly influence production strategies, supply chains, and long-term growth opportunities within the Global Gallium Nitride Semiconductor Market.
Company Analysis
Key companies analyzed within the global gallium nitride semiconductor market are: Infineon Technologies AG, Navitas Semiconductor Corporation, Efficient Power Conversion Corporation (EPC), Qorvo, Inc., MACOM Technology Solutions Holdings, Inc., Innoscience Technology, Nexperia B.V., STMicroelectronics N.V., ROHM Co., Ltd. And others.
Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) is designed to evaluate participants in the Global Gallium Nitride Semiconductor Market, placing the greatest emphasis on GaN technology and device portfolio (18%) as well as manufacturing capacity and wafer production (15%). These elements are crucial for determining long-term competitiveness and commercial scalability. Companies that possess extensive portfolios encompassing power devices, RF semiconductors, optoelectronics, and GaN integrated circuits are in a stronger position to meet the demands from various sectors, including consumer electronics, automotive, telecommunications, industrial automation, AI data centers, and aerospace.
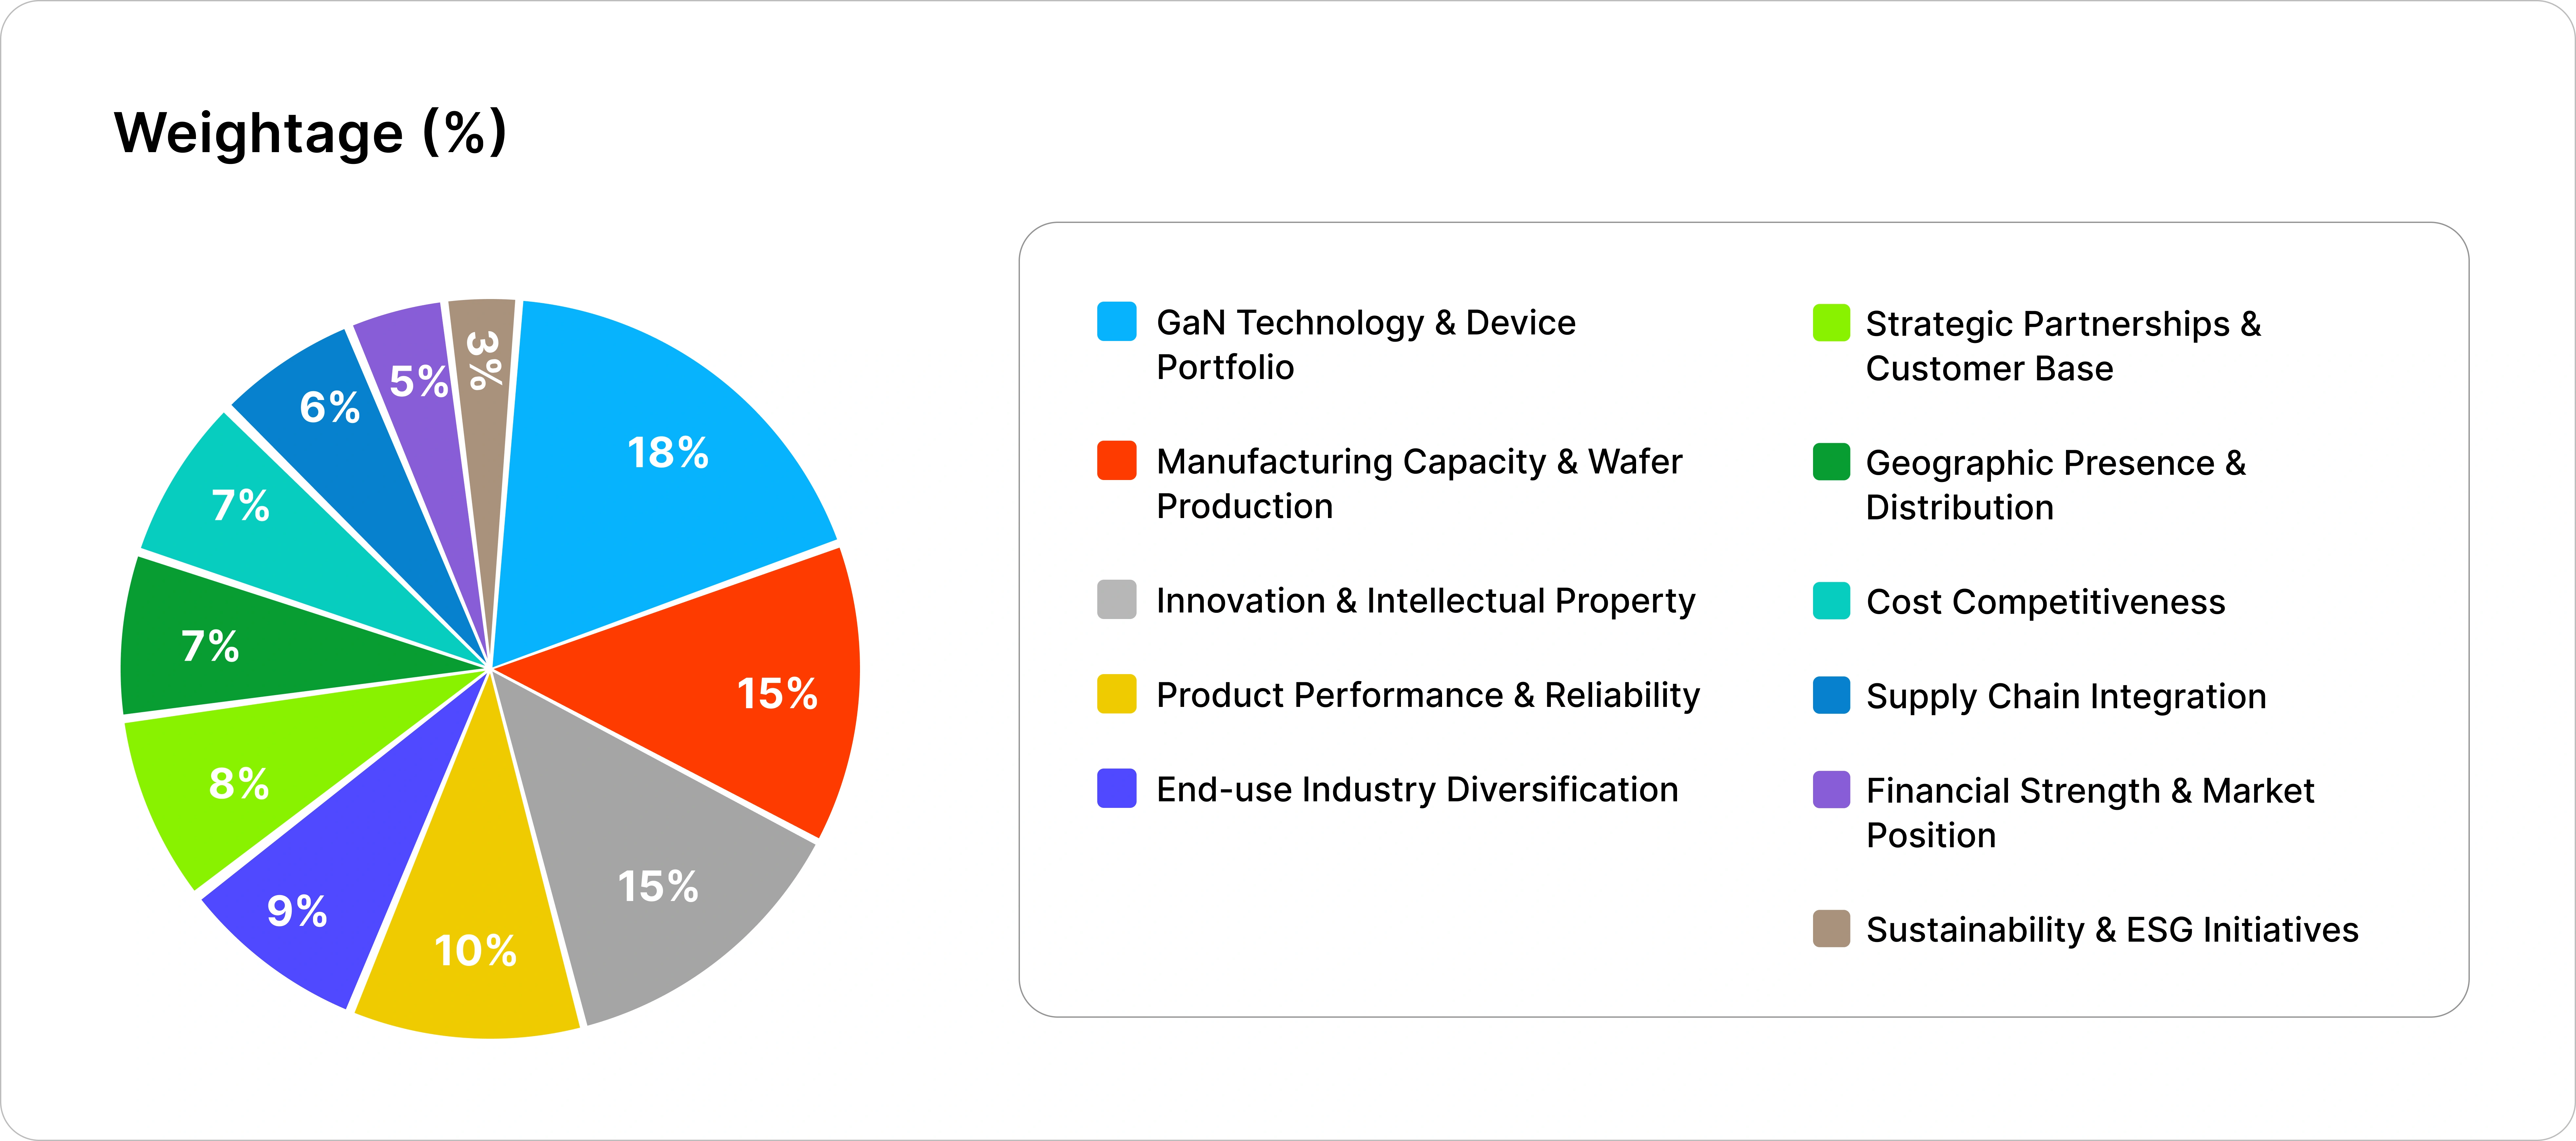
Manufacturing capability is likewise vital, as the ability to produce high-yield epitaxial wafers and the shift towards 8-inch GaN-on-silicon wafers significantly impact production costs, supply reliability, and gross margins. The framework also recognizes the importance of innovation and intellectual property (12%), highlighting how proprietary device architectures, epitaxial processes, packaging technologies, and patent strength contribute to maintaining technological differentiation.
The assessment measures product performance and reliability (10%) based on efficiency, switching frequency, thermal characteristics, and the qualification standards necessary for automotive and industrial applications. End-use industry diversification (9%) and strategic partnerships (8%) evaluate a company's capability to secure long-term agreements with OEMs, cloud infrastructure providers, automotive manufacturers, and telecom equipment suppliers. Factors like geographic presence (7%), cost competitiveness (7%), and supply chain integration (6%) are considered essential for resilience against regional disruptions while fulfilling global customer demands. Lastly, financial strength (5%), sustainability initiatives (3%), and after-sales technical support (3%) gauge an organization’s investment ability, regulatory preparedness, and customer engagement.
Together, these weighted parameters create a comprehensive framework for benchmarking established semiconductor manufacturers and emerging GaN specialists, facilitating an objective comparison of competitive positioning, innovation potential, operational efficiency, and future growth opportunities within the Global Gallium Nitride Semiconductor Market.

