Key Takeaways
- Europe's military drone market is projected to grow from 4,800 units in 2024 to 11,846 units by 2033, registering a 10.87% CAGR (2027–2033), driven by increasing procurement of tactical, ISR, and AI-enabled UAVs.
- The 5–25 kg payload segment leads the market with a 36.7% share, supported by strong demand for reconnaissance, border surveillance, and multi-mission tactical operations.
- The United Kingdom (18.6%), France (16.9%), and Germany (14.8%) account for nearly 50% of the AI-enabled military drone market, backed by advanced defense industries and autonomous UAV development.
- BAE Systems, Airbus Defence & Space, Leonardo, Thales, and Safran Electronics & Defense dominate strategic UAV programs, while Tekever, Delair, and Alpha Unmanned Systems strengthen competition in tactical and VTOL drone segments.
- AI-enabled autonomy, autonomous target recognition, sensor fusion, and anti-jamming technologies are becoming the primary competitive differentiators across Europe's military drone market.
- Growing indigenous manufacturing, NATO interoperability, and collaborative European defense programs are accelerating adoption of modular, multi-mission military drone platforms.
Europe Military Drones Market Outlook
Europe Military Drones Market recorded a sales volume of 5,300 units in 2025 and is estimated to reach a volume of 11,846 units by 2033 with a CAGR of 10.87% during the forecast period, according to Epignosis Insights.
Europe Military Drones Market Dynamics
The growing integration of AI-based autonomous target recognition (ATR) is emerging as a significant technological driver for the European military drone market. Armed forces are increasingly aiming to reduce sensor-to-shooter timelines while enhancing target identification accuracy in complex operational settings. Unlike traditional image-processing systems, AI-enabled ATR utilizes a combination of deep learning, computer vision, electro-optical/infrared (EO/IR) sensors, and synthetic aperture radar (SAR) imagery to autonomously detect, classify, prioritize, and track military assets in real time. This capability proves particularly advantageous in contested electromagnetic environments, where operators need to manage thousands of images and video feeds simultaneously.
Insights gained from the Russia–Ukraine conflict have notably sped up investments in AI-enabled unmanned systems designed to recognize armored vehicles, artillery, air-defense systems, and maritime targets with minimal operator involvement. In response to these developments, the European Defence Agency has prioritized autonomous systems within its capability development strategy, launching the Action Plan on Autonomous Systems (APAS) in 2024 to expedite the deployment of highly autonomous air, land, maritime, and cross-domain unmanned platforms. This includes a focus on cooperative autonomy and manned-unmanned teaming (MUM-T). The agency emphasizes artificial intelligence, advanced computing, robotics, and networked systems as core enabling technologies for next-generation European defense capabilities.
Additionally, the European Commission is enhancing the regional AI ecosystem through the European Defence Fund, which finances collaborative defense research and development projects like the STORE (Shared daTabase for Optronics image Recognition and Evaluation) program led by Thales. This initiative aims to develop extensive, standardized image databases and AI algorithms to improve the automatic recognition of military objects by optronic sensors, thereby directly supporting autonomous target recognition in drones and other defense platforms.
Moreover, while the EU's AI Act exempts systems created solely for military purposes, it simultaneously fosters broader AI innovation, trustworthy AI development, and investments throughout the European technology landscape. This enables defense manufacturers to harness advancements in dual-use AI, machine vision, and edge computing. As European armed forces increasingly demand AI-enabled ISR drones with capabilities for autonomous object recognition, target prioritization, and multi-sensor data fusion, manufacturers are incorporating onboard AI processors. This aims to reduce operator workload, accelerate decision-making, and enhance mission effectiveness. The shift from remotely piloted surveillance platforms to AI-assisted autonomous reconnaissance systems is projected to remain one of the strongest catalysts for growth in the European military drone market over the next decade.
Europe Military Drones Market Product Matrix
Competitive Positioning Highlights Strong ISR and AI-Enabled Platform Portfolios
The Europe military drones product matrix illustrates a competitive landscape dominated by established defense prime contractors, particularly in high-value strategic platforms, while specialized manufacturers excel in tactical and mission-specific UAV segments. Companies like Airbus Defence & Space and Leonardo boast the most extensive portfolios, providing capabilities across MALE platforms, ISR missions, maritime surveillance, AI-powered autonomy, and electronic warfare integration, which positions them as essential suppliers for multi-domain defense modernization initiatives.
Thales and Safran Electronics & Defense set themselves apart with their advanced mission systems, optronics, secure communications, navigation, and payload technologies, rather than focusing solely on complete UAV platforms. This specialization makes them vital technology partners for the European drone ecosystem. Meanwhile, firms such as Quantum-Systems, WB Group, Tekever, and Primoco UAV have carved out significant roles in tactical fixed-wing and border surveillance drones. Their success is driven by the need for rapidly deployable, cost-effective ISR platforms, especially relevant in light of recent security challenges across Europe.
Schiebel has achieved a unique competitive edge in VTOL and maritime UAV applications, where the need for runway-independent deployment is crucial for shipborne operations and infrastructure monitoring. The matrix also reveals that combat UAVs and loitering munitions are relatively underrepresented among European manufacturers, a reflection of the region's historical focus on reconnaissance, intelligence gathering, and border security over offensive unmanned strike capabilities.
Furthermore, the integration of AI-enabled autonomous functions, secure data links, multi-payload integration, and swarm-enabling technologies is becoming increasingly pivotal across manufacturers. This trend marks a shift in competition from basic airframe development to enhanced software capabilities, sensor fusion, resilient communications, and mission autonomy. As a result, collaboration is expected to grow between airframe manufacturers, electronics suppliers, and AI developers, as European defense programs focus more on interoperable, modular, and mission-adaptable drone ecosystems rather than solely single-purpose UAV platforms.
Segment & Regional Analysis
By Payload Capacity: Medium-Payload Military Drones Dominate European Procurement through Multi-Mission Operational Flexibility
The 5–25 kg payload , primarily due to its versatility in supporting various operational needs while ensuring high mobility and lower deployment costs. Drones in this range typically carry electro-optical/infrared (EO/IR) sensors, laser designators, electronic intelligence payloads, communication relay equipment, and compact synthetic aperture radar systems, all without the need for specialized launch infrastructure. Their effectiveness for platoon- and brigade-level intelligence, surveillance, and reconnaissance (ISR) missions has led to significant procurement by European armed forces, particularly as they enhance situational awareness along NATO's eastern borders and maritime security zones.
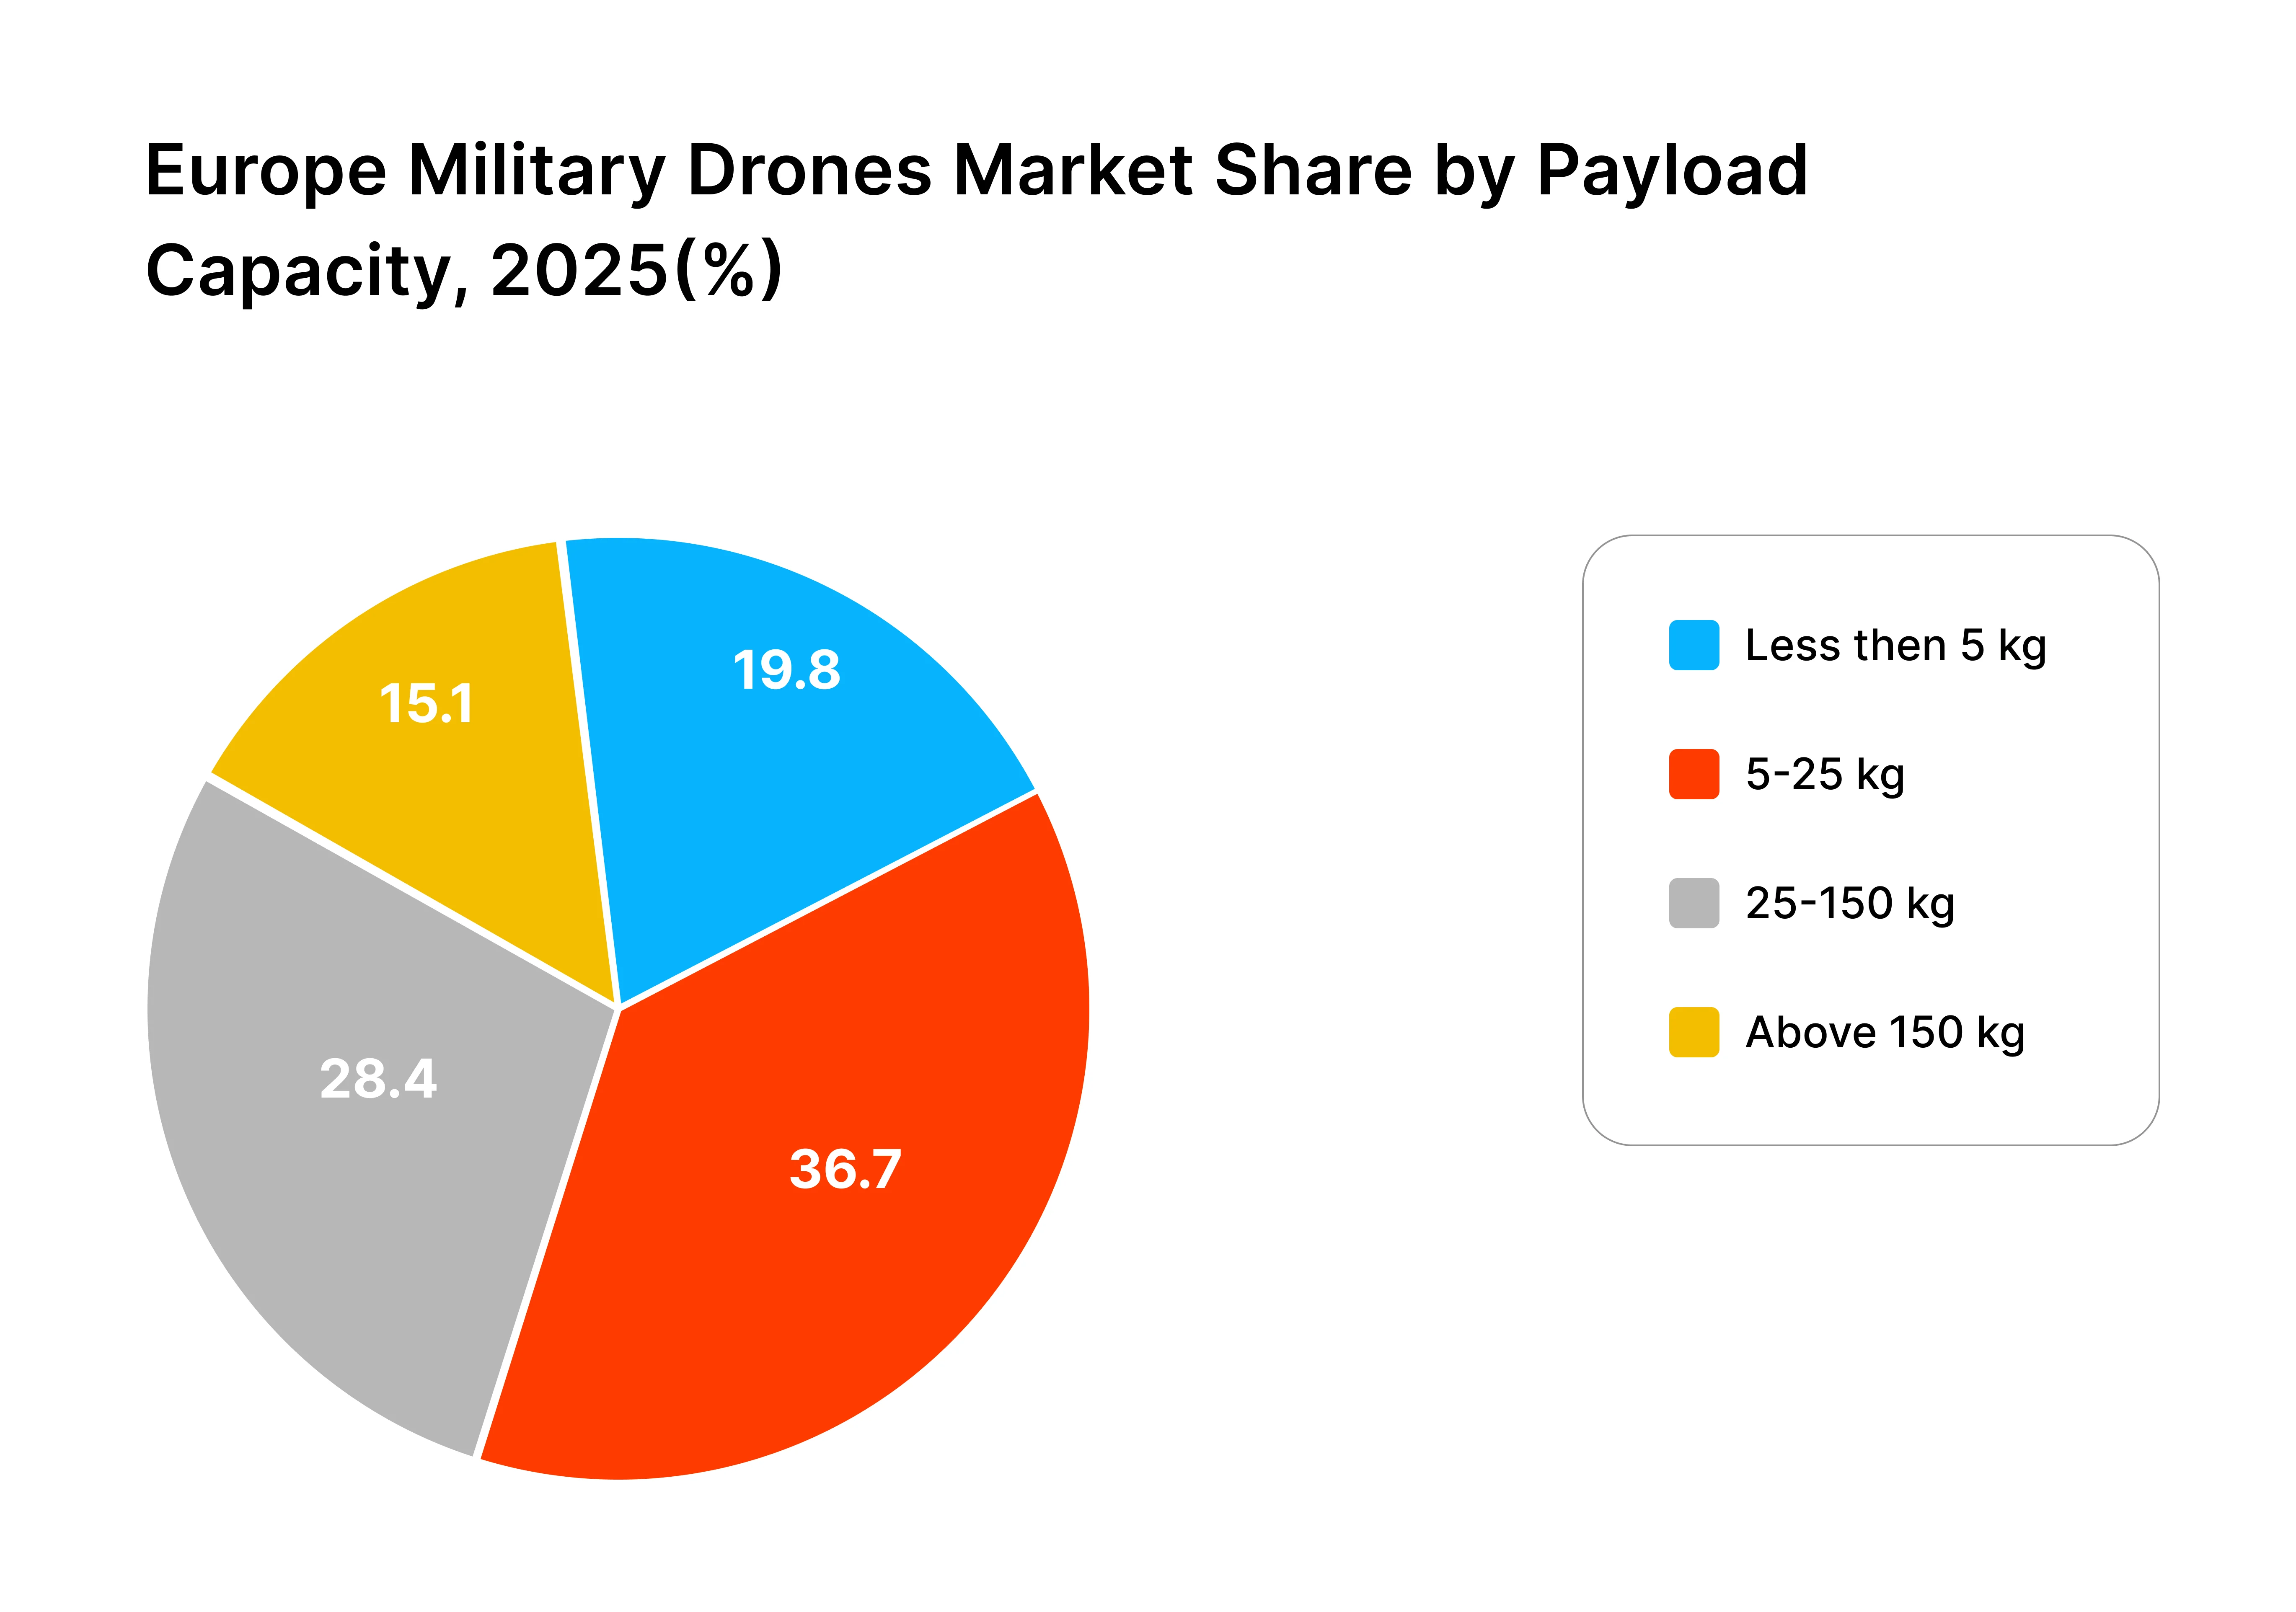
The 25–150 kg segment follows as the second-largest category, with defense organizations increasingly utilizing these platforms for extended-endurance reconnaissance, border surveillance, maritime patrol, and logistics support. The larger payload capacity allows for the simultaneous integration of multiple sensors, secure communication systems, electronic warfare equipment, and precision-guided payloads, thereby increasing mission versatility.
On the other hand, the less than 5 kg category maintains steady adoption for tasks such as dismounted infantry reconnaissance, urban combat operations, and rapid battlefield assessments, where portability and quick deployment take precedence over payload limits. Although the above 150 kg segment accounts for the smallest market volume, it significantly contributes to market value, as these high-end platforms provide strategic ISR capabilities, long-range surveillance, satellite communication, heavy sensor packages, and facilitate persistent multi-domain operations.
In Europe, procurement priorities are increasingly leaning towards optimizing payload capabilities rather than focusing solely on platform size. This shift is driving manufacturers to create modular architectures that enable the rapid interchange of ISR, electronic warfare, communications, and logistics payloads, allowing them to adapt to evolving mission requirements without the need to invest in entirely new drone platforms.
By Country: United Kingdom and France Lead Europe's AI-Enabled Military Drone Development through Advanced Defense Innovation
The United Kingdom currently holds the largest share of Europe’s AI-enabled military drone market. This dominance is supported by significant investments in autonomous systems, AI-assisted intelligence, surveillance, and reconnaissance (ISR), as well as collaborative combat technologies. The UK’s defense ecosystem is bolstered by leading aerospace and defense companies, advanced AI research institutions, and government initiatives that emphasize autonomous decision-support, swarming technologies, and human-machine collaboration for future battlefield operations.
France closely follows the UK, driven by a strong integration of artificial intelligence into next-generation optronics, autonomous mission planning, and defense electronics. This progress is supported by national defense modernization programs and collaborative European research initiatives.
Germany ranks third, focusing on AI-enabled tactical reconnaissance drones, sensor fusion technologies, and autonomous navigation systems. The country is also increasing its investment in domestic UAV manufacturing and digital battlefield capabilities.
Italy is enhancing its position in the market through the development of AI-supported ISR platforms and active participation in multinational European unmanned aviation programs. Meanwhile, Spain and Poland are emerging as noteworthy contributors, particularly in the areas of tactical UAV production, border surveillance, and AI-assisted mission automation.
Smaller markets like Sweden, Norway, the Netherlands, Finland, and the Baltic states are honing their expertise in niche capabilities such as Arctic surveillance, electronic warfare, resilient communications, and autonomous maritime operations. Across Europe, the competitive edge is increasingly determined by the ability to integrate edge AI processors, autonomous target recognition, multi-sensor fusion, secure communications, and interoperable command-and-control frameworks.
As a result, countries with well-developed defense industrial bases, established AI ecosystems, and consistent investment in autonomous military technologies are poised to maintain leadership in Europe’s AI-enabled military drone landscape for the foreseeable future.
Competitive Analysis
Key companies considered within the Europe military drones market are: BAE Systems, Tekever, Safran Electronics & Defense, Thales, Delair, Parrot, Airbus Defence and Space, Leonardo, Sky Eye Systems, Alpha Unmanned Systems, SAAB, Others.
Epignosis Insights Competitive Assessment Framework (EICAF)
This internal analytical model is designed to evaluate the strategic positioning and competitive strength of leading military drone manufacturers operating in the European market. Instead of comparing companies solely by revenue or product count, the framework assesses their overall competitiveness across various dimensions including technology, manufacturing, innovation, and market execution capabilities.
| Assessment Parameter |
Weight (%) |
| Product Portfolio Breadth |
25% |
| AI & Autonomous Capabilities |
12% |
| ISR & Sensor Integration |
10% |
| Government & NATO Contracts |
9% |
| Production Capacity |
8% |
| Technology Innovation |
11% |
| Strategic Partnerships |
7% |
| Geographic Presence |
5% |
| Export Capability |
4% |
| R&D Investment |
6% |
| Financial Strength |
3% |
The framework encompasses several key evaluation parameters such as the breadth of the product portfolio, capabilities in artificial intelligence and autonomy, integration of intelligence, surveillance, and reconnaissance (ISR) and sensors, offerings of vertical take-off and landing (VTOL) and fixed-wing platforms, as well as government and NATO defense contracts. It also evaluates aspects like production capacity, R&D intensity, strategic partnerships, indigenous manufacturing capabilities, export presence, technology innovation, and financial strength. Participation in multinational European defense programs, platform scalability, and the capacity to meet evolving military requirements including electronic warfare, swarm operations, secure communications, and multi-domain missions are also taken into account.
By benchmarking companies against these factors, the framework delivers a structured perspective on competitive differentiation, helping to identify market leaders and emerging challengers while supporting strategic analysis of the military drones market in Europe.
Related Insights
AI, ELINT & SIGINT: Transforming Europe's Military Drone Ecosystem
Tactical Military Drones Driving Europe's Defense Modernization
European UAV Readiness Index: Military Drone Rankings

