Key Finding
- Europe Edge AI market is witnessing strong growth, driven by increasing adoption of AI inference at the edge across manufacturing, automotive, healthcare, and telecommunications.
- Germany, the United Kingdom, and France collectively account for over 45% of the Europe Edge AI market, supported by advanced industrial automation and AI investments.
- AI Processors hold the largest hardware share (~29.5%), reflecting growing demand for dedicated NPUs and AI SoCs in edge computing applications.
- Industrial predictive maintenance solutions are reducing unplanned equipment downtime by 30–50%, accelerating investments in the Europe Edge AI market.
- Private 5G deployment and Industry 4.0 initiatives are significantly expanding real-time Edge AI applications across factories, logistics hubs, and energy infrastructure.
- The EU AI Act and EU Chips Act are strengthening regulatory compliance and encouraging domestic AI semiconductor innovation across the Europe Edge AI market.
- High deployment costs and dependence on imported high-performance AI chipsets remain key challenges for widespread enterprise adoption.
Europe Edge AI Market Outlook
Europe Edge AI Market recorded a market value of USD 6,540 million in 2025 and is estimated to reach a value of USD 40,907 million by 2033 with a CAGR of 26.2% during the forecast period. In terms of volume, AI chipset recorded a volume demand of 212 million units in 2024.
Growing Adoption of Edge AI for Predictive Maintenance in Energy, Utilities, and Heavy Industrial Operations
The increasing implementation of Edge AI for predictive maintenance is becoming a significant driver of growth in the Europe Edge AI market, especially within industries such as energy generation, utilities, chemicals, mining, steel, and heavy manufacturing. In these sectors, unplanned equipment failures can lead to substantial production losses. Unlike traditional cloud-based analytics, Edge AI allows machine learning models to process sensor data directly on the industrial assets themselves. This capability enables rapid execution of tasks such as vibration analysis, thermal imaging, acoustic monitoring, and motor diagnostics in mere milliseconds without the need for constant cloud connectivity.
Industrial equipment like gas turbines, transformers, compressors, pumps, wind turbines, and high-voltage switchgear generate vast amounts of operational data each year, necessitating localized AI inference for effective real-time anomaly detection. Industry estimates suggest that predictive maintenance can reduce unplanned equipment downtime by 30-50%, decrease maintenance costs by 15-30%, and extend equipment life by 20-40%. This approach is also capable of enhancing overall equipment effectiveness (OEE) by as much as 20%. These tangible operational benefits are spurring investments in embedded AI processors, industrial edge gateways, and AI-enabled condition monitoring systems across Europe.
The region’s growing renewable energy sector is further driving demand, with wind farms, offshore platforms, and large-scale solar facilities increasingly utilizing Edge AI to monitor blade health, inverter performance, battery storage systems, and grid assets in real time. Countries such as Germany, France, the Netherlands, Denmark, and those in the Nordic region are leading the way in adoption, due to their robust industrial automation capabilities and comprehensive renewable energy infrastructure. Utilities are also enhancing their operations by integrating Edge AI with digital substations and smart grid assets to identify transformer degradation, cable faults, and voltage irregularities before service interruptions can occur.
The rollout of private 5G networks and industrial IoT platforms is further bolstering the effectiveness of predictive maintenance through low-latency communication between distributed sensors and Edge AI devices. As manufacturers aim for more autonomous operations, lower maintenance-related expenditures, and improved asset utilization, predictive maintenance is expected to remain one of the most valuable applications shaping technology investments and commercial deployments in the Europe Edge AI market throughout the forecast period.
High Deployment Costs Associated with Industrial-Grade Edge AI Hardware and AI Inference Infrastructure
High deployment costs associated with industrial-grade Edge AI hardware and AI inference infrastructure pose significant barriers to broader adoption within the European Edge AI market, particularly for small and medium-sized manufacturers and utilities that have limited budgets for digital transformation. Unlike traditional industrial automation systems, Edge AI deployments necessitate high-performance AI processors, industrial-grade GPUs or NPUs, rugged edge servers, smart sensors, industrial gateways, high-speed networking equipment, cybersecurity software, and AI lifecycle management platforms.
For instance, a single industrial Edge AI gateway typically costs between USD 1,500 and USD 5,000, while rugged edge servers equipped with AI accelerators can range from USD 10,000 to USD 50,000, depending on their compute capability and environmental specifications. Large manufacturing facilities that deploy hundreds of AI-enabled cameras, vibration sensors, and edge computing nodes often require multi-million-dollar capital investments before they can realize operational benefits.
Additionally, organizations incur further expenses on software licensing, AI model optimization, system integration, cybersecurity compliance, employee training, and ongoing maintenance. In sectors like automotive, chemicals, steel, pharmaceuticals, and energy, many companies operate legacy operational technology (OT) systems that need considerable customization for Edge AI platform integration, resulting in implementation costs rising by 20–35% compared to greenfield facilities.
Moreover, stringent European cybersecurity requirements such as compliance with GDPR, the NIS2 Directive, and the EU AI Act complicate matters, as they demand secure hardware architectures, encrypted edge communication, and continuous AI model governance, which further inflate total deployment costs. Organizations also need to factor in expenses related to validating AI models for safety-critical applications, especially in industries like automotive manufacturing, rail infrastructure, and power generation.
While declining semiconductor prices and the rise of dedicated AI accelerators are gradually making project economics more favorable, the return on investment continues to be highly influenced by deployment scale and operational complexity. As a result, large enterprises tend to dominate implementation, while many SMEs are opting for phased deployment strategies that focus on high-value assets before expanding across entire production facilities. To accelerate long-term adoption across the European Edge AI market, addressing these cost barriers through standardized hardware platforms, AI-as-a-Service models, and government-supported digitalization initiatives will be crucial.
Between 2024 and 2030, pricing trends for Edge AI processors indicate a significant divergence based on chip architecture in response to scale and competition. Neural processing units (NPUs), commonly found in smartphones, PCs, and IoT devices, are expected to experience the most drastic price drop, decreasing from approximately $15 per unit in 2024 to an estimated $6 by 2030. This reduction illustrates their evolution from a distinguishing feature to a commodity, with billions of units shipped. Manufacturing yield improvements and design standardization are driving margins down the fastest in this category.
ASIC modules will follow a similar, albeit more gradual path, with prices falling from around $275 to $120 during the same period. Specialized chips like Google's Edge TPU, which focus on vision and inference tasks, will benefit from high-volume production and maintain a more niche position compared to NPUs.
On a different scale, Edge GPUs are projected to decline from roughly $1,325 to $780. Their initial higher price is due to their broad computational versatility, but the rate of decline is more moderate. GPUs continue to be essential for compute-intensive edge workloads where raw parallel processing remains critical, and the replacement by NPUs has not yet fully materialized.
FPGAs, however, stand out as an anomaly in this market. Their pricing is expected to remain stable, fluctuating between $1,450 and $1,600 throughout the forecast period. The reprogrammability of FPGAs supports a consistent premium in low-volume, mission-critical applications. Moreover, the smaller addressable market for FPGAs limits the scale economies that affect NPU and ASIC pricing.
Overall, the data indicates a trend toward bifurcation rather than uniform commoditization. High-volume, purpose-built silicon is becoming cheaper rapidly, while flexible, lower-volume architectures are resisting price declines. For deployment strategies, this means that small and medium-sized enterprises (SMEs) and cost-sensitive adopters can anticipate significant savings on NPU and ASIC-based edge AI solutions over the next few years. Meanwhile, those relying on GPUs and FPGAs will likely continue to face cost challenges well into the decade, exacerbating the system-level cost issues already confronting smaller manufacturers and utility providers.
Segment & Country Level Analysis
Heterogeneous Computing Architectures Strengthen Edge AI Hardware Deployment Across Europe
The hardware ecosystem within the Europe Edge AI market is experiencing rapid evolution as enterprises move away from traditional embedded computing towards heterogeneous AI architectures that offer low-latency inference at the network edge. AI Processors, which comprise nearly 29.5% of the hardware market, have emerged as the favored computing platform due to their integration of dedicated Neural Processing Units (NPUs) and AI engines tailored for applications such as computer vision, predictive analytics, and industrial automation. Their capability to perform AI inference while consuming significantly less power than conventional processors makes them highly appealing for environments like smart factories, autonomous robots, intelligent cameras, and medical diagnostic tools.
Graphics Processing Units (GPUs) hold around 18% of the market and continue to handle compute-intensive workloads like machine vision, robotics, and generative AI inference in edge servers. However, their deployment is becoming more selective as enterprises consider the higher power consumption and costs associated with GPUs. Central Processing Units (CPUs) maintain a market share of approximately 16.5% due to their role in managing operating systems, networking tasks, and application orchestration, typically working alongside AI accelerators instead of performing inference on their own.
The rising adoption of Application-Specific Integrated Circuits (ASICs) and Edge AI Accelerators, which collectively account for over 21% of hardware demand, illustrates the industry's focus on optimization for specific applications. This focus allows for higher inference throughput while minimizing energy consumption and thermal requirements, with these devices increasingly integrated into automotive electronic control units, industrial gateways, smart surveillance systems, and healthcare equipment where reliable performance is essential.
Meanwhile, Field Programmable Gate Arrays (FPGAs) continue to be crucial for sectors like telecommunications, industrial control systems, and aerospace due to their capacity for hardware reconfigurability, which is vital to accommodating evolving AI workloads. The demand for Memory & Storage solutions is also on the rise, driven by the need for high-bandwidth memory and rapid local data access to enable real-time inference without relying on cloud services.
As European industries progress in their digital transformation efforts backed by initiatives like the EU Chips Act, Industry 4.0 programs, and the expansion of private 5G networks hardware investments are increasingly pivoting towards specialized AI silicon that balances computational performance, power efficiency, cybersecurity, and long-term operational reliability. This shift is expected to be a significant factor in shaping technology investments across the Europe Edge AI market throughout the forecast period.
Western Europe Continues to Lead Edge AI Deployment While Central Europe Accelerates Adoption
The geographic spread of Edge AI technologies across Europe reveals a notable correlation among industrial digitalization, semiconductor capabilities, AI research intensity, and enterprise investment in real-time computing infrastructure. Germany leads the European Edge AI market, with an estimated 38% enterprise penetration. This significant adoption showcases the extensive implementation of AI-enabled machine vision, predictive maintenance, collaborative robotics, and intelligent quality inspection, particularly in the automotive, machinery, and advanced manufacturing sectors.
Following Germany, the United Kingdom shows approximately 35% penetration, largely fueled by strong adoption in financial services, healthcare diagnostics, defense technologies, and AI software development, supported by one of the largest AI startup ecosystems in Europe. France and the Netherlands are emerging as strategic growth hubs, investing in aerospace, industrial automation, semiconductor design, logistics optimization, and smart port infrastructure, with penetration rates exceeding 30%.
Countries like Sweden, Denmark, Finland, and Norway are also expanding their adoption of Edge AI by integrating it into telecommunications equipment, renewable energy assets, industrial robotics, maritime operations, and autonomous mobility solutions, leveraging the region's advanced digital infrastructure and the deployment of private 5G networks. Despite its smaller market size, Switzerland exhibits robust adoption, driven by precision manufacturing, pharmaceutical production, and high-value medical technology applications that require secure, low-latency AI inference.
Southern and Central European nations, including Italy, Austria, Poland, the Czech Republic, and Portugal, represent the next wave of market expansion as manufacturers modernize their production facilities under Industry 4.0 initiatives. These countries are increasing investments in AI-enabled automation to boost productivity and operational resilience, with enterprise penetration currently ranging from 16% to 28%. The availability of European Union digital funding programs and rising investments in local AI infrastructure are expected to reduce the adoption gap in the coming years.
Looking ahead, future market expansion will heavily rely on the availability of skilled AI professionals, resilience in semiconductor supply, integration of industrial cloud-edge systems, and compliance with regulations under the EU AI Act. As AI processing continues to shift from centralized cloud environments to distributed intelligent devices, the European Edge AI market is anticipated to experience stronger adoption in both mature economies and emerging digital manufacturing hubs, fostering a more balanced regional growth landscape throughout the forecast period.
Competitive Analysis
Key companies analyzed within the Europe Edge AI market are: NVIDIA Corporation, Intel Corporation, Advanced Micro Devices, Inc. (AMD), QUALCOMM Incorporated, Arm Holdings plc, STMicroelectronics N.V., Infineon Technologies AG, NXP Semiconductors N.V., Texas Instruments Incorporated, Siemens AG, Robert Bosch GmbH, Schneider Electric SE, ABB Ltd., Advantech Co., Ltd., Cisco Systems, Inc., Dell Technologies Inc., Hewlett Packard Enterprise Development LP, Lenovo Group Limited, IBM Corporation, Microsoft Corporation and others.
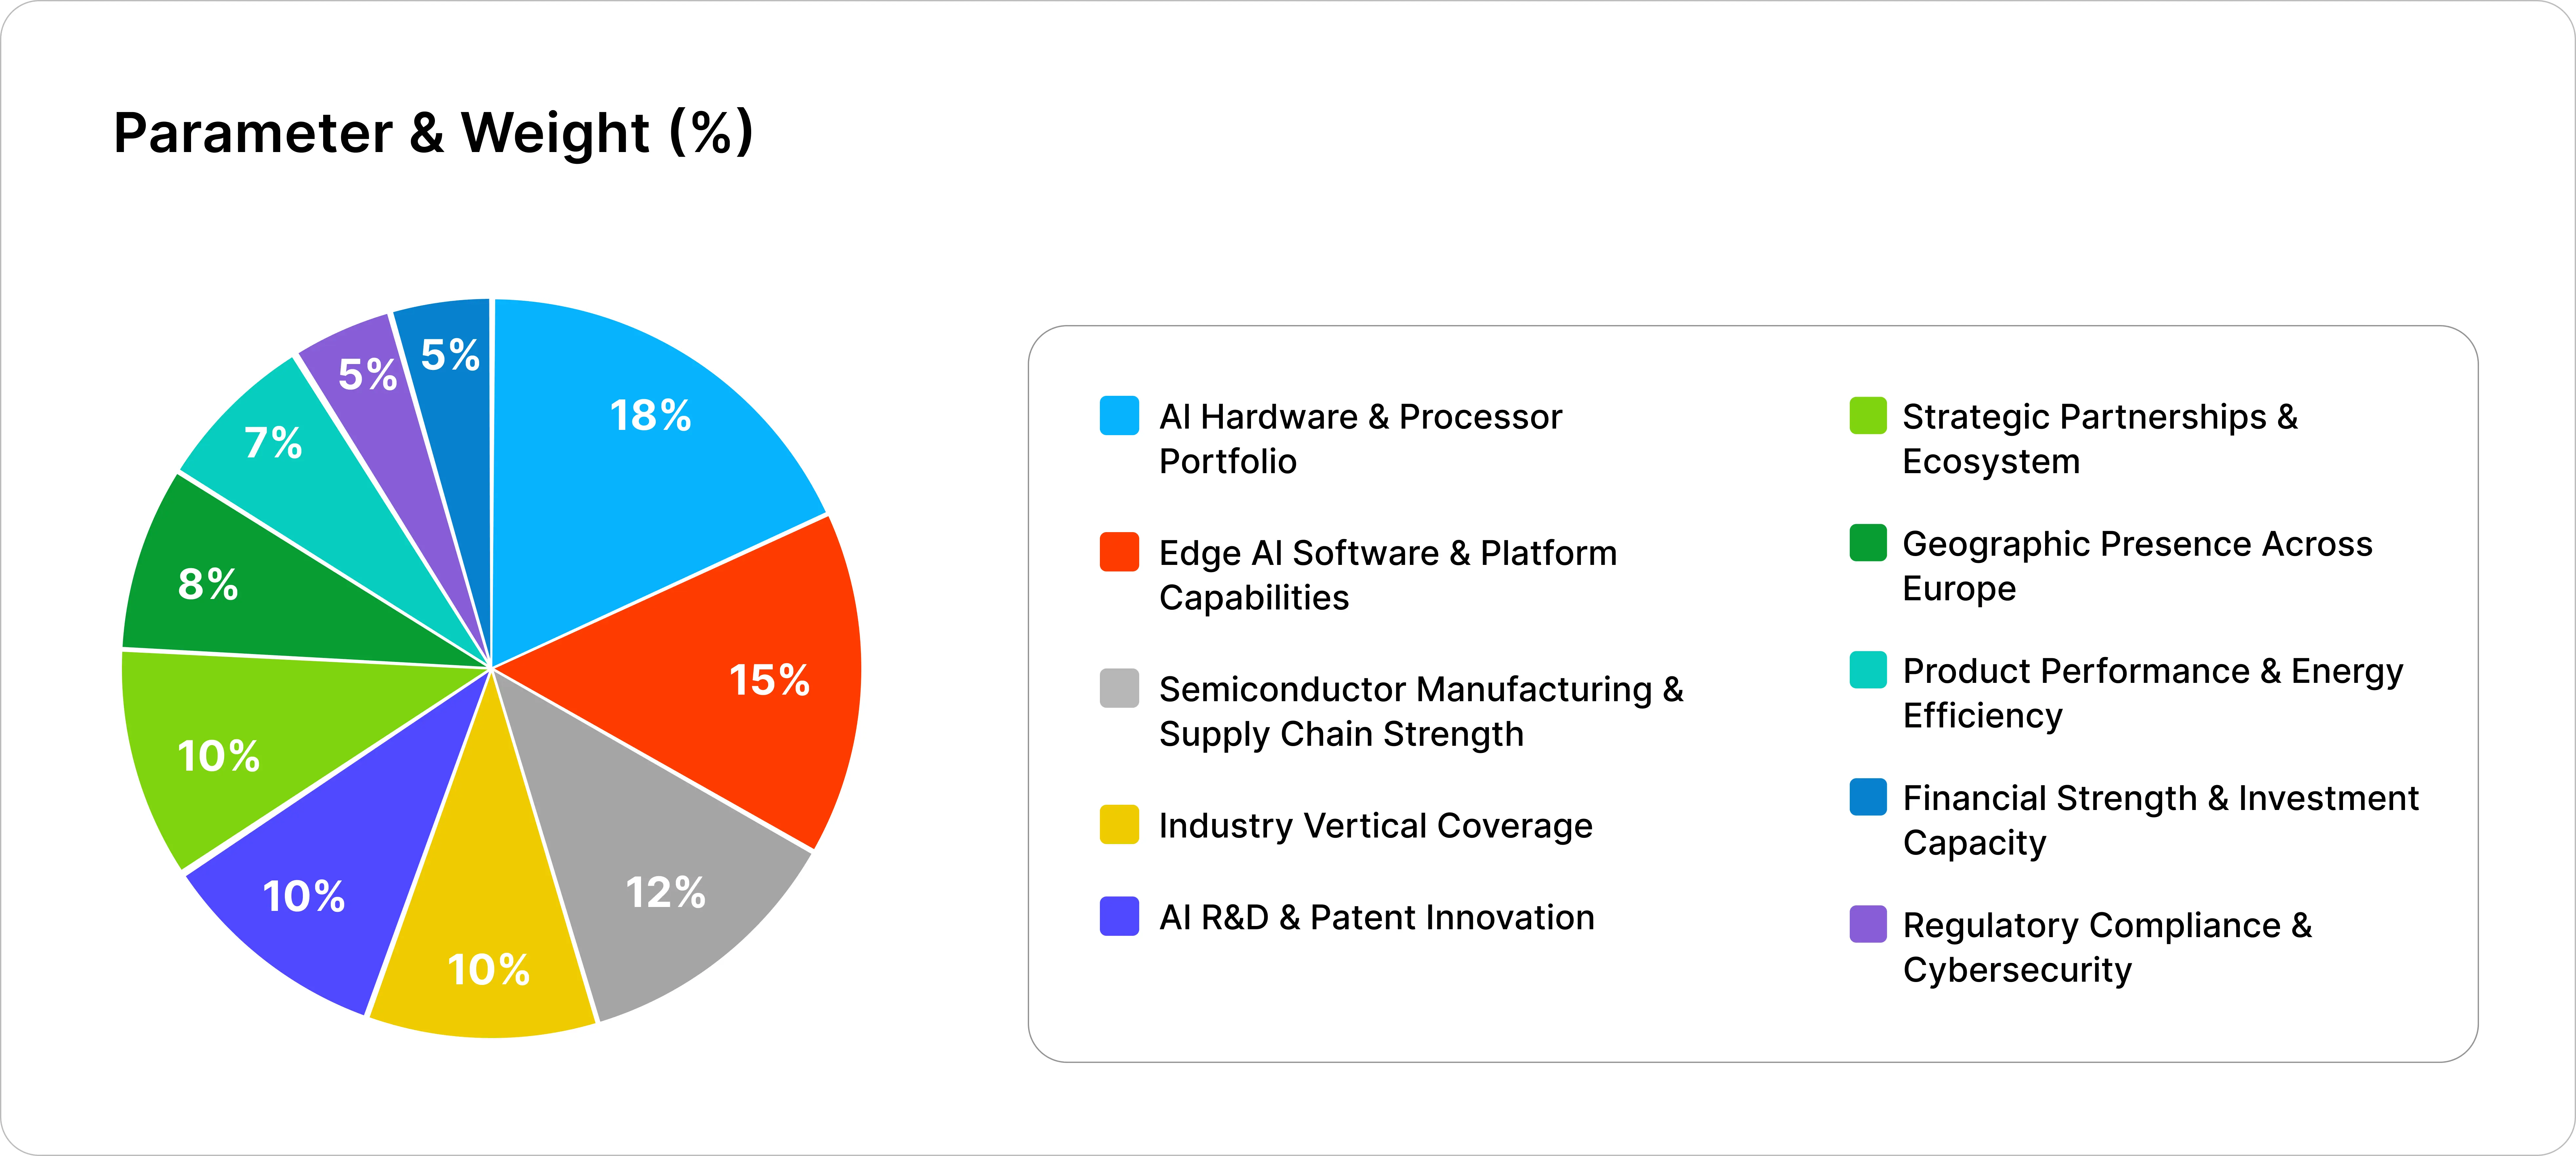
Epignosis Insights Competitive Assessment Framework (EICAF)
The geographic spread of Edge AI technologies across Europe reveals a notable correlation among industrial digitalization, semiconductor capabilities, AI research intensity, and enterprise investment in real-time computing infrastructure.
Germany leads the European Edge AI market, with an estimated 38% enterprise penetration. This significant adoption showcases the extensive implementation of AI-enabled machine vision, predictive maintenance, collaborative robotics, and intelligent quality inspection, particularly in the automotive, machinery, and advanced manufacturing sectors.
Following Germany, the United Kingdom shows approximately 35% penetration, largely fueled by strong adoption in financial services, healthcare diagnostics, defense technologies, and AI software development, supported by one of the largest AI startup ecosystems in Europe. France and the Netherlands are emerging as strategic growth hubs, investing in aerospace, industrial automation, semiconductor design, logistics optimization, and smart port infrastructure, with penetration rates exceeding 30%.
Countries like Sweden, Denmark, Finland, and Norway are also expanding their adoption of Edge AI by integrating it into telecommunications equipment, renewable energy assets, industrial robotics, maritime operations, and autonomous mobility solutions, leveraging the region's advanced digital infrastructure and the deployment of private 5G networks. Despite its smaller market size, Switzerland exhibits robust adoption, driven by precision manufacturing, pharmaceutical production, and high-value medical technology applications that require secure, low-latency AI inference.
Southern and Central European nations, including Italy, Austria, Poland, the Czech Republic, and Portugal, represent the next wave of market expansion as manufacturers modernize their production facilities under Industry 4.0 initiatives. These countries are increasing investments in AI-enabled automation to boost productivity and operational resilience, with enterprise penetration currently ranging from 16% to 28%. The availability of European Union digital funding programs and rising investments in local AI infrastructure are expected to reduce the adoption gap in the coming years.
Looking ahead, future market expansion will heavily rely on the availability of skilled AI professionals, resilience in semiconductor supply, integration of industrial cloud-edge systems, and compliance with regulations under the EU AI Act. As AI processing continues to shift from centralized cloud environments to distributed intelligent devices, the European Edge AI market is anticipated to experience stronger adoption in both mature economies and emerging digital manufacturing hubs, fostering a more balanced regional growth landscape throughout the forecast period.

