Key Findings
- Premium skincare accounts for 50–60% of premium personal care spending, driven by clinically proven, biotech-based, and personalized products.
- China, South Korea, and Japan lead the market through premium demand, innovation, and science-backed anti-aging skincare.
- Ingredient transparency, clinical efficacy, AI personalization, and dermatologist recommendations are key purchase drivers.
- India, Indonesia, Vietnam, and Thailand are the fastest-growing markets, supported by rising incomes, urbanization, and e-commerce growth.
- Localized ingredients and premium packaging are improving supply chain resilience and speeding up product launches.
- Innovation, digital engagement, and sustainability are the primary competitive advantages driving long-term growth in the Asia Premium Personal Care Market.
Asia Premium Personal Care Market Outlook
Asia Premium Personal Care Market recorded a market value of USD 69.9 billion and is estimated to reach a value of 137.4 billion by 2033 with a CAGR of 9.1% during the forecast period.
Asia Premium Personal Care Market Dynamics
Strong Influence of K-Beauty, J-Beauty, and C-Beauty Innovation Ecosystems on Regional Purchasing Behavior
The Asia Premium Personal Care Market is witnessing significant transformation driven by the competitive innovation landscape among K-Beauty, J-Beauty, and C-Beauty ecosystems, which are collectively reshaping premium beauty purchasing behaviors throughout the region. These ecosystems are not just competing on brand recognition; they are advancing through formulation science, rapid commercialization, ingredient innovation, digital engagement, and consumer education.
| Parameter |
K-Beauty |
J-Beauty |
C-Beauty |
| Innovation philosophy |
Trend-led, multifunctional skincare |
Science-led, preventive skincare |
Digital-first, consumer-driven innovation |
| Product development cycle |
6–12 months |
18–36 months |
3–9 months |
| Primary competitive advantage |
Fast innovation, viral launches |
Clinical validation, premium efficacy |
AI-enabled development, agile commercialization |
| Key consumer proposition |
Glass skin, hydration, barrier repair |
Longevity, skin health, simplicity |
Personalization, localized innovation |
| Flagship ingredients |
Centella asiatica, fermented extracts, snail mucin, PDRN |
Hyaluronic acid, ceramides, collagen, rice ferment |
Peptides, recombinant collagen, probiotics, TCM botanicals |
| R&D intensity |
Very high |
Very high |
High, rapidly increasing |
| Commercialization speed |
High |
Moderate |
Extremely high |
| Digital commerce integration |
High |
Moderate |
Very high |
| Social commerce influence |
High |
Moderate |
Extremely high |
| AI & consumer data utilization |
High |
Moderate |
Very high |
| Premium pricing position |
Mid-premium to prestige |
Prestige to luxury |
Affordable premium to prestige |
| Consumer trust driver |
Innovation, visible results |
Scientific credibility, safety |
Technology, customization, value |
| Packaging strategy |
Functional, trend-focused, sustainable |
Elegant, minimalist, premium |
Interactive, smart, customizable |
| Global expansion model |
K-pop, K-drama, influencers, specialty retail |
Department stores, pharmacies, luxury retail |
Cross-border e-commerce, digital ecosystems |
| Market strength |
Global trend creation |
Premium skincare leadership |
Rapid domestic scaling, digital engagement |
| Primary weakness |
Short product life cycles, trend dependency |
Slower commercialization of innovations |
Lower international premium brand recognition |
South Korea continues to set the standard for swift innovation in the beauty sector, boasting one of the world's fastest cosmetic product development cycles, typically ranging from 6 to 12 months. This allows brands to quickly bring trending ingredients such as PDRN, exosomes, Centella Asiatica, fermented extracts, and microbiome-based actives to market, outpacing global competitors. In 2024, Korean cosmetic exports surpassed USD 10 billion, solidifying South Korea's position as the world's second-largest beauty exporter, following France, and highlighting the global impact of K-Beauty’s innovations.
In contrast, J-Beauty distinguishes itself through a focus on scientific credibility, minimalist skincare routines, and promoting long-term skin health. The global J-Beauty market achieved approximately USD 40 billion in 2025, with the Asia-Pacific region contributing about 60.8% of total revenue. Premium J-Beauty products are expected to grow at a 8.8% CAGR through 2033, as consumers become more inclined to favor clinically validated formulations over trend-driven options.
C-Beauty is rapidly emerging as the most dynamic ecosystem by utilizing AI-driven consumer analytics, social commerce, biotechnology, and agile manufacturing processes, enabling product launches within 3 to 9 months. This approach allows local brands to swiftly adapt to online consumer feedback and translate it into commercially successful products. The rise of livestream commerce, influencer networks, and proprietary peptide technologies has further accelerated premium adoption among younger consumers.
Overall, the competitive dynamics across Asia are shifting purchasing behaviors towards values such as ingredient transparency, efficacy validation, dermatologist recommendations, and personalized skincare, rather than merely relying on traditional luxury branding. As a result, multinational companies are establishing regional R&D centers in China, Japan, and South Korea, while also increasing investments in localized formulations tailored for Asian skin types. This evolution is enhancing innovation intensity, compressing product life cycles, and boosting the penetration of premium products. Thus, technological differentiation and scientific credibility are becoming the key competitive advantages within the Asia Premium Personal Care Market.
High Dependence on Imported Active Ingredients and Luxury Packaging Materials
The Asia Premium Personal Care Market is currently navigating a significant structural challenge due to its heavy reliance on imported specialty active ingredients and high-end packaging components. Despite Asia being a leading manufacturing hub for cosmetics, premium formulations have become increasingly dependent on advanced ingredients such as biomimetic peptides, encapsulated retinol, recombinant collagen, ceramides, stabilized vitamin derivatives, marine bioactives, and specialty fragrance compounds. These ingredients are mainly sourced from suppliers located in Europe, the United States, Japan, and South Korea, known for their proprietary technologies and patented manufacturing methods.
Similarly, luxury packaging options, including airless dispensing systems, metallized caps, thick-walled glass bottles, premium pumps, recyclable mono-material packaging, and high-clarity acrylic containers, are often imported from established manufacturers in France, Italy, Germany, and specialized Asian suppliers. This reliance contributes to increased procurement complexity and production costs. As a result, premium beauty manufacturers face exposure to currency fluctuations, geopolitical trade disruptions, shipping delays, and variations in freight costsall of which can pressure profit margins, particularly since packaging can represent 20–40% of the manufacturing cost of finished products, considerably more than in the mass-market segment.
Additionally, extended procurement lead times for patented ingredients and customized packaging hinder manufacturers' ability to swiftly respond to evolving consumer preferences, especially in the premium skincare sector, where innovation cycles are shortening. As regional consumers demand clinically validated formulations, refillable luxury packaging, and unique sensory experiences, brands are tasked with finding a balance between innovation and supply chain resilience.
In response, many leading manufacturers are investing in regional biotechnology capabilities, localized ingredient extraction, and domestic premium packaging production to lessen their reliance on imports while preserving product quality and luxury appeal. Building strategic partnerships with local biotechnology firms, sustainable packaging manufacturers, and advanced materials suppliers is becoming a crucial component of competitive strategy. This approach allows brands to enhance supply security, reduce product development timelines, and mitigate cost volatility. Companies that successfully localize critical inputs without sacrificing efficacy, aesthetics, or sustainability stand to gain operational resilience and pricing flexibility, ultimately creating a sustainable competitive edge in the Asia Premium Personal Care Market.
Premiumization Index Across Asian Countries
The Premiumization Index reveals notable variations in the maturity of premium beauty consumption throughout Asia, indicating that purchasing behavior is increasingly shaped by factors such as consumer sophistication, innovation ecosystems, and digital retail infrastructure, rather than merely by population size. Leading the Asia Premium Personal Care Market is China, boasting a composite score of 82, which underscores its swift transition toward prestige skincare, luxury fragrances, and biotech-driven formulations. Chinese consumers are placing greater emphasis on clinically validated ingredients, personalized skincare solutions, and premium domestic brands, in addition to international luxury labels, all within one of the world’s most advanced social commerce frameworks.
Following closely is South Korea with a score of 78, propelled by continuous product innovation, strong consumer engagement with skincare routines, and an export-focused beauty industry that rapidly brings emerging ingredients and technologies to market. Japan, with a score of 65, illustrates a more mature premium market where purchasing decisions prioritize long-term efficacy, dermatological research, and product safety over transient trends, which has led to stable demand for high-value skincare products.
Emerging economies showcase distinct premiumization dynamics. Indonesia, scoring 48, is experiencing advantages from increasing disposable incomes, urbanization, and a rising interest in halal-certified premium cosmetics. India, with a score of 42, is witnessing premium growth primarily in metropolitan regions through omnichannel retail, dermatologist-recommended skincare solutions, and a greater acceptance of prestige international brands. Thailand and Vietnam, each with a score of 38, are still considered early-stage premium markets, yet they are strengthening through tourism, expanding specialty beauty retail, and heightened digital beauty engagement among younger consumers.
The index further demonstrates that premiumization evolves unevenly across Asia; it reflects the interplay of innovation capacity, consumer purchasing power, retail sophistication, digital adoption, and local beauty culture. As these structural factors continually develop, manufacturers are anticipated to strategically direct investments toward countries with higher premiumization scores, while also adopting localized pricing, product assortments, and channel strategies in emerging markets. This country-level disparity will persist as a defining competitive trait of the Asia Premium Personal Care Market, shaping future expansion strategies, premium product launches, and long-term revenue prospects.
Asia Premium Personal Care Market-Luxury Beauty Consumer Affluence Mapping
Methodology: The Composite Affluence Score combines five weighted parameters: disposable household income (30%), premium beauty penetration (25%), luxury retail ecosystem (20%), digital luxury commerce adoption (15%), and consumer willingness to pay for premium personal care (10%). The estimated premium personal care spending values represent average annual expenditure per consumer purchasing premium personal care products and are intended as strategic benchmarking figures for competitive analysis in the Asia Premium Personal Care Market.
Luxury beauty consumption in Asia is increasingly becoming concentrated in countries that boast expanding affluent populations, established retail environments, and consumers eager to invest in premium wellness products rather than basic personal care items. The Asia Premium Personal Care Market is witnessing a distinct divide between mature luxury markets and emerging hubs for premium consumption.
China stands out as the largest opportunity in the luxury beauty sector, largely due to its significant high-net-worth population, a growing affluent middle class, and a digitally savvy Gen Z demographic that favors biotechnology-based skincare, prestige fragrances, and personalized beauty solutions over traditional luxury branding. Meanwhile, Japan retains one of the highest per-capita expenditures on premium beauty products in the region, driven by aging consumers with substantial purchasing power who are dedicated to investing in clinically proven anti-aging skincare and dermatologist-developed formulations.
South Korea is notable for its combination of relatively high disposable income and an advanced beauty ecosystem, where consumers are quick to embrace premium innovations and are willing to invest in sophisticated formulations and aesthetic skincare. Singapore and Hong Kong serve as regional luxury retail hubs, characterized by a concentration of ultra-high-income consumers, international travelers, and premium department stores that facilitate the entry of prestigious global brands into the market.
In contrast, countries such as India, Indonesia, Vietnam, and the Philippines are transitioning from volume-driven to value-driven beauty markets. Even though their current luxury market penetration is lower, these nations are experiencing rapid income growth, urbanization, increased female workforce participation, and the rise of digital commerce, which is significantly expanding the base of potential premium consumers. These emerging markets show stronger long-term growth potential as premium consumption begins to move from elite metropolitan circles into upper-middle-income households.
As a result, brands are increasingly adopting a two-tier strategy: maintaining exclusive luxury offerings in affluent markets while introducing accessible premium product lines in high-growth emerging economies. This varied landscape of consumer affluence will continue to shape pricing strategies, retail expansion, product localization, and investment priorities, highlighting consumer purchasing power as a key factor in achieving competitive success within the Asia Premium Personal Care Market.
Asia Premium Personal Care Market – Consumer Spending Pattern
Consumer expenditure in the Asia Premium Personal Care Market is increasingly shifting from routine hygiene purchases to high-value investments in beauty products. This marks a structural transition from volume-driven consumption to a focus on premium value creation. Premium skincare remains the leading category, accounting for approximately 50–60% of total personal care spending in most developed markets, followed by premium haircare, fragrances, and specialized men’s grooming products.
| Country |
Average Annual Premium Personal Care Spending (USD/Consumer) |
Premium Share of Total Personal Care Expenditure (%) |
Fastest Growing Premium Category |
Average Purchase Frequency (per Year) |
| China |
290 |
39% |
Premium Skincare |
9–11 |
| Japan |
340 |
46% |
Anti-aging Skincare |
8–10 |
| South Korea |
315 |
44% |
Clinical Skincare & Haircare |
10–12 |
| Singapore |
420 |
48% |
Luxury Fragrances & Skincare |
8–9 |
| Australia |
270 |
36% |
Clean Beauty |
7–9 |
| Taiwan |
235 |
35% |
Functional Skincare |
8–10 |
| Malaysia |
145 |
26% |
Premium Halal Beauty |
6–8 |
| Thailand |
125 |
24% |
Prestige Cosmetics |
6–7 |
Expenditure levels vary significantly across the region, with Singapore ($420 per consumer annually), Japan ($340), South Korea ($315), and China ($290) leading in premium beauty spending, driven by higher disposable incomes, mature retail ecosystems, and a greater acceptance of prestige brands. In these markets, premium products comprise 39–48% of total personal care expenditures, indicating a trend where consumers prioritize product efficacy, clinically validated formulations, and advanced ingredients over lower prices.
China is experiencing the most rapid shift toward premium consumption, supported by digital commerce, personalized beauty recommendations, and social commerce platforms that encourage frequent purchases and product upgrades. On the other hand, countries like India, Indonesia, Vietnam, and the Philippines report lower annual premium spending ranging from $32 to $48 per consumer but possess significant long-term growth potential due to rapid urbanization, a rising number of upper-middle-income households, and increasing adoption of international premium brands through e-commerce.
A notable trend in the Asia Premium Personal Care Market is the growing concentration of consumer spending on multifunctional products that offer benefits such as hydration, anti-aging, sun protection, and skin barrier repair, enabling brands to charge higher average prices.
Additionally, subscription beauty services, limited-edition product launches, dermatologist-endorsed skincare, and AI-driven product recommendations are increasing purchase frequency, particularly among Millennials and Gen Z consumers.
As a result, future growth in spending will likely be driven less by an expanding consumer base and more by higher average transaction values, upgrades in premium product mixes, and an increased willingness among consumers to invest in science-backed formulations. This creates sustainable revenue growth opportunities for premium beauty manufacturers throughout Asia.
Competitive Analysis
Key companies analyzed within the Asia premium personal care market are: L'Oréal Group, Shiseido Company, Limited, Estée Lauder Companies Inc., LVMH (Parfums Christian Dior, Guerlain, Benefit Cosmetics, Fresh), Chanel, Amorepacific Corporation, LG Household & Health Care Ltd., Kao Corporation, Kosé Corporation, POLA ORBIS Holdings Inc., Beiersdorf AG, Puig Brands, S.A., Coty Inc., The Procter & Gamble Company, Unilever PLC, Natura &Co, Edgewell Personal Care, Oriflame Cosmetics SA, Revlon Group Holdings LLC, Mary Kay Inc. and others.
Epignosis Insights Competitive Assessment Framework (EICAF)
The Epignosis Insights Competitive Assessment Framework (EICAF) is designed to evaluate competitive positioning within the Asia Premium Personal Care Market. Rather than focusing solely on short-term sales performance, it emphasizes the strategic capabilities that contribute to long-term value creation. The framework places significant importance on Product Innovation & Pipeline, assigning it the highest weighting of 20%. This reflects the increasing competitive leadership driven by how quickly companies can commercialize biotechnology-based ingredients, personalized skincare solutions, microbiome formulations, and clinically differentiated products.
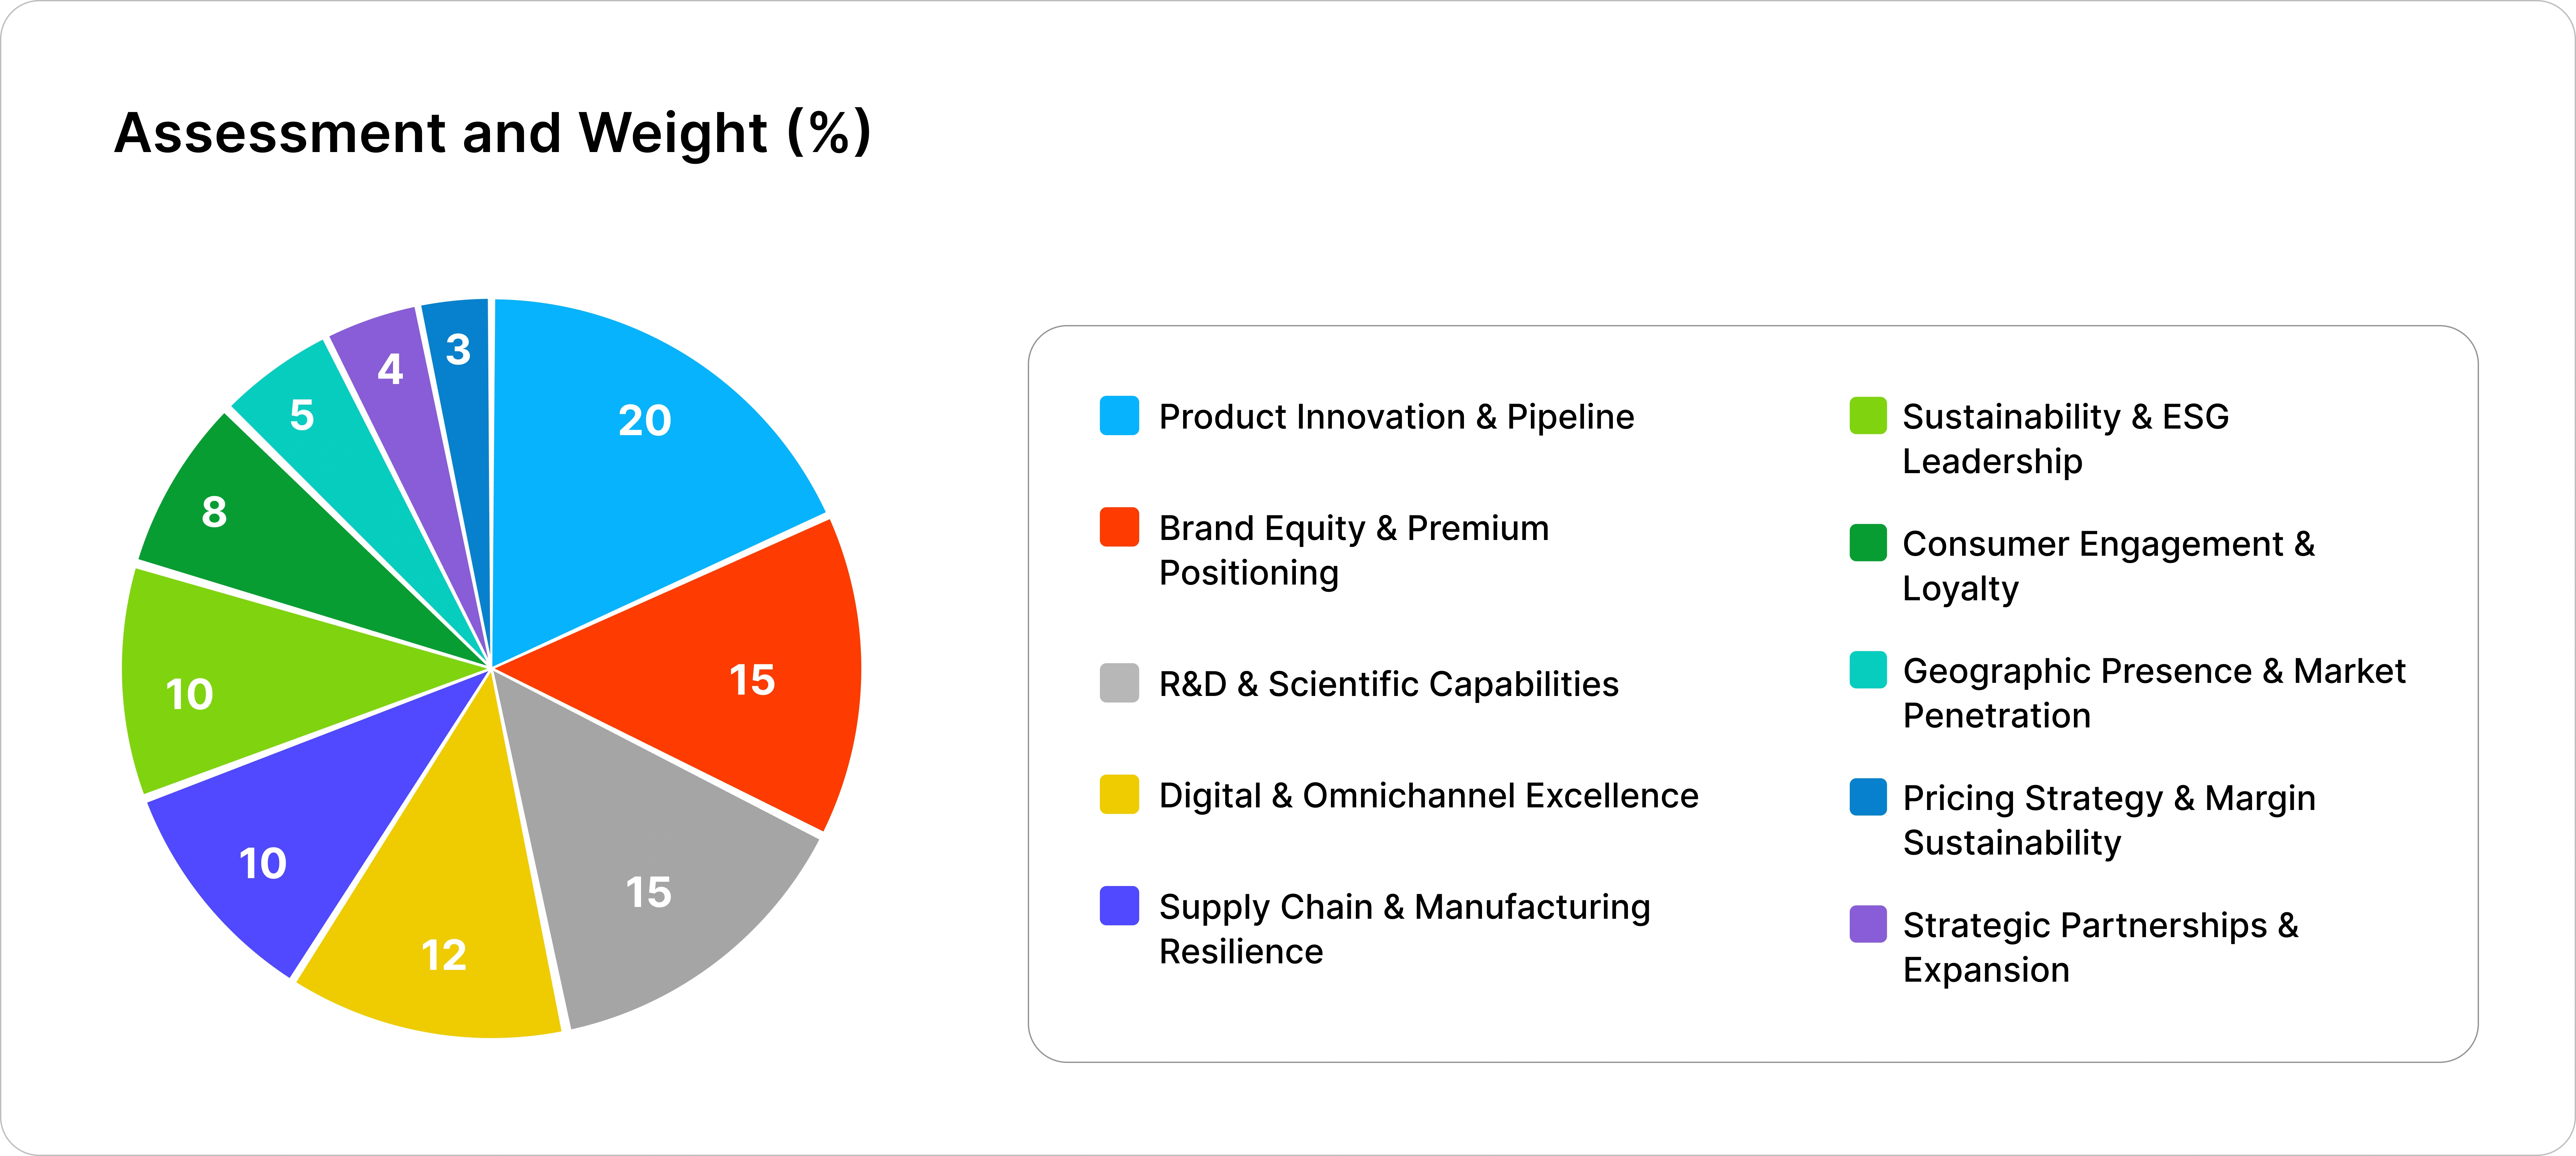
Brand Equity & Premium Positioning is given a 15% weighting, acknowledging the critical role of pricing power, consumer trust, and the necessity of maintaining premium margins in a market where consumers prioritize perceived efficacy over brand heritage. Similarly, R&D & Scientific Capabilities, also weighted at 15%, evaluates investments in dermatological research, proprietary ingredients, clinical testing, and formulation expertise, which have become key differentiators in a landscape where consumers demand evidence-backed performance.
Digital & Omnichannel Excellence, assigned a 12% weighting, reflects an organization’s proficiency in leveraging AI-powered beauty diagnostics, social commerce, direct-to-consumer platforms, and integrated retail experiences to enhance customer acquisition and retention. Additionally, the framework recognizes that operational resilience is now a strategic advantage; thus, Supply Chain & Manufacturing Resilience is weighted at 10% to assess the localization of active ingredients, manufacturing flexibility, and premium packaging capabilities that mitigate procurement risks.
Sustainability is evaluated with an 8% weighting, highlighting the increasing consumer demand for refillable packaging, responsible sourcing, and environmentally conscious manufacturing practices. Consumer Engagement & Loyalty, also weighted at 8%, measures repeat purchase habits, personalization efforts, and loyalty ecosystems that contribute to a higher customer lifetime value.
The remaining parameters consider aspects such as regional expansion, pricing discipline, and strategic collaborations, ensuring a comprehensive assessment of both commercial execution and readiness for future growth. Together, the EICAF allows investors, manufacturers, and brand owners to benchmark competitors based on innovation intensity, operational capability, and premium value creation, providing a forward-looking evaluation of sustainable competitive advantage in the Asia Premium Personal Care Market, beyond just market share or revenue metrics.

